Can You Use a Buy-to-Let Remortgage to Repay Personal Debt?
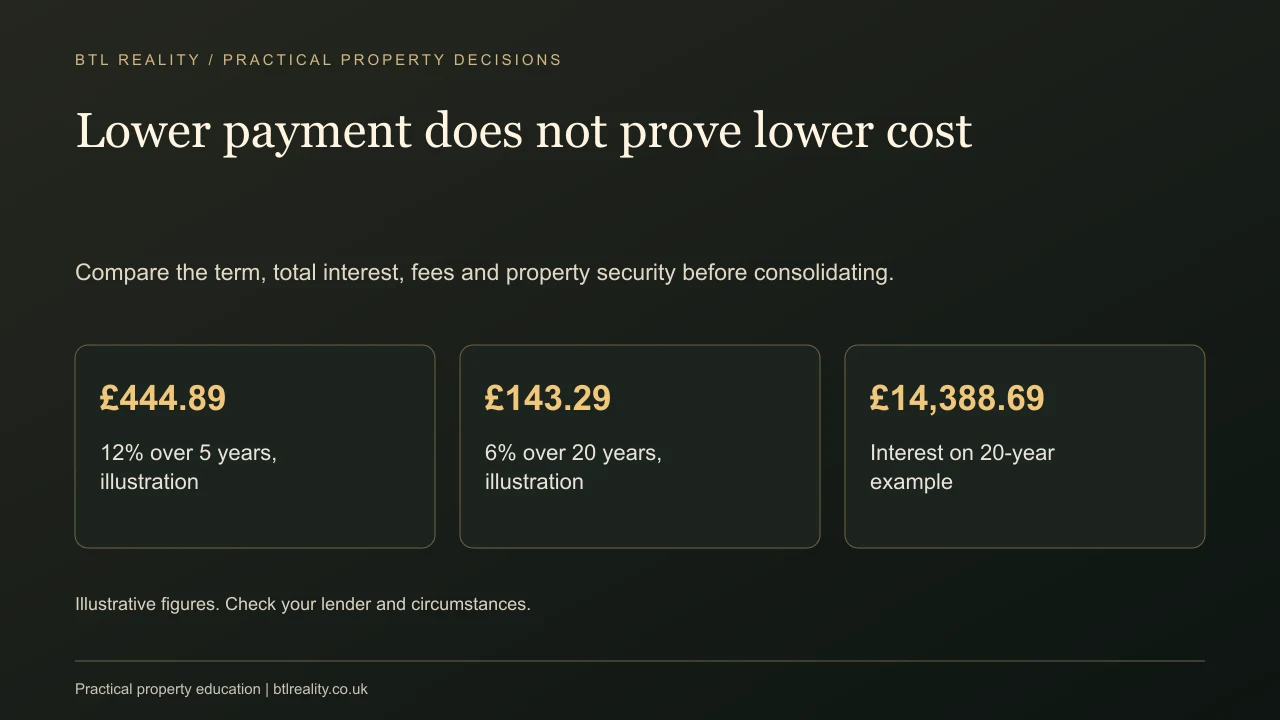
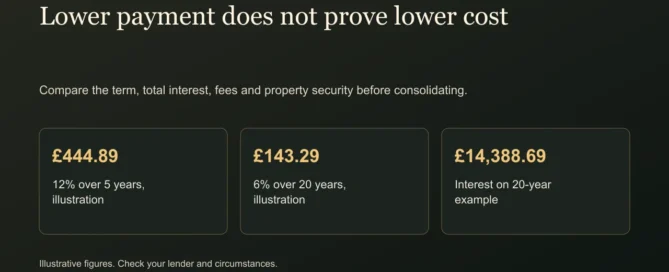
A lower monthly payment can mean a higher lifetime cost. Compare the whole mortgage and repayment plan before moving personal debt onto a rental.
A lower monthly payment can mean a higher lifetime cost. Compare the whole mortgage and repayment plan before moving personal debt onto a rental.
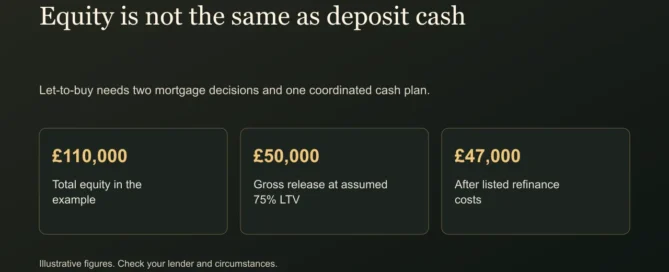
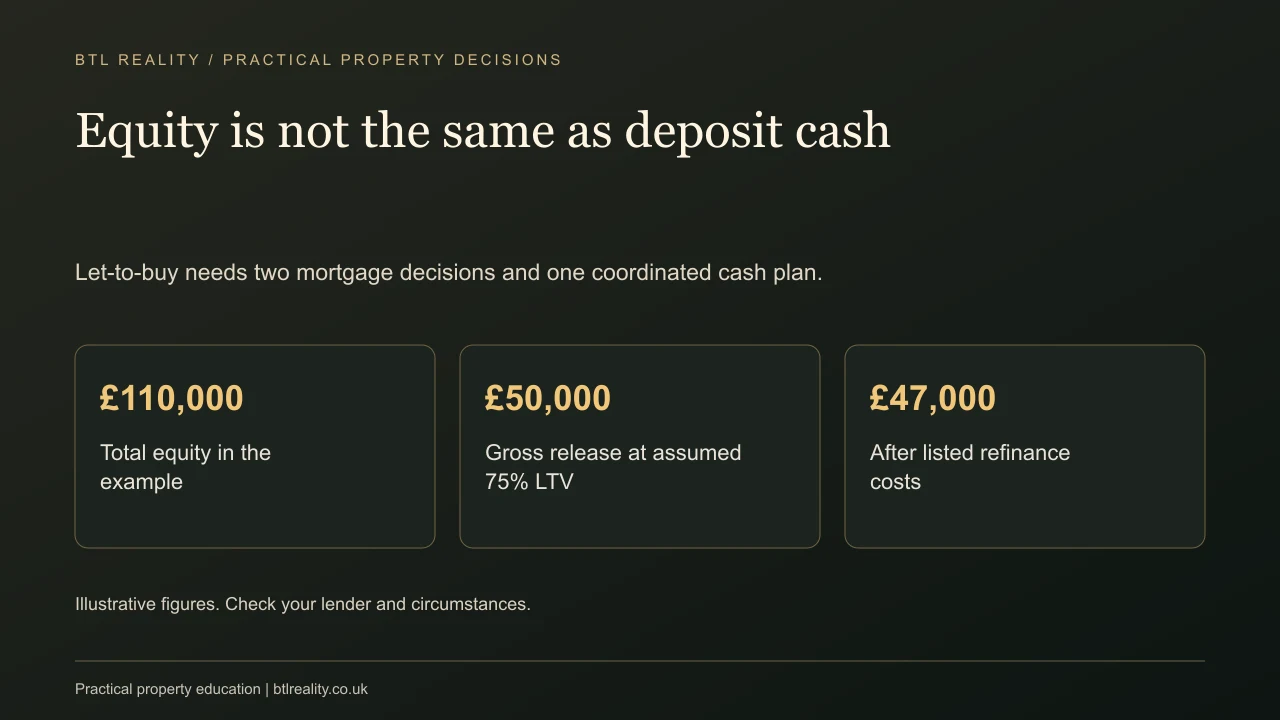
Keeping your old home can release a deposit, but total equity is not available cash. Check both mortgages and the complete moving budget.
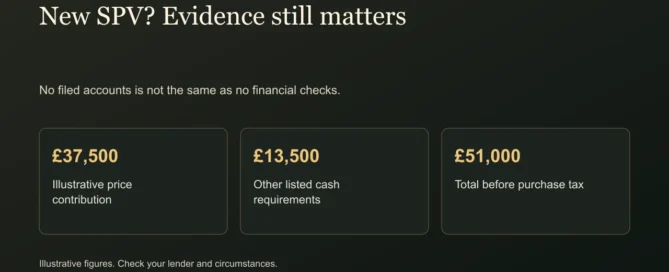
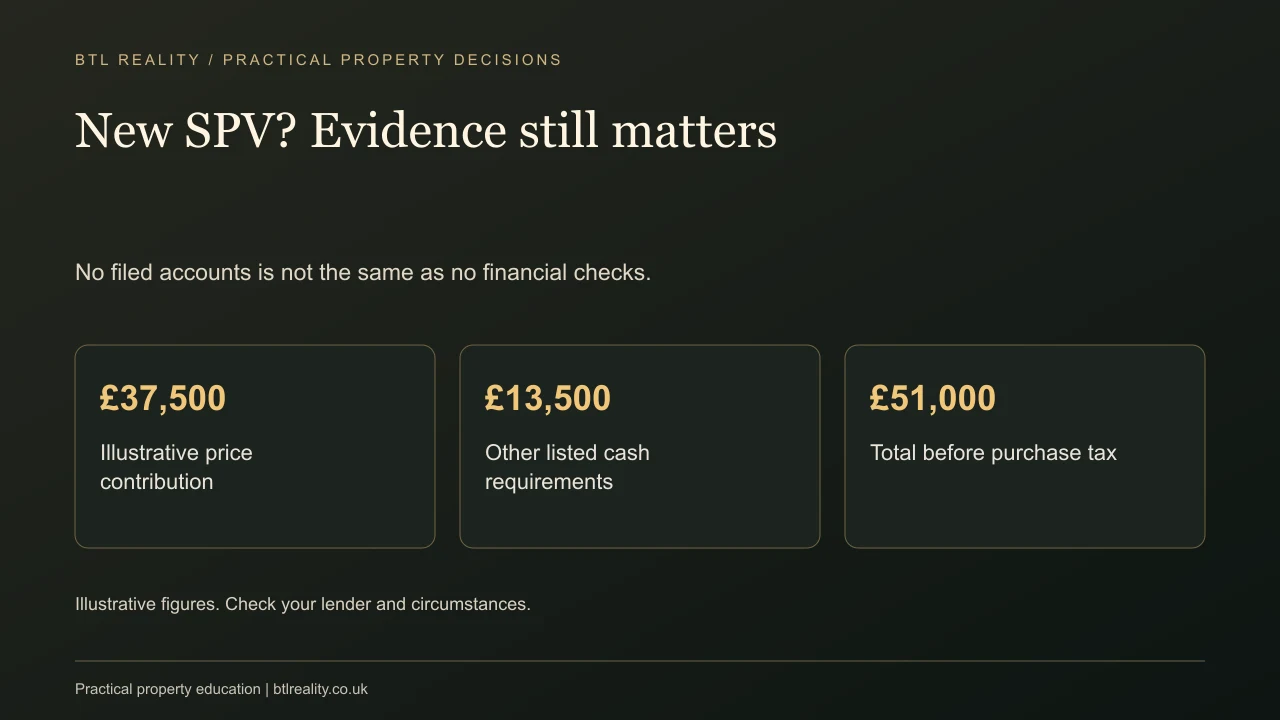
New-company acceptance still requires a complete application. Prepare the borrower, directors, funding and property evidence before committing.
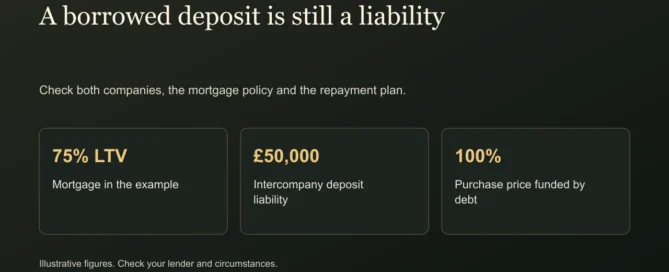
A company-funded deposit creates a second liability. Match the agreement to the lender’s rules and test both companies’ cash needs.
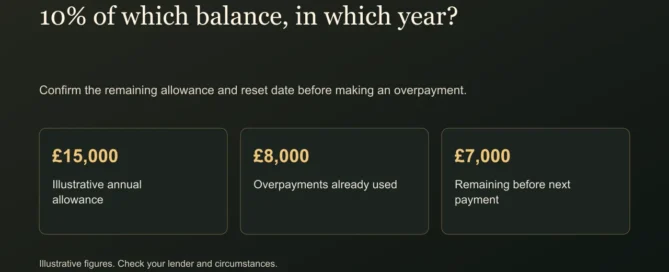
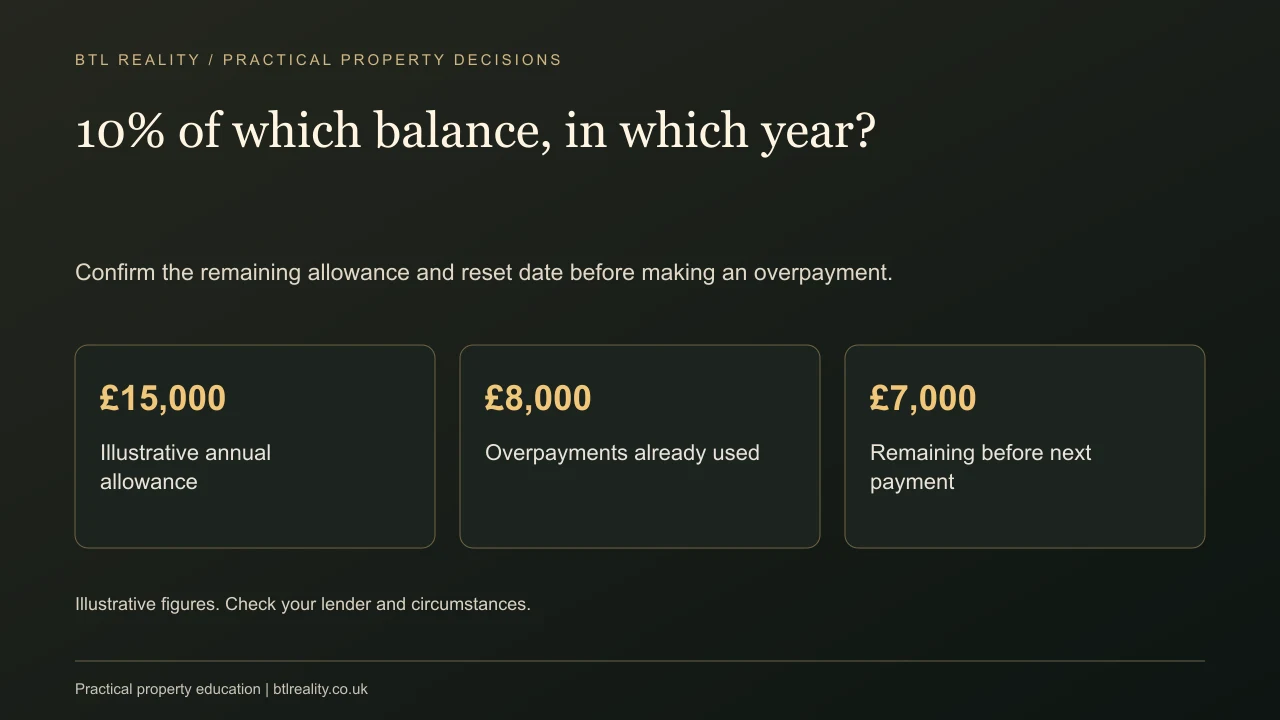
Calculate the remaining allowance in pounds, not from memory. The mortgage terms decide the balance, period and payments that count.
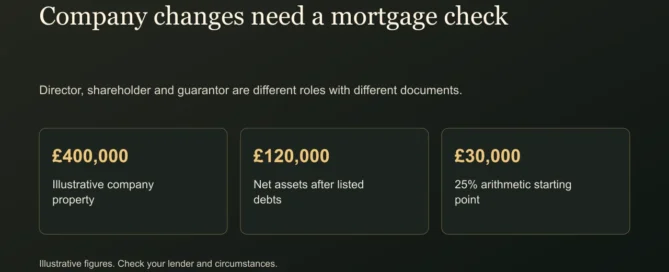
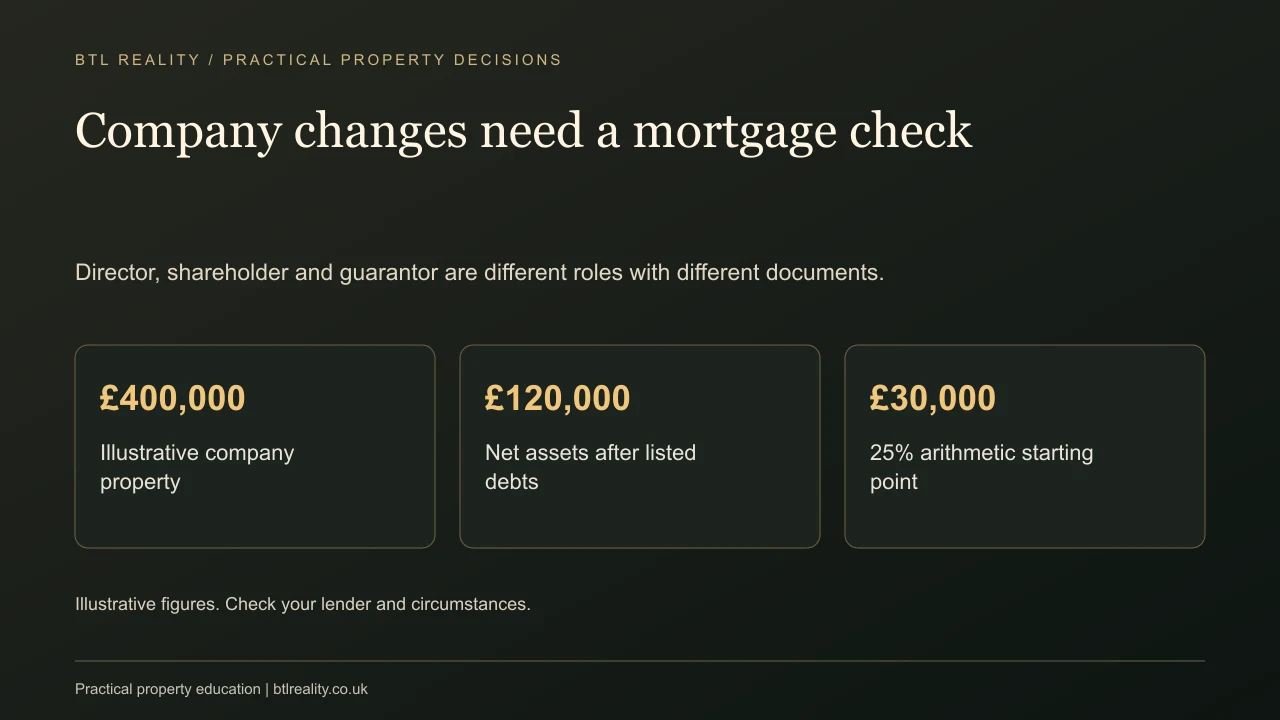
Company filings, lender permission and guarantee release are separate tasks. Plan them together before changing a mortgaged property SPV.
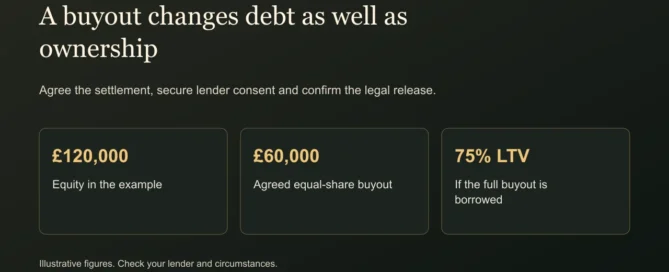
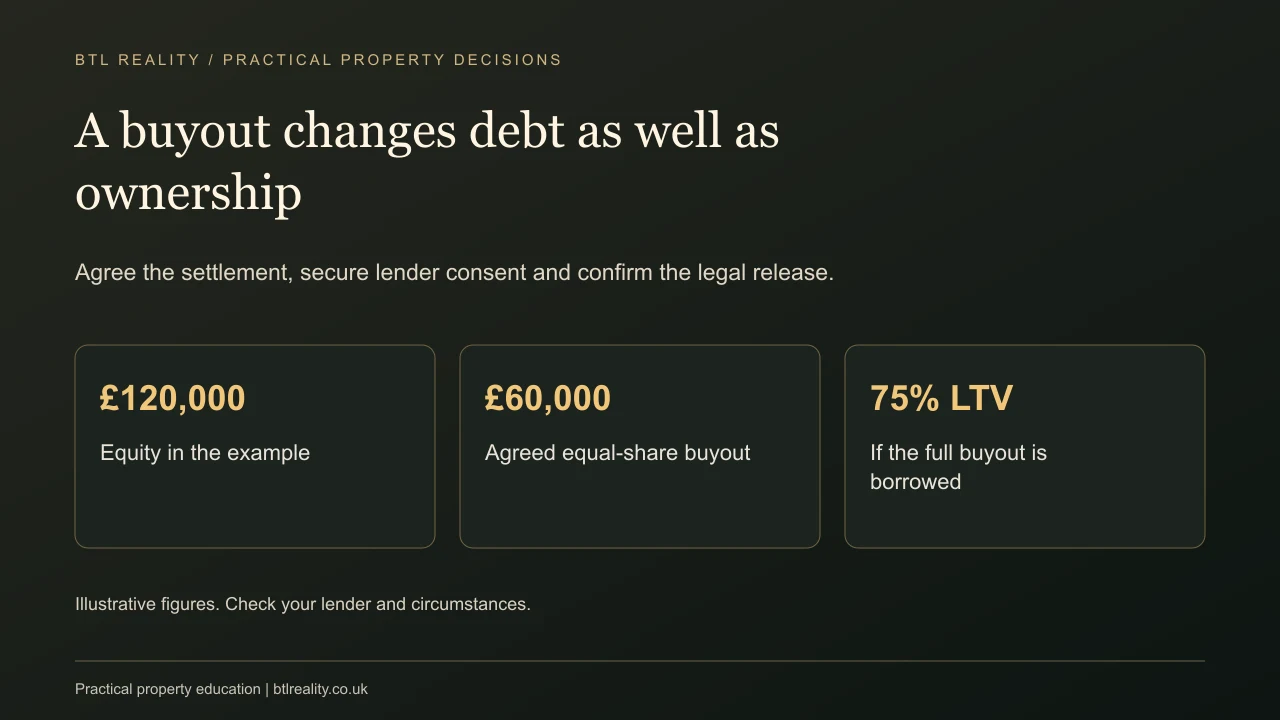
Align the title, mortgage liability and buyout payment. A private agreement alone does not release a joint borrower from the lender’s contract.
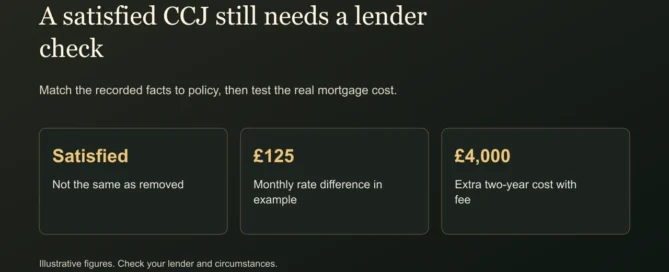
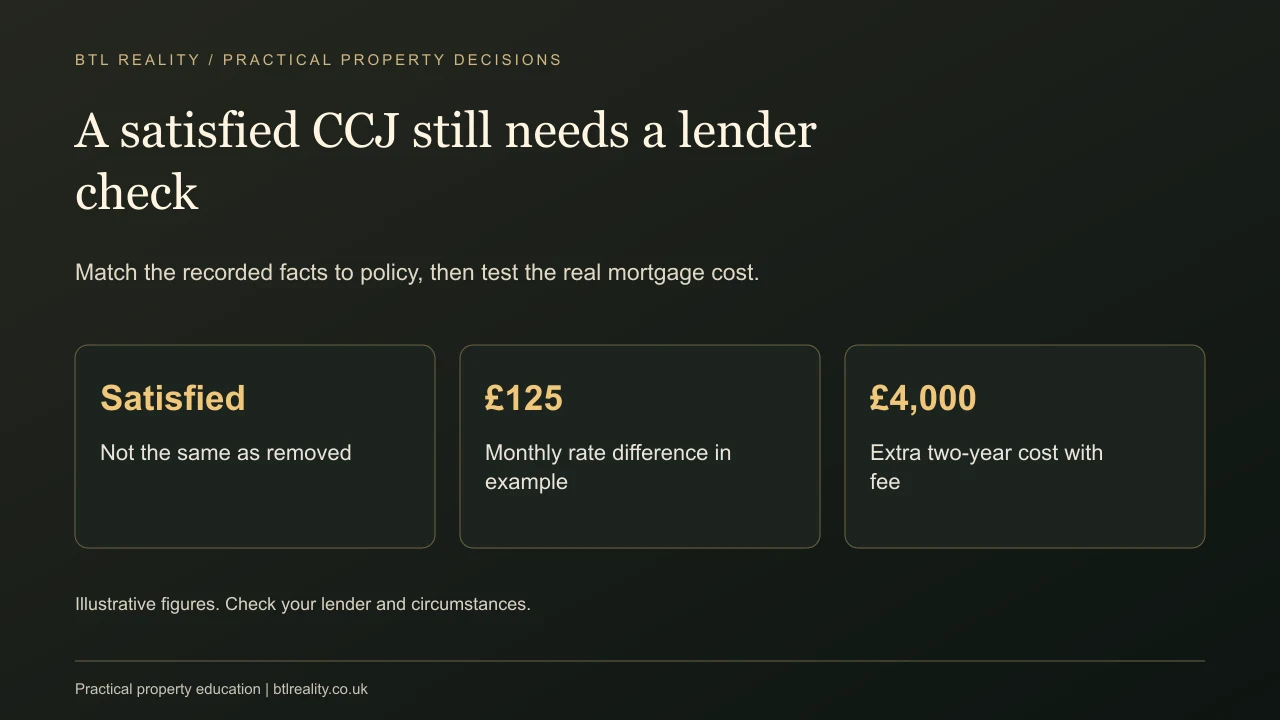
A satisfied judgment is different from a cancelled record. Understand the credit evidence and compare the real cost of the mortgage you can obtain.
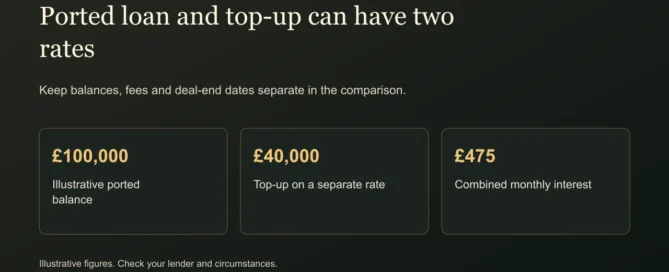
Porting can preserve an existing rate, but extra borrowing and completion conditions change the decision. Compare the whole replacement transaction.
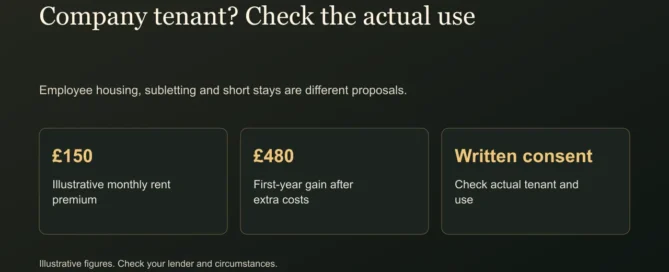
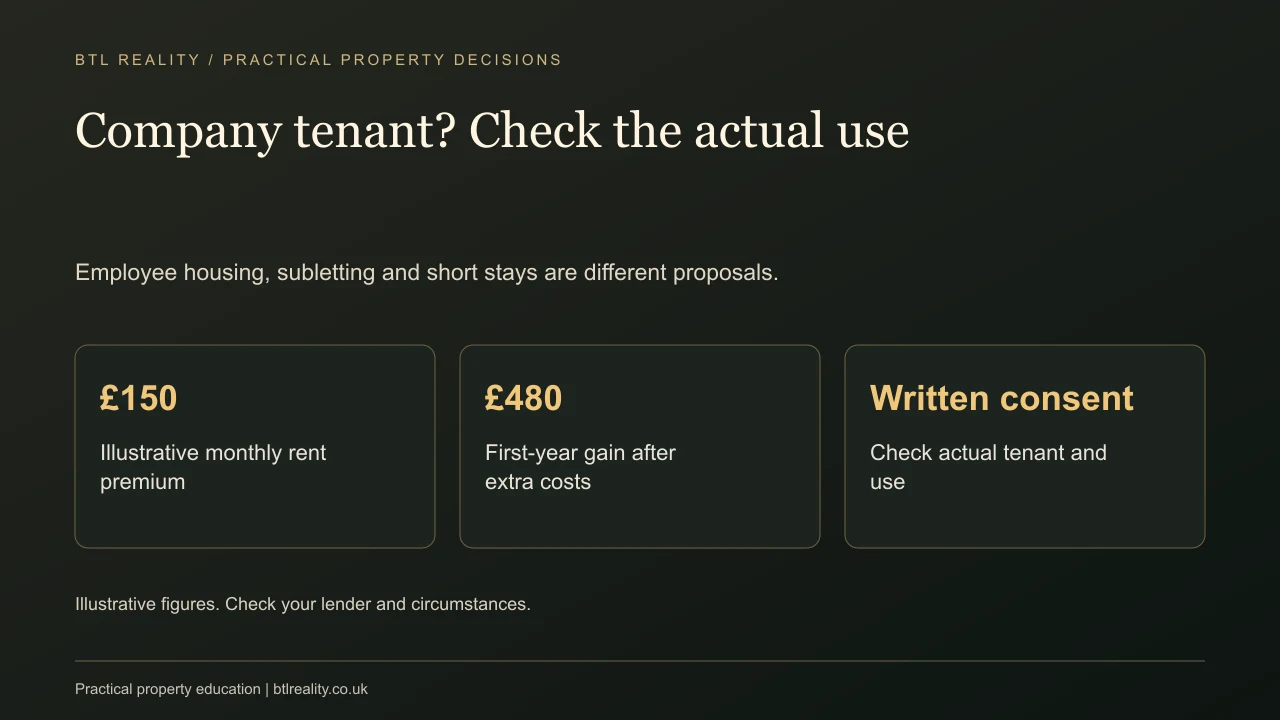
Company tenant, company landlord and rent-to-rent mean different things. Check the full occupation chain and compare the real costs before agreeing.