Inherited a Property: Do You Need a Consumer Buy-to-Let Mortgage?
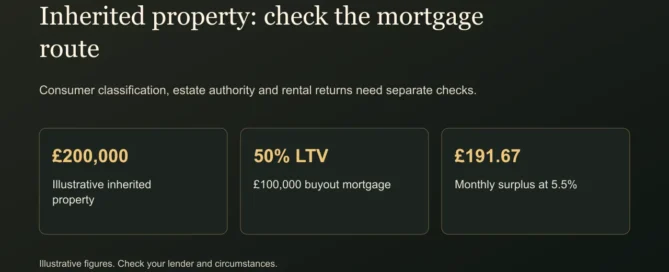
Inheritance can change the mortgage route. Establish the estate position, the correct borrower classification and whether keeping the property makes financial sense.
Inheritance can change the mortgage route. Establish the estate position, the correct borrower classification and whether keeping the property makes financial sense.
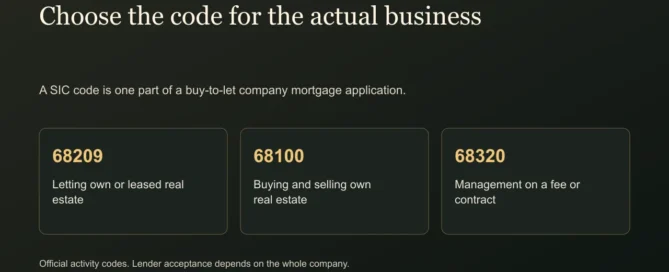
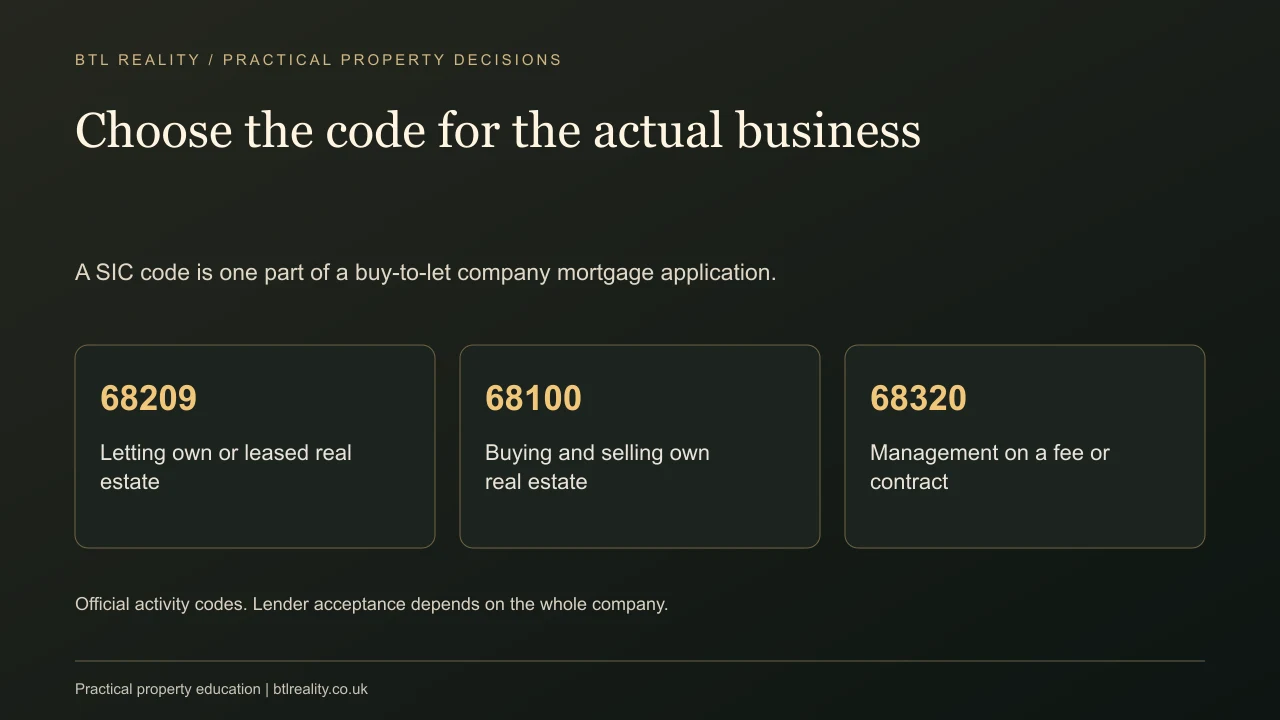
Choose a property-company SIC code that describes the real business, then check the lender’s SPV definition and company records before applying.
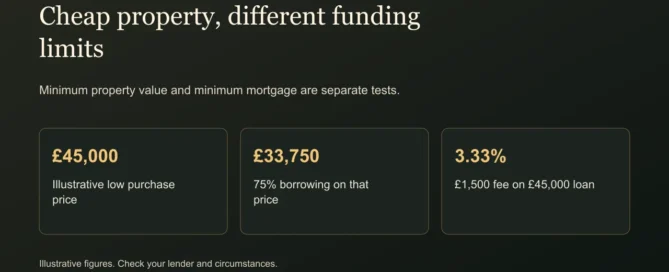
A low asking price does not guarantee easy funding. Compare property-value rules, minimum loans and the true cost of a smaller buy-to-let mortgage.
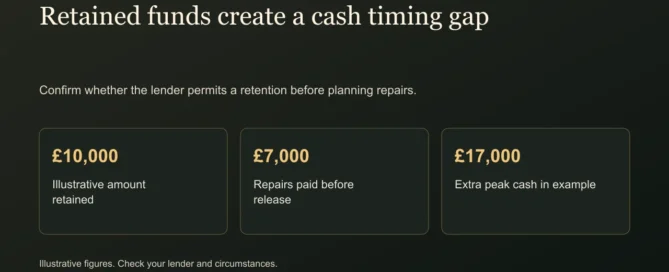
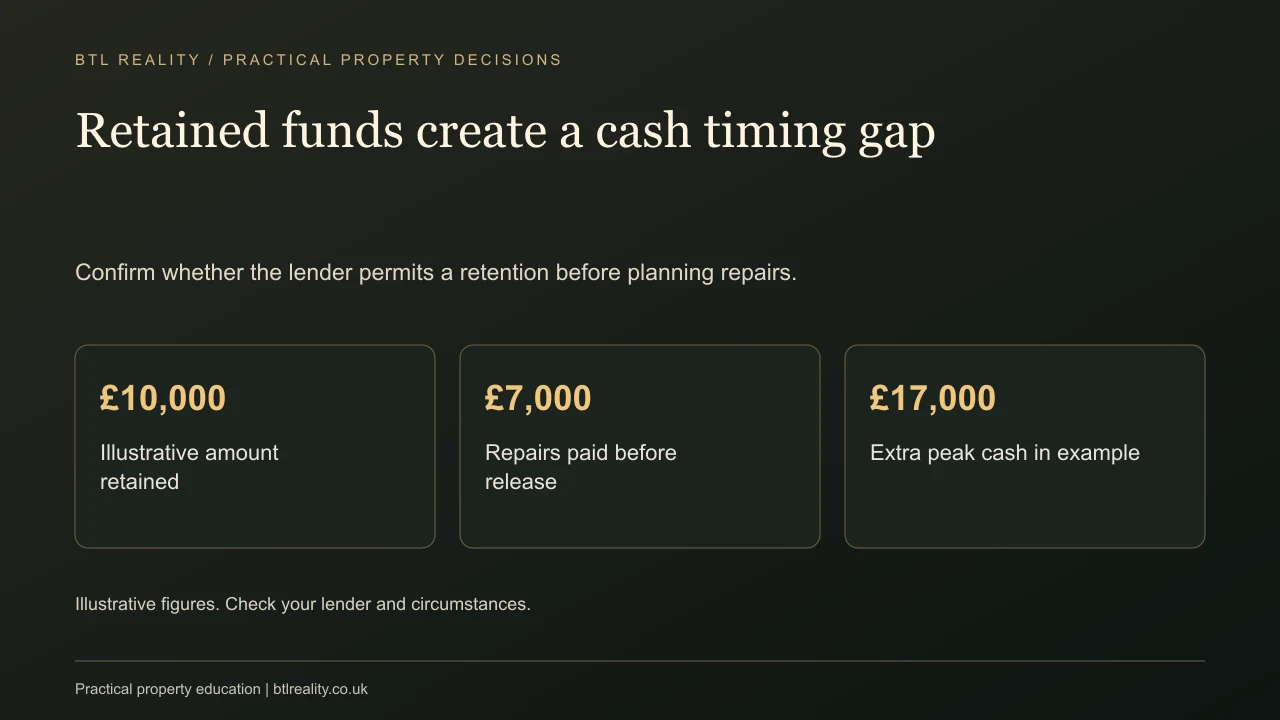
A mortgage retention can require both extra completion money and a separate repair budget. Work through the cash gap before committing.
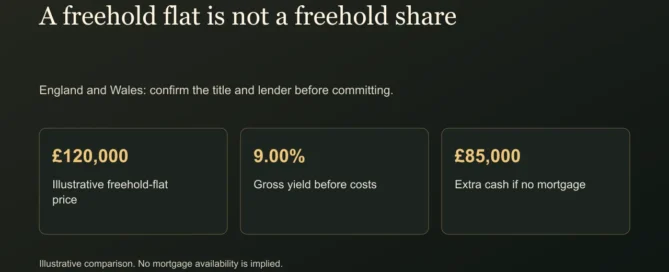
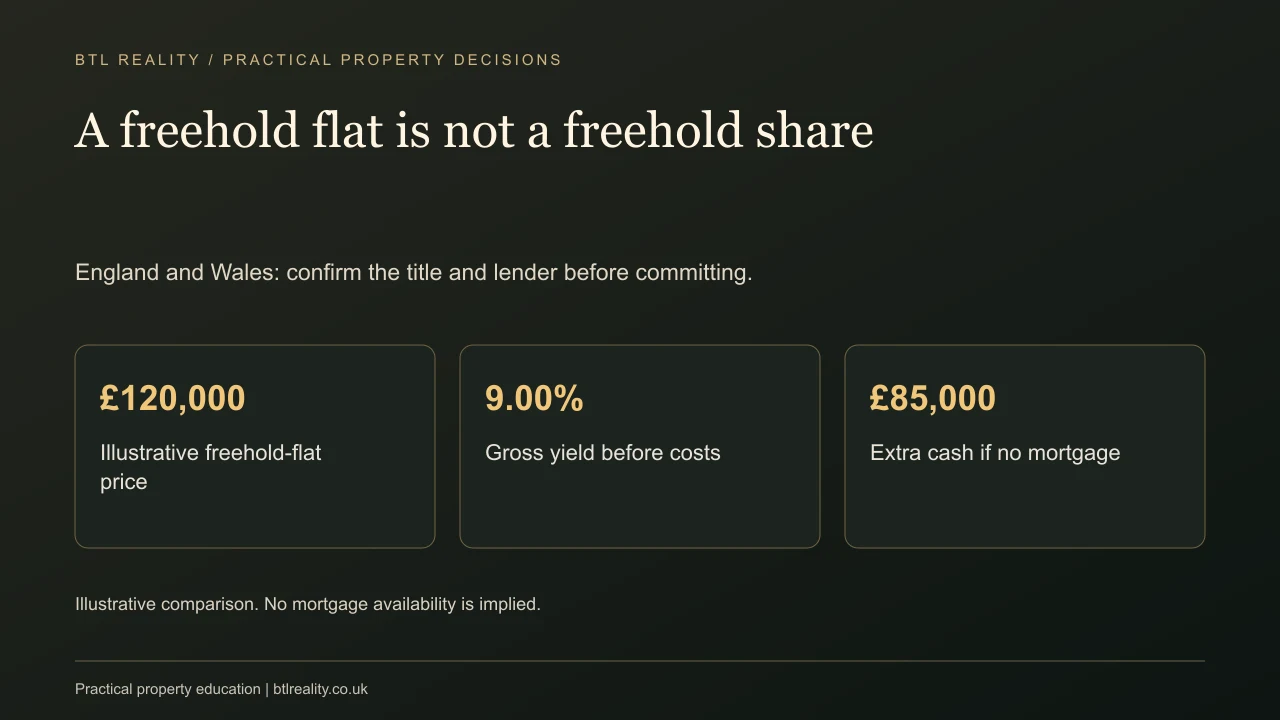
Check whether the flat is truly freehold or leasehold with a freehold share before you rely on a mortgage or a promising rental yield.
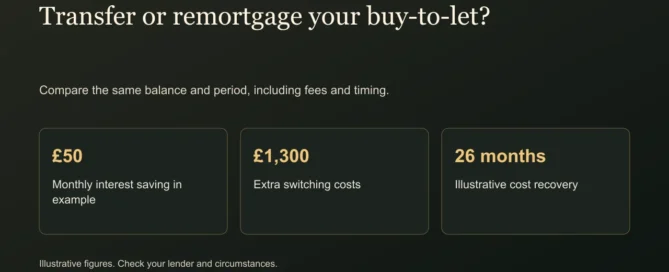
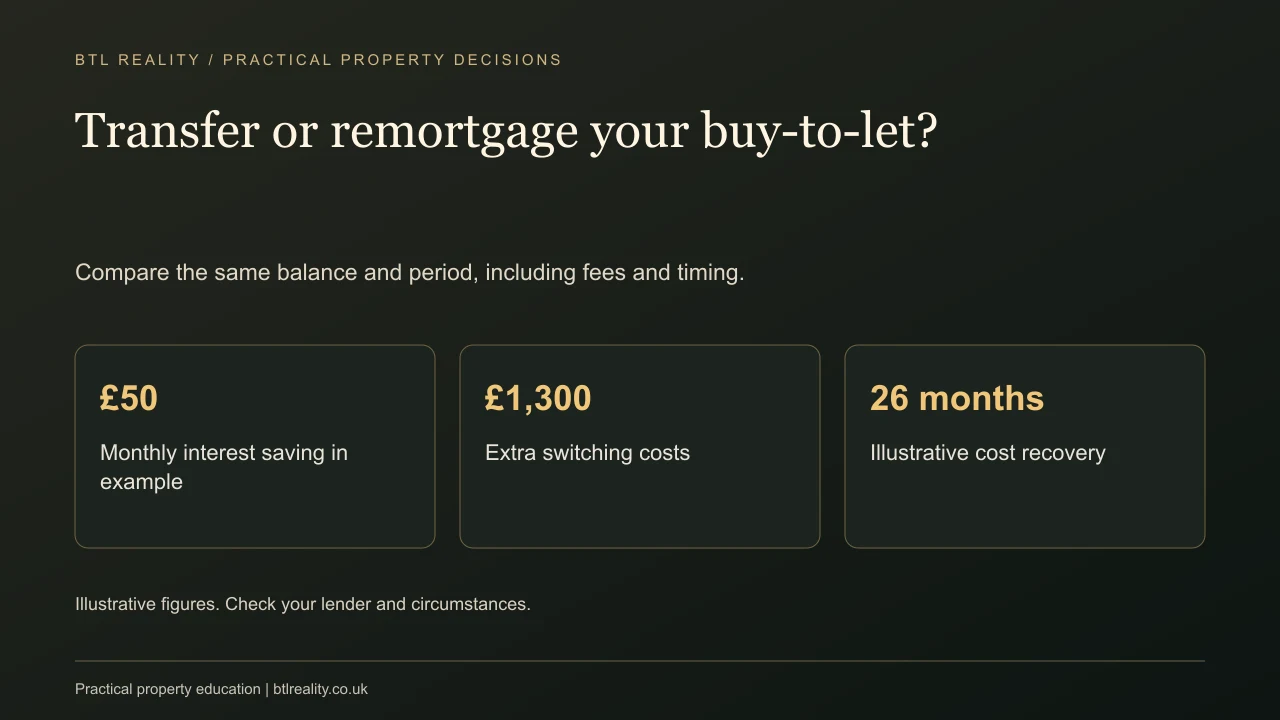
A lower mortgage rate can still cost more. Compare a same-lender switch with a full buy-to-let remortgage over the same period.
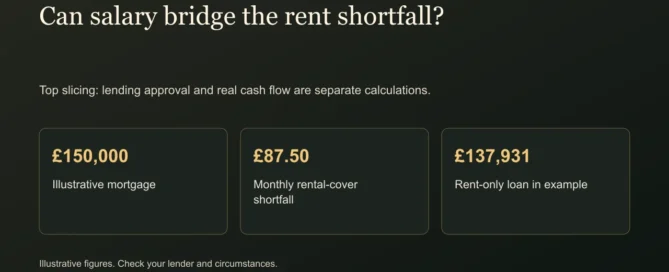
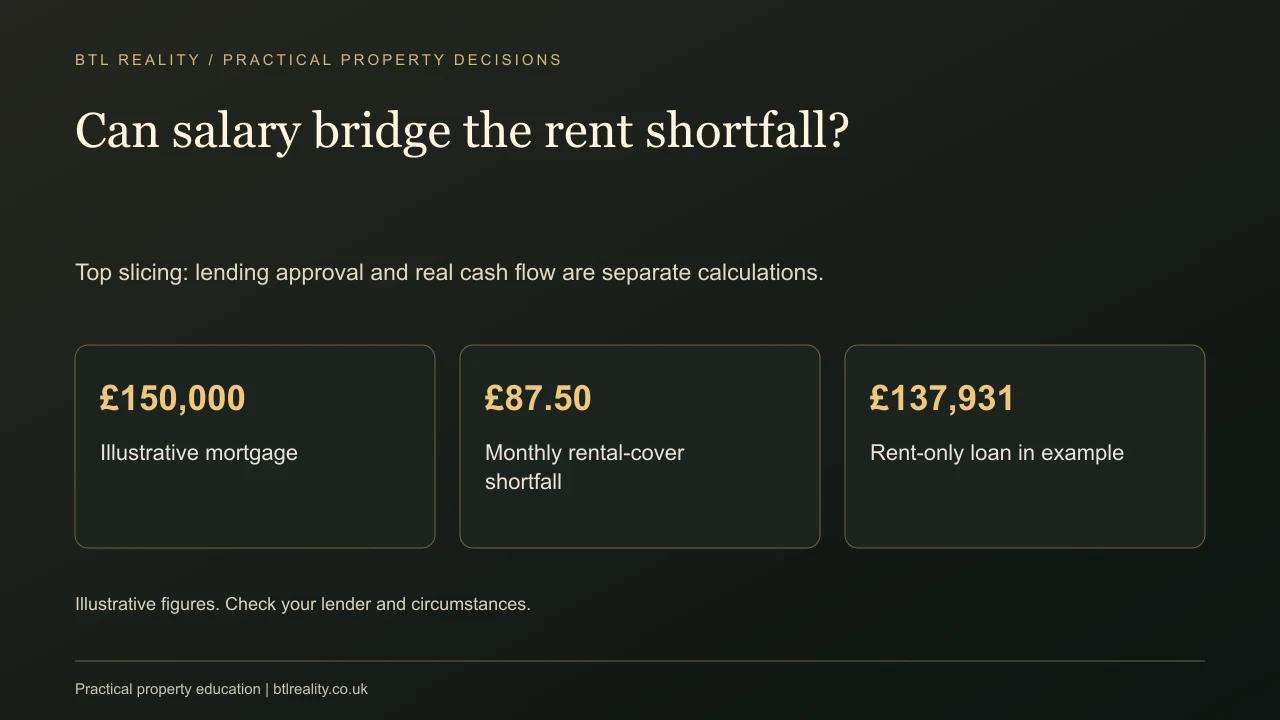
A practical guide to using personal income in a buy-to-let application, with separate rental-cover and real cash-flow calculations.
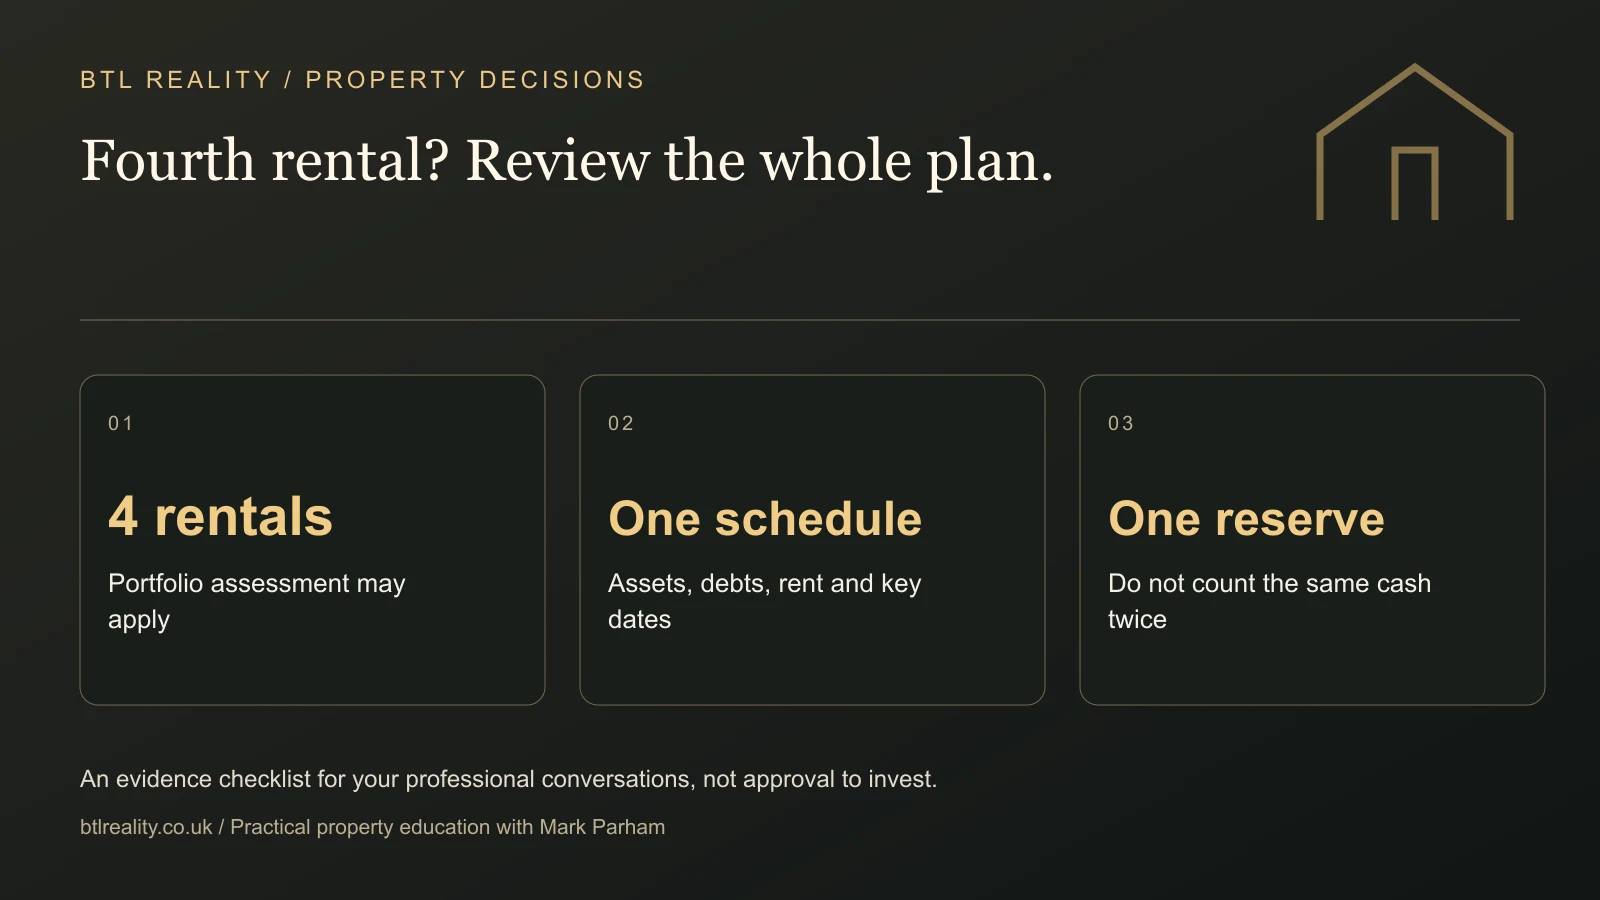
Buying a fourth mortgaged rental? Prepare your property schedule, understand portfolio assessment and test whether the next purchase improves the whole plan.
A reported rise in the bank surcharge raises a practical question for borrowers. I explain the proposal, the possible lender responses and what small rate changes mean in pounds.
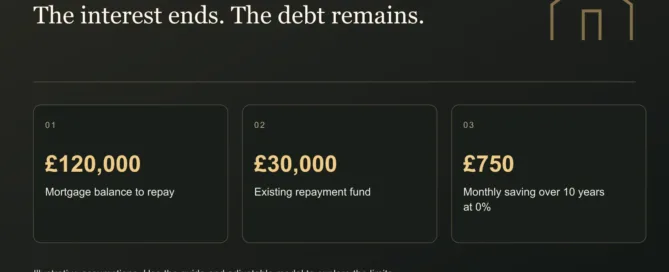
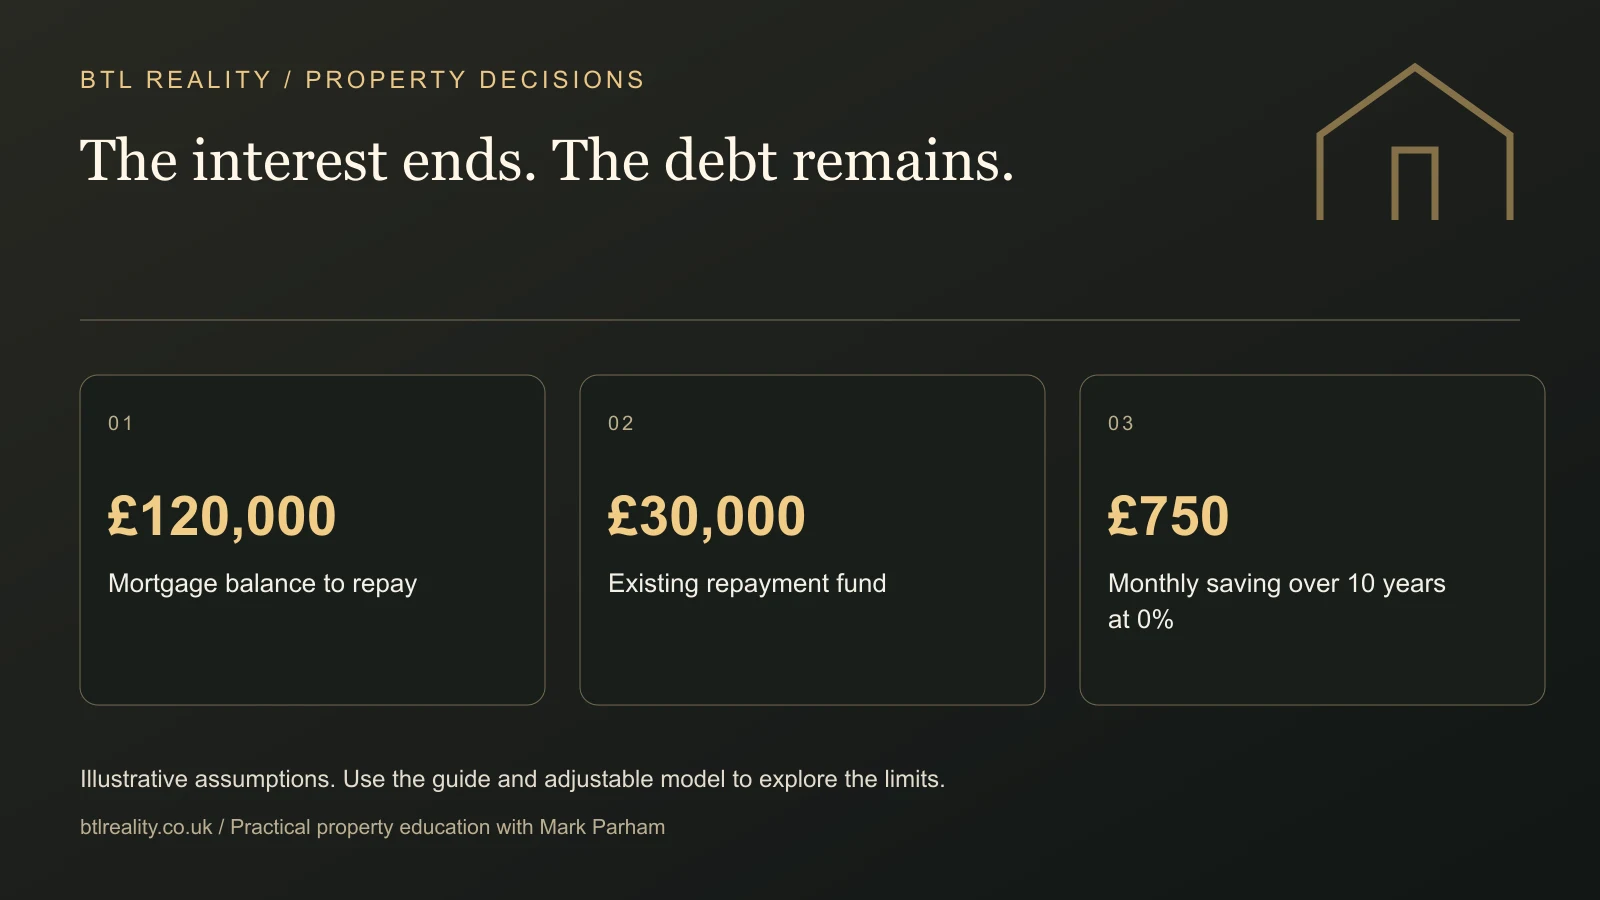
Your interest-only mortgage balance still needs repaying. Model the funding gap, monthly savings and alternatives before the final term ends.