Can You Use a Buy-to-Let Remortgage to Repay Personal Debt?
October 22, 2026
A buy-to-let lender may permit additional borrowing to repay personal debts, depending on its policy and your circumstances. But lender permission, a lower monthly payment and a lower total cost are three different questions.
Moving debt onto a rental mortgage can extend repayment over many years and make the property security for borrowing that was previously unsecured. Before proceeding, compare the complete repayment schedule, fees, effect on rental cash flow and what happens if the underlying spending problem continues.
Check the permitted loan purpose
Tell the broker exactly which debts would be repaid, their balances and their origin. Personal credit cards, business borrowing and property-refurbishment loans are not necessarily treated identically. A vague request for “capital raising” is not enough.
Checked on 19 October 2026, The Mortgage Works’ further-advance page identifies debt consolidation among its permitted purposes, subject to eligibility and the rest of its rules. That is an existing-customer product route, not proof that every buy-to-let lender or company mortgage permits personal debt repayment.
Ask whether the proposed solution is a further advance, replacement mortgage or another arrangement. Each can have different rates, fees and conditions. Do not change the stated use of funds to make an application fit a policy.
A smaller monthly payment can cost more overall
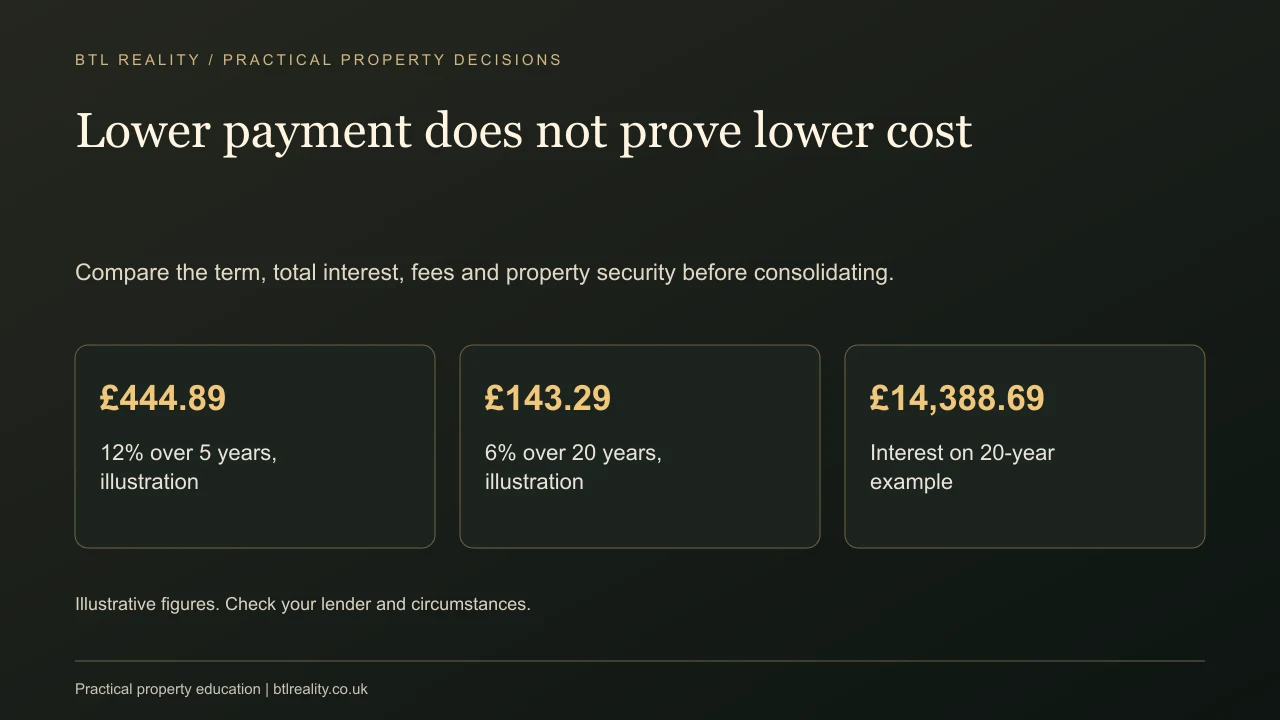
Compare an illustrative £20,000 debt repaid over five years at 12% with the same amount repaid over twenty years at 6%. Assume fixed rates throughout, monthly capital-and-interest payments and no fees for this initial calculation.
| Borrowing option | Monthly payment | Total repaid | Total interest |
|---|---|---|---|
| £20,000 at 12% over 5 years | £444.89 | £26,693.34 | £6,693.34 |
| £20,000 at 6% over 20 years | £143.29 | £34,388.69 | £14,388.69 |
| £20,000 at 6% over 5 years | £386.66 | £23,199.36 | £3,199.36 |
The twenty-year example halves the rate but more than doubles the interest cost compared with the five-year 12% example. The five-year 6% example shows why matching the repayment period matters when judging the benefit of a lower rate.
Use the mortgage stress calculator to explore the actual repayment method and term. Compare total payments and the balance remaining, not just the first direct debit.
Interest-only borrowing leaves the capital outstanding
At 6%, £20,000 of additional interest-only debt costs £100 a month. That is a much smaller payment than either five-year repayment example, but it does not pay down the £20,000 principal.
If the rate remained 6% for twenty years, interest would total £24,000 and the original £20,000 would still need repayment. Adding them gives £44,000 before fees. Actual mortgage rates can change, so this is a fixed-assumption illustration rather than a forecast.
Read the interest-only capital-repayment guide before treating the lower payment as debt reduction. A balance moved to another lender is still a balance owed.
Compare the whole mortgage, not only the extra £20,000
If you replace the entire rental mortgage to raise the money, the existing balance may move onto a different rate as well. A benefit on the additional borrowing can be outweighed by higher interest on a much larger old balance.
Obtain a comparison with the current mortgage retained and a suitable separate further advance, where available, as well as a full remortgage. Include product fees, broker costs, legal work, valuation and any existing-lender early repayment charge.
The mortgage-switching guide explains whole-cost comparisons. A product transfer alone does not necessarily provide extra money, so ensure every option actually funds the intended repayment.
What changes when debt becomes secured?
Unsecured borrowing and a mortgage have different consequences if payments fail. MoneyHelper’s consolidation guidance explains the distinction and encourages comparing costs, fees and alternatives before committing.
For a rental mortgage, the investment property is security. Rent can stop, repairs can arise and a refinancing valuation can fall. The property therefore needs enough resilience to support the enlarged debt rather than relying on uninterrupted rent.
Consider the effect on the wider household too. Depending on the contract and guarantees, exposure may extend beyond your preferred picture of “the tenant pays it”. Obtain the legal explanation of the actual obligations attached to the new borrowing.
Tax relief does not follow from the security alone
Do not assume all interest on borrowing secured against a rental is eligible for property-business relief. HMRC’s interest overview distinguishes business and private expenditure and explains the residential finance-cost restrictions for individuals.
There can also be specific questions about replacement borrowing and withdrawing capital from a business. HMRC’s capital-withdrawal guidance shows why the capital-account position can require analysis. A general label such as personal spending does not replace tracing the actual funds and business history.
Ask the accountant to assess the proposed transaction before including any tax benefit in the comparison. Company borrowing adds separate issues if the money is intended to settle a director’s personal liabilities.
Calculate the rental’s new operating surplus
Update the property budget using the total mortgage payment after the transaction. Deduct management, insurance, compliance, repairs and empty-period provisions. Keep principal repayment distinct from interest for accounting, but include both when checking cash leaving the bank.
Use the deal calculator to review the revised operating position. Then consider a month with no rent and a realistic repair bill. The debt-consolidation payment still needs to be met.
If the property already has a very thin surplus, taking extra debt can make it harder to handle ordinary landlord costs. A lower household credit-card payment does not automatically mean the rental has become stronger.
Make sure the old debts are actually cleared
Get settlement figures and check early repayment costs on the debts being replaced. Confirm how and when the lender or solicitor requires them to be repaid. A statement balance may not be the exact settlement amount on completion.
Keep evidence that each account was paid and reconcile the first statements afterwards. If a credit facility remains open, decide how it will be managed so that the same borrowing does not build up again alongside the larger mortgage.
Review the cause of the debt. A one-off cost with an affordable future budget is different from ongoing spending exceeding income. Consolidating the balance without changing that pattern can leave both the mortgage and fresh consumer debt to service.
Consider alternatives before extending the term
Depending on the situation, options may include repaying from available savings, a shorter-term lower-cost loan, an affordable balance transfer, changing the household budget or agreeing help with creditors. Availability and suitability vary.
If payments are already difficult, seek free debt guidance before adding secured borrowing. MoneyHelper’s linked guidance provides routes to support. A mortgage application is not the only way to address an affordability problem.
If consolidation is still appropriate, compare a repayment period close to the original debt term and test whether maintaining a higher payment is affordable. Check mortgage overpayment restrictions before assuming you can always accelerate repayment later without cost.
Distinguish the product period from the repayment term
A mortgage fixed for five years can still have a twenty-year repayment term. The illustrative table assumes the stated rate remains unchanged throughout purely to isolate the effect of term length. A real mortgage may need several new products before the debt is repaid.
Model a less favourable rate when the product ends and ask how much capital will remain then. Add future switching costs only where you have a reasonable basis, rather than pretending today’s fee is the final cost for twenty years. If an arrangement fee is added to the loan, the fee can also attract interest, increasing the debt that the new repayment schedule must clear.
Keep the decision written down
Record the old debts, settlement amounts, new balance, interest rate, term, fees, monthly payment and total payable under the assumptions. Add the property’s revised surplus, capital-repayment plan and the treatment of any tax relief.
Then state what makes the route suitable: an actual total-cost saving, a necessary affordable restructuring or another clearly understood objective. If the only benefit is a smaller monthly number produced by stretching repayment from five years to twenty, recognise that trade-off explicitly.
Questions about rental mortgage debt consolidation
Can a buy-to-let mortgage repay personal credit cards?
Some lender routes permit debt consolidation under conditions. Disclose the actual purpose, ownership and debts. Do not assume all lenders or company mortgages permit the same use.
Does a lower mortgage rate guarantee a saving?
No. Extending the repayment period, paying fees or repricing a larger existing mortgage can increase total cost. Compare the same term and the whole transaction.
Does an interest-only top-up repay the debt?
No. The monthly payment normally covers interest while the principal remains due. In the illustration, £100 monthly at 6% leaves the original £20,000 balance outstanding.
Is all the new mortgage interest eligible for rental tax relief?
Do not assume so. Purpose, capital-account history, ownership and the applicable finance-cost rules matter. Have the accountant assess the actual transaction before counting any relief.
Should I close the old accounts after consolidation?
Confirm settlement and consider how remaining facilities will be managed with appropriate advice. The essential point is avoiding new balances building alongside the enlarged mortgage.
What if I am already struggling to meet payments?
Seek free debt guidance and contact relevant lenders before committing to more secured borrowing. Assess the household budget and alternatives, rather than treating consolidation as an automatic solution.