Can Let-to-Buy Release the Deposit for Your Next Home?
October 22, 2026
Let-to-buy can allow you to keep your current home as a rental while purchasing a new home to live in. If the existing property has enough equity and the rent supports suitable borrowing, the transaction may also release money towards the new home’s deposit.
It is not simply taking all the equity out and spending it twice. The old mortgage must be repaid, the rental loan has limits, and the onward residential mortgage needs its own affordability assessment. Purchase tax, legal costs and reserves also compete with the deposit for the cash released.
What does let-to-buy actually involve?
The existing home becomes a rental under an appropriate mortgage arrangement. You then purchase another property as your main home, with a residential mortgage if required. The two transactions need to fit together legally and financially.
That differs from temporary consent to let, where an existing residential lender permits letting under its own conditions. The consent-to-let comparison explains that initial choice. Consent alone does not necessarily release purchase money.
Tell both advisers that the deposit for the onward purchase depends on refinancing the old home. A residential application presented as if the money were already unencumbered savings can give an incomplete picture.
There are two affordability decisions
The proposed rental lender needs to assess the existing property and its sustainable rent, alongside its applicant and loan criteria. The onward residential lender needs to assess the new home and your ability to meet the residential borrowing under its rules.
A rent-cover calculation supporting the old property does not establish the maximum residential mortgage. Equally, a strong salary does not guarantee the rental loan will release the amount you want. Each lender must accept the connected arrangement.
Ask how the residential lender treats the retained property, proposed rent and new mortgage. Do not assume every lender ignores the old debt once you intend to let the property. Provide the documents it requests to establish the expected post-completion position.
Start with cash released, not total equity
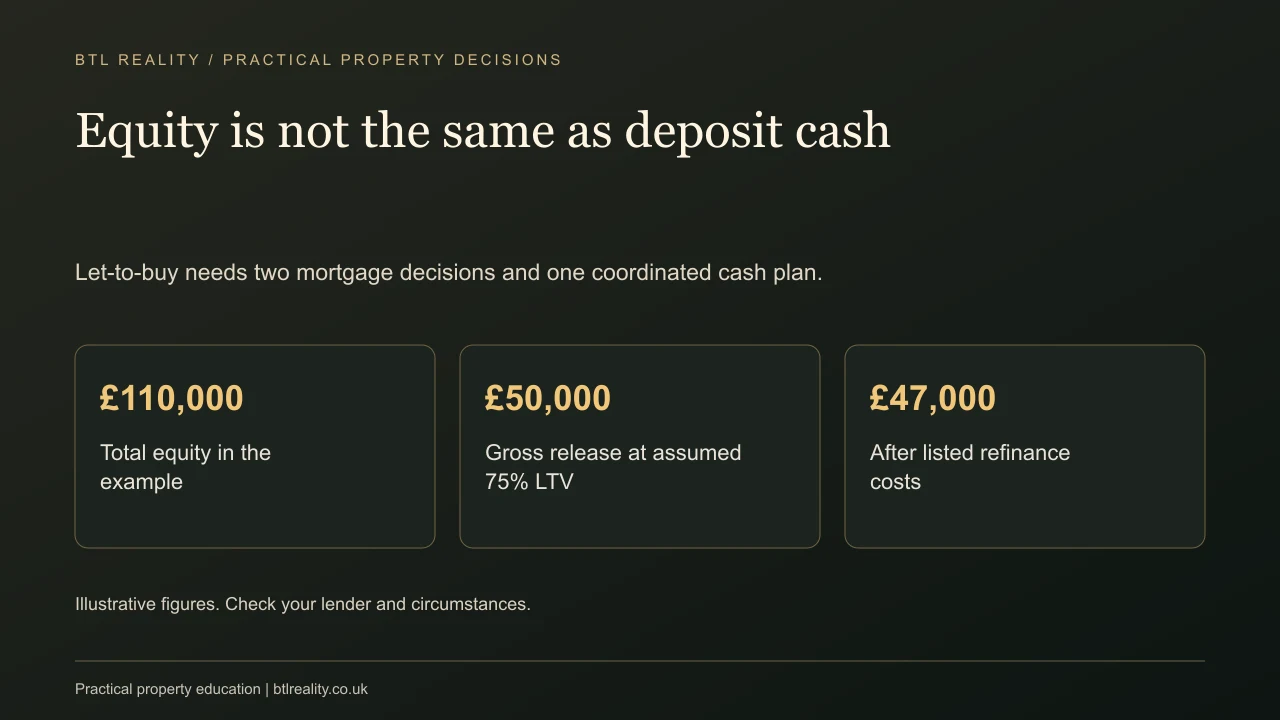
Suppose your current home is worth £240,000 and the existing mortgage redemption amount is £130,000. Total equity before costs is £110,000. But a hypothetical 75% let-to-buy mortgage would be £180,000, releasing £50,000 after repaying the old lender.
| Item | Amount |
|---|---|
| Existing home value | £240,000 |
| Assumed maximum borrowing at 75% | £180,000 |
| Existing mortgage repaid | Minus £130,000 |
| Gross cash released | £50,000 |
| Illustrative refinance costs | Minus £3,000 |
| Cash before onward purchase costs and reserves | £47,000 |
The £110,000 equity is not a £110,000 available deposit. In this example, £60,000 stays in the rental as equity and £3,000 is used in refinancing costs. The actual cash release also depends on the rent and lender valuation.
Use the buy-to-let deal calculator for the retained rental and record the onward home’s purchase budget separately. Keep each transaction’s cash requirements visible.
Rental coverage may reduce the release
If a lender’s rent assessment supports only a £165,000 loan, the gross release falls to £35,000 before costs. The same property value and existing mortgage therefore produce £15,000 less cash than the 75% LTV assumption.
Ask for the maximum supported by both LTV and rental coverage and use the lower relevant amount. Obtain realistic achieved-rent evidence, taking account of the property’s condition and local demand. An optimistic rental listing is not a confirmed valuation.
The rent-cover guide explains the basic calculation. Do not increase the new home’s offer price before the rental borrowing is sufficiently established.
Check the lender’s linked-completion requirements
Checked on 19 October 2026, BM Solutions’ let-to-buy criteria require a linked onward residential purchase and simultaneous completion. They also set out the information needed about that purchase before an offer is issued.
The Mortgage Works’ general criteria direct applicants converting their existing residence to its let-to-buy range and describe its linked onward-purchase proposition. These are lender-specific processes, not a universal rule that all transactions follow the same timetable.
Ask the broker and solicitor to agree the sequence. If the new-home purchase is delayed or falls through, establish what happens to the proposed refinancing and any reserved products. An intended use of released money does not guarantee the lender will advance it independently.
Budget purchase tax on the new home
Keeping the previous home can affect transaction tax when you buy another. For England and Northern Ireland, HMRC’s higher-rate SDLT guidance says the new main home can attract higher rates where the relevant conditions are met and the previous main home is retained.
Scotland and Wales use different transaction taxes. Have the solicitor calculate the actual bill using all owners’ circumstances. Do not assume describing the new purchase as a home rather than an investment removes the additional-property rules.
If a later sale of the old home might support a refund under the applicable rules, confirm the conditions and deadlines. The purchase still needs to be funded when it completes; a possible later refund is not cash available for the initial deposit.
Keep a rental reserve after the move
The old home now needs a landlord operating budget. Include management, insurance, maintenance, compliance, empty periods and any work needed before a tenant moves in. Some costs differ from those you paid while living there.
Do not allocate every pound released to the onward deposit and tax. A rental that needs £4,000 of initial work and several months of carrying costs can put pressure on the household immediately after an expensive house move.
Use the mortgage stress calculator for the proposed rental loan. Test no rent during the initial works as well as an occupied month. Your household needs to support the gap until the letting is genuinely ready.
Compare keeping the property with selling it
Let-to-buy is one option, not an automatic solution when a sale feels inconvenient. Compare the net rental return, extra purchase tax, finance costs, management work and capital tied up with the cash a sale could release.
In the example, retaining £60,000 equity in the rental has an alternative use. It could otherwise reduce the residential mortgage or provide flexibility. Include that opportunity cost rather than treating the old property as free because you already own it.
The return-on-equity guide helps assess the income produced by that retained capital. Future capital growth remains uncertain and should be tested as a scenario rather than assumed.
Existing mortgage charges can affect the choice
Get a current redemption statement and confirm any early repayment charge. A £50,000 gross release can shrink once charges, product fees and legal costs are included. Ask which fees can be added to the new loan and whether that reduces purchase cash or rental affordability.
Compare the proposed timing with the existing deal end. Waiting may reduce charges, but it may also affect the house move. A sensible comparison includes the practical reason for moving and the actual costs of each timetable.
Keep the rental and residential mortgage terms separate. Their expiry dates, repayment methods and charges may differ. Record both so the household does not face a surprise refinance on two properties simultaneously.
Prepare the property for its new use
Mortgage approval is not the whole landlord setup. Check insurance, legal letting duties, any licensing and restrictions in the title or lease. Tell the agent and solicitor the intended date you will move out and when the property can be occupied.
Read the first buy-to-let guide for the wider sequence. Already knowing the house is helpful, but it can also make it easy to overlook repair or tenant-demand issues a buyer would normally investigate.
The plan is ready when the borrowing, purchase cash, tax, reserves and completion sequence all agree. A large equity figure alone does not establish that the next home is funded.
Allow for a lower valuation or a short period with both properties costing money and no tenant in place. A house move already uses time and cash. A realistic slower case helps establish whether retaining the former home is affordable without depending on every date and estimate going perfectly.
Questions about let-to-buy deposits
Can I release equity from my old home for a new-home deposit?
Potentially, through a suitable let-to-buy arrangement. The available amount depends on value, rent, existing debt, fees and lender criteria, alongside approval of the onward residential purchase.
Is all the equity available to withdraw?
No. The rental lender normally requires equity to remain and may restrict borrowing through rental coverage. Deduct the old mortgage and transaction costs from the accepted new advance to calculate released cash.
Does the rental mortgage approval guarantee the residential mortgage?
No. The onward lender makes a separate decision under its own affordability and property rules. Both need to accept the connected arrangement and its deposit source.
Do both purchases have to complete together?
Some lender arrangements expressly require simultaneous completion. Confirm the actual sequence with the broker and solicitor before relying on released funds for a binding purchase commitment.
Will the new home avoid additional-property tax because I live there?
Not necessarily. Retaining the former home can trigger higher purchase-tax rates where the rules apply. Have the solicitor assess the relevant UK nation and all purchasers’ circumstances.
Should I use all the released cash for the new deposit?
Allow for purchase tax, fees, moving costs and the retained rental’s work and reserves first. The maximum available deposit is not automatically the amount it is sensible to commit.