Can a New Property Company Get a Mortgage Without Accounts?
October 22, 2026
A new property SPV may be able to obtain a buy-to-let mortgage before it has filed a set of accounts. Some lenders expressly accept newly established companies. That does not mean the application proceeds without financial evidence.
The lender still needs to understand the people behind the company, its ownership, the deposit, the property and the rent. The useful preparation is a complete new-company application pack, rather than trying to create a trading history that does not exist.
Why a new SPV is different from an established trading business
A newly formed property company may be purchasing its first asset. It cannot provide several years of rental accounts if it has not yet owned a property. Some buy-to-let lenders assess that starting position through their company, director and property criteria.
That is different from a trading business borrowing against an income stream it has operated for years. Do not assume a lender’s requirements for a self-employed person’s income are identical to the requirements for the SPV buying the property.
Your personal income evidence can still be relevant. If a director is self-employed, the lender may need their accounts or tax records under its applicant policy even though it accepts the property company without company accounts.
What do published criteria say?
Checked on 19 October 2026, Cambridge’s limited-company buy-to-let criteria identify newly established companies as acceptable, subject to the rest of the policy. That is not an exemption from director, deposit or property checks.
The Mortgage Works’ company criteria also describe consideration of SPVs from the start of their existence, while asking applicants to allow time for new-company information to be available in its systems.
Ask the broker to identify a current product that fits the actual structure. A company’s age may be acceptable while the shareholders, intended activity, residency or funding source are not. “New companies accepted” is one line in a larger policy.
Set the legal borrower up accurately
Choose the company structure with appropriate advice before making an offer dependent on it. Confirm the exact legal name, registration number, directors, shareholders and persons with significant control. Give the same details to the broker and solicitor.
Check that the intended business activity is recorded accurately and meets the lender’s SPV requirements. The SIC-code guide explains the classification question. A suitable code does not by itself prove that the whole structure qualifies.
Do not incorporate a complex ownership chain purely because it sounds sophisticated. A parent company, overseas shareholder or unusual share rights can change the lender shortlist. Explain the intended long-term ownership before settling on the setup.
What evidence replaces a long company history?
| Area | What the application needs to establish |
|---|---|
| Company identity | The correct legal borrower and its ownership |
| Applicants | Identity, residence, credit and relevant income evidence |
| Deposit | Who owns the money and how it was accumulated |
| Property | Acceptable security, value, condition and intended letting |
| Rent | A sustainable figure supporting the required calculation |
| Guarantees | The required people understand and sign the legal obligations |
Ask for a case-specific checklist. Different lenders accept different personal and company deposit sources. Do not move funds first and assume any later description will be acceptable.
If the lender requests a company statement, provide the genuine new-account history available and ask how it handles the short period. Never substitute a personal account statement and label it as the company’s trading record.
A first-purchase cash budget
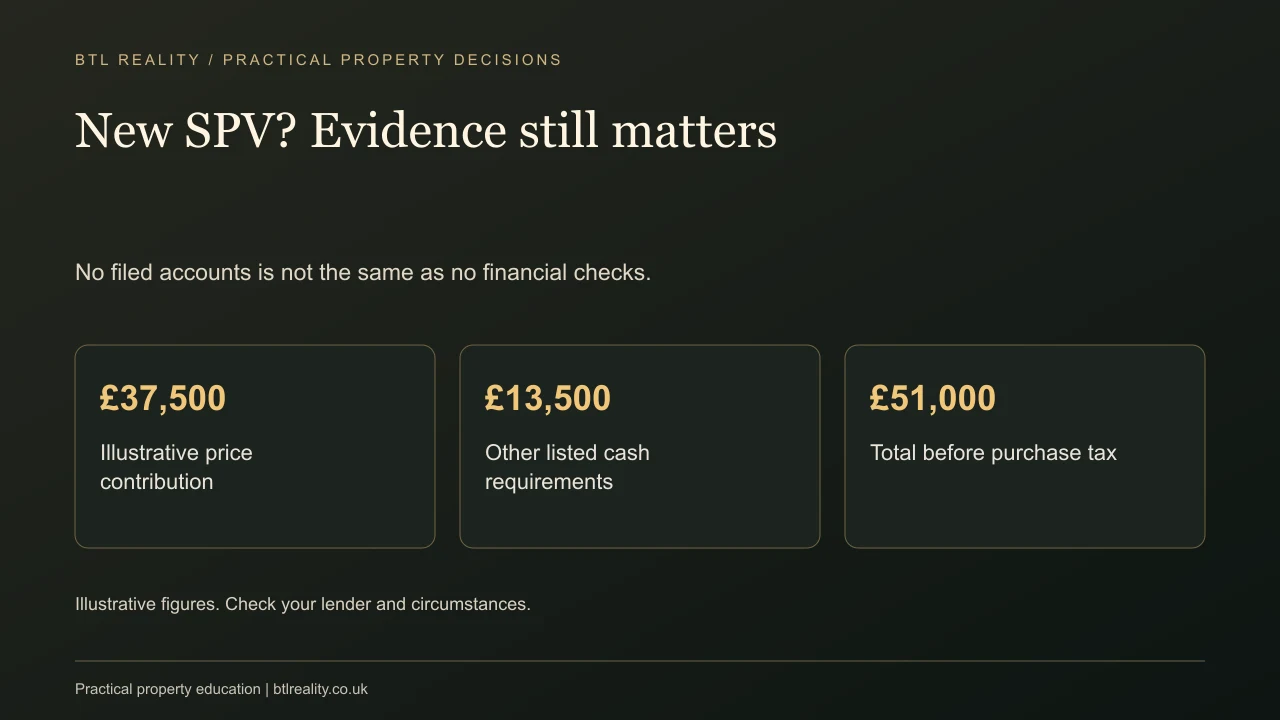
Assume a £150,000 property with a £112,500 mortgage and £37,500 price contribution. Add illustrative £2,000 finance costs, £1,500 legal costs, £4,000 initial work and £6,000 operating reserve. Those figures total £51,000 before any purchase tax and additional case-specific expenses.
The company therefore needs more than the £37,500 headline deposit. The extra £13,500 has to come from a documented source too. If the director provides the money, record whether it is a loan, share capital or another properly advised arrangement.
Use the buy-to-let deal calculator beside the actual quotation. Company mortgage fees, legal advice and lender requirements can differ from a purchase in your own name, so do not simply copy a personal-buying budget.
Personal guarantees deserve time
The lender may require directors or other applicants to guarantee the company’s borrowing. Ask who must sign, the scope of the guarantee and what independent legal advice is required. Do not leave this until the day the purchase is supposed to complete.
A limited company does not automatically mean the lender can look only to the property and company assets. The personal-guarantee guide explains why the actual legal documents matter.
Confirm the parties and advice arrangements early, especially where people live in different places. A lender accepting the SPV’s age does not shorten the time needed for everyone to receive advice and complete valid documentation.
The rent still has to support the proposed loan
For an illustrative £112,500 interest-only mortgage at 6%, annual interest is £6,750. A hypothetical 125% rental-cover test would require £8,437.50 annual rent, or £703.13 monthly after rounding.
That is a simplified example, not a current lender calculator. The selected product’s stress rate, rental multiple and treatment of fees control the actual assessment. A company structure does not make every advertised rent sufficient.
Also prepare an operating budget after management, insurance, maintenance, compliance and empty periods. An application can pass rent cover while leaving little useful income after the property’s real costs. Company accounts will later record the business; they do not create a profit that the property fails to earn.
Keep setup money and trading money distinct
Open and use the company banking arrangements required for the transaction and lender payments. Keep the records showing each contribution and expense. Paying a professional bill personally may need to be recorded correctly in the accounts rather than disappearing from the company budget.
Read the director’s-loan guide where the director is funding the initial purchase. If another business is advancing the money, the intercompany-loan guide covers that different creditor arrangement.
Agree who maintains the records from day one. A new company with no historical accounts still needs an organised record of what happened after incorporation, including the money committed before the first rent is collected.
Do not let incorporation timing drive a rushed purchase
Allow time for the company records, bank account, identity checks, mortgage application and legal work. Different organisations may need updated information to become visible before they can proceed. Ask the broker for the actual sequencing requirements.
For an auction or short completion deadline, confirm funding readiness before committing. A company can be incorporated quickly while the mortgage remains nowhere near an unconditional offer.
Set the purchase timetable from the slowest necessary process, not the quickest administrative step. Keep the seller informed through the appropriate agent or solicitor rather than promising completion because the company registration has arrived.
A new company does not erase the directors’ property history
If the applicants already own rentals personally or through other companies, disclose them. The mortgage lender may assess their wider portfolio and commitments even though this particular SPV is buying its first property. Do not describe the whole case as a first-time landlord simply because the company was incorporated last week.
Prepare a current property schedule with ownership, values, mortgages, payments, rents and deal-end dates where requested. That lets the adviser identify portfolio requirements early. A complete schedule is also useful for checking whether the new purchase adds too much exposure to the same location or refinancing period.
Plan the first year’s administration
Ask the accountant about accounts, tax, confirmation statements and record-keeping obligations for the company. Establish which professional services the quotation includes and which tasks remain with the directors.
The absence of accounts at mortgage application is a temporary starting condition, not a permanent exemption from company administration. Build those recurring costs into the investment budget so the first year does not look artificially profitable.
Then review the company after the first letting. Compare actual rent, expenses and cash with the assumptions used for the mortgage and purchase. That creates useful evidence for future borrowing while showing whether the first property is performing as planned.
Questions about new-company mortgages
Can a new SPV get a buy-to-let mortgage without filed accounts?
Some lenders accept newly established companies under specific criteria. They still assess the applicants, ownership, deposit, property and rent. Ask for a suitable current product and document checklist.
Does no company-accounts requirement mean no income evidence?
No. Directors or other applicants may still need personal income evidence under the lender’s rules. A new SPV and a self-employed applicant have different evidence questions.
Can I use my personal bank account for everything?
Check the lender’s company banking requirements and keep the company’s records separate. Personal contributions and expenses need accurate accounting. Do not present personal transactions as an invented company history.
Does the correct SIC code guarantee approval?
No. The code describes activity. The entire company structure, applicants, funds and property must still meet the selected lender’s criteria.
How much cash does the company need beyond the deposit?
Budget for applicable tax, finance and legal costs, initial work and reserves. In the illustration, those listed non-tax items increase £37,500 of price contribution to £51,000 total cash.
Will the company avoid personal guarantees because it is new?
Not automatically. Guarantee requirements depend on the lender and structure. Identify who must sign and arrange the required legal advice before setting a completion date.