Changing Directors or Shareholders in a Mortgaged Property Company
October 20, 2026
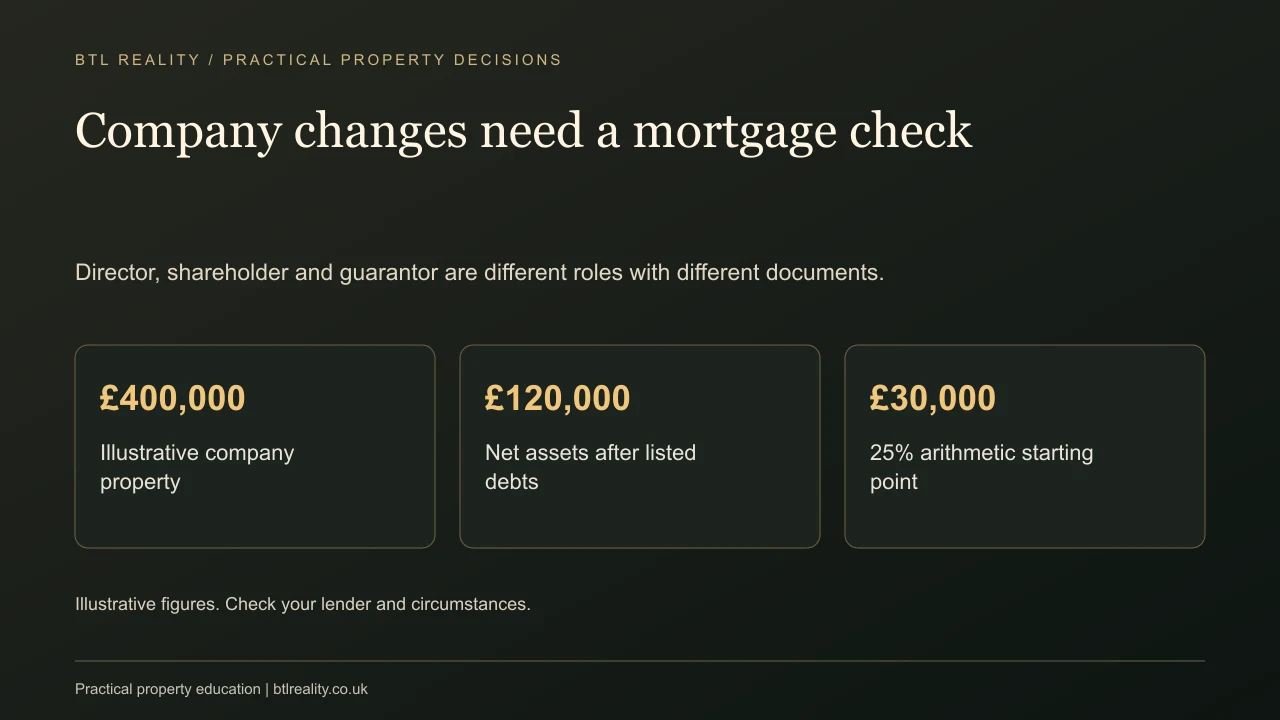
If your property company has a mortgage, changing a director or shareholder can require the lender’s permission before the company records are changed. Filing a form at Companies House does not establish that the mortgage contract permits the new structure.
The property may remain owned by the same company, but the lender originally assessed particular people, ownership and guarantees. A shareholder exit, new investor or director resignation can change that picture. Plan the company and mortgage steps together rather than treating the finance as an afterthought.
Director, shareholder and guarantor are different roles
A director manages the company under the relevant duties and powers. A shareholder owns shares with rights defined by the company’s documents. A guarantor has obligations under a separate guarantee. One person can hold all three roles, but changing one role does not automatically change the others.
For example, resigning as a director does not by itself prove that the lender has released a personal guarantee. Selling shares does not automatically update the mortgage applicants or permit a new director to give instructions on the account.
Map the current roles and proposed roles in writing. Include directors, shareholders, persons with significant control and anyone who has signed mortgage or guarantee documents. The broker and solicitor need the actual structure, not just the percentage being sold.
What can a mortgage policy require?
Checked on 19 October 2026, The Mortgage Works’ company-change criteria require advance notification and an application for consent, subject to risk assessment. They also identify changes it will not accept and warn about changes made without approval.
That is one lender’s policy. Read your own mortgage terms and ask about the specific proposal. An increase in one existing shareholder’s holding may be handled differently from adding an overseas corporate parent or replacing every director.
Where the company has several mortgages, each lender may need to consider the change. Approval from one does not bind another. Keep a lender-by-lender checklist so a portfolio-wide company change is not completed with only one account reviewed.
Companies House has a separate reporting process
Companies House guidance on company changes explains the reporting requirements for directors, shares and other company details. Those public-record duties exist separately from lender consent and the company’s internal decision-making.
Your solicitor or company adviser should confirm the documents, approvals and filings needed for the actual transaction. The company’s articles, any shareholders’ agreement and the proposed share rights can affect what must happen.
Do not use the public register as the only completion checklist. A register can accurately record a change that breached an existing finance condition. Equally, receiving lender consent does not complete the share-transfer documents or required public filings.
A share value is not simply a slice of the house price
Consider an illustrative company with a £400,000 rental property and £10,000 cash. It owes £250,000 on the mortgage and £40,000 under properly recorded director loans. Before other liabilities, costs and tax, the simplified net assets are £120,000.
| Item | Amount |
|---|---|
| Property value | £400,000 |
| Cash | £10,000 |
| Mortgage debt | Minus £250,000 |
| Director-loan balances | Minus £40,000 |
| Simplified net assets | £120,000 |
| 25% arithmetic share | £30,000 |
One quarter of the £400,000 property price is £100,000, but that ignores the company’s debts. Even the £30,000 arithmetic result is not a professional valuation: share rights, tax, control, contingent liabilities and negotiations can change the actual price.
Use the deal calculator to review the property’s operating budget, but obtain proper company-account and share-valuation advice for the ownership transaction. They answer different questions.
Director loans need their own settlement
A shareholder can also be a creditor because they lent money to the company. Agree separately what happens to that loan when shares are sold or the person resigns. The share price does not necessarily repay or transfer the loan automatically.
If the company must repay a director loan from its cash, test the impact on reserves. In the example, £10,000 cash would not cover a £40,000 immediate repayment. The plan might depend on fresh funds, agreed terms or suitable refinancing, each requiring its own assessment.
The director’s-loan guide explains why money owed to a director should be recorded distinctly from shares. Give the accountant, solicitor and lender the same proposed treatment.
Who will guarantee the debt after the change?
Ask the lender which people must sign guarantees under the new structure and whether existing guarantees will be released, replaced or remain effective. Each person should obtain the legal advice required for the documents they are being asked to sign.
Do not assume a 25% shareholder guarantees only 25% of the mortgage. The scope comes from the actual deed and lender requirements, not just the shareholding. Equally, do not assume a departing person has no exposure because the new owner promises to pay.
Read the personal-guarantee guide before agreeing the financial settlement. A clean exit needs written clarity about both ownership and continuing liability.
New people can change the underwriting
A lender may need identity, residence, credit, income or experience information for new directors or relevant shareholders. Ask what is required before setting a completion deadline. If a person lives overseas or another company is joining the structure, flag that early.
The lender can also assess whether its applicant numbers, shareholding requirements and permitted company structure still fit. Adding a relative with a small stake can therefore involve more than changing an internal spreadsheet.
If the current lender cannot consent, ask the broker whether a suitable refinance exists and at what cost. Do not make the ownership transaction dependent on an assumed new mortgage without checking property value, rent cover, fees and any early repayment charge.
Budget the transaction and its timing
Obtain quotations for legal work, accountant advice, any valuation, lender processing and guarantees. Add possible finance costs if the mortgage must be replaced. A small share transfer can create professional work disproportionate to the percentage changing hands.
Ask who bears the costs if the lender declines consent or the transaction does not complete. Keep conditional agreements clear so one party does not assume that paying a deposit guarantees lender approval.
Consider the property’s cash flow during the process. Repairs and mortgage payments continue while corporate documents are negotiated. Avoid using the operating reserve to fund an owner’s exit unless the remaining company can still meet its obligations comfortably.
A share transaction is different from selling the property
Changing the company’s shareholders is not the same legal transaction as transferring the property out of the company. The company can remain the registered property owner while its own ownership changes. That distinction affects the documents, liabilities and tax advice required.
Give advisers the actual proposed transaction instead of asking loosely how to “transfer the property to a partner”. A share sale, new share issue, director appointment and asset sale can have different consequences. Choosing the wrong description at the start can lead to unsuitable advice, quotations or lender applications.
Update access and management after completion
Agree who can operate the company bank account, speak to lenders, instruct the letting agent and authorise repairs. Change access at the appropriate point, with proper authority. Do not remove the only functioning signatory before the replacement arrangements are ready.
Notify the insurer, accountant and property manager where required, keeping the legal company identity and ownership information accurate. A director’s departure may also change who holds tenancy, safety and financial records.
Keep a central completion file with lender consent, legal documents, guarantee confirmations, register updates and the final account settlement. This is the evidence future advisers need when the company refinances or another owner exits.
Reconcile the final director-loan balances and any money paid at completion against the company accounts. Keep the payment trail and signed settlement together. A later remortgage can involve questions about the same funds, so recording the transaction clearly now saves the remaining directors from reconstructing it years later.
Questions about property-company changes
Can I change a director without telling the mortgage lender?
Check the mortgage contract first. A lender may require advance consent and underwriting. Companies House acceptance of a filing is not evidence that the mortgage terms permit the change.
Does resigning as a director release my personal guarantee?
Not automatically. The guarantee’s wording and the lender’s formal release determine the position. Obtain written confirmation rather than relying on a resignation letter or the remaining owners’ promise.
Can I give shares to a family member?
There may be a lawful route, but company rules, tax, lender consent and underwriting need checking. A gift is still a change in the ownership structure the lender originally assessed.
Is my share worth the same percentage of the property value?
Not necessarily. The company also has debts, cash, other liabilities and share rights. Use current accounts and valuation advice instead of multiplying the house price by your share percentage.
What happens to my director loan when I sell shares?
Agree it separately. It may remain owed, be repaid or be dealt with under a documented arrangement. The share sale does not automatically determine what happens to a distinct creditor balance.
Does one lender’s consent cover the whole portfolio?
No. If different lenders have mortgages to the company, check each contract and process. Record every required consent and guarantee outcome before treating the company change as fully approved.