Can I Transfer My Buy-to-Let Into a Limited Company?
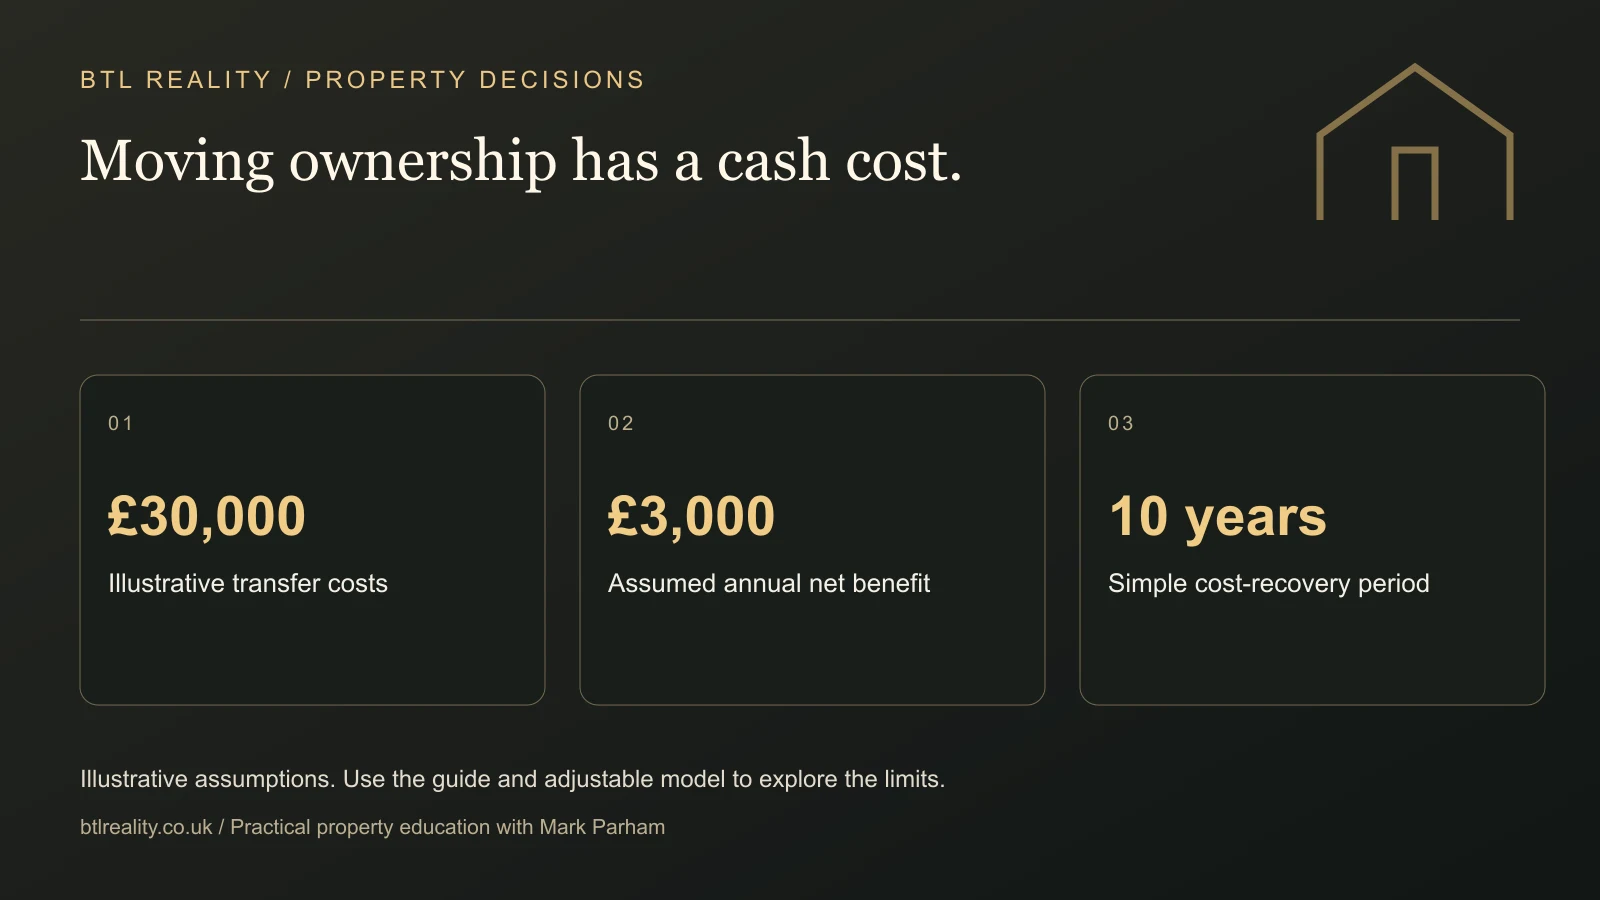
Moving a rental into a limited company can trigger tax and refinancing costs. Compare the upfront bill with the expected annual benefit before deciding.
Moving a rental into a limited company can trigger tax and refinancing costs. Compare the upfront bill with the expected annual benefit before deciding.
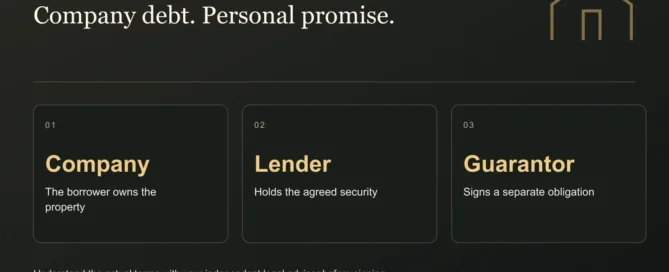
A company mortgage can create a personal commitment. Understand the questions to ask about guarantee limits, joint liability, legal advice and release.
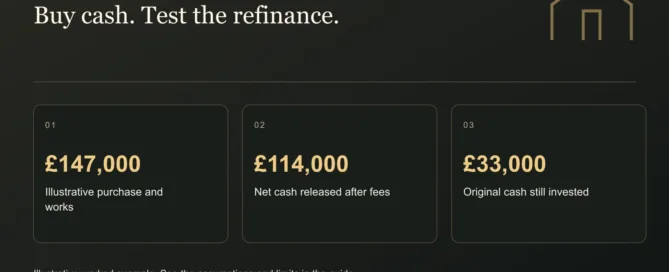
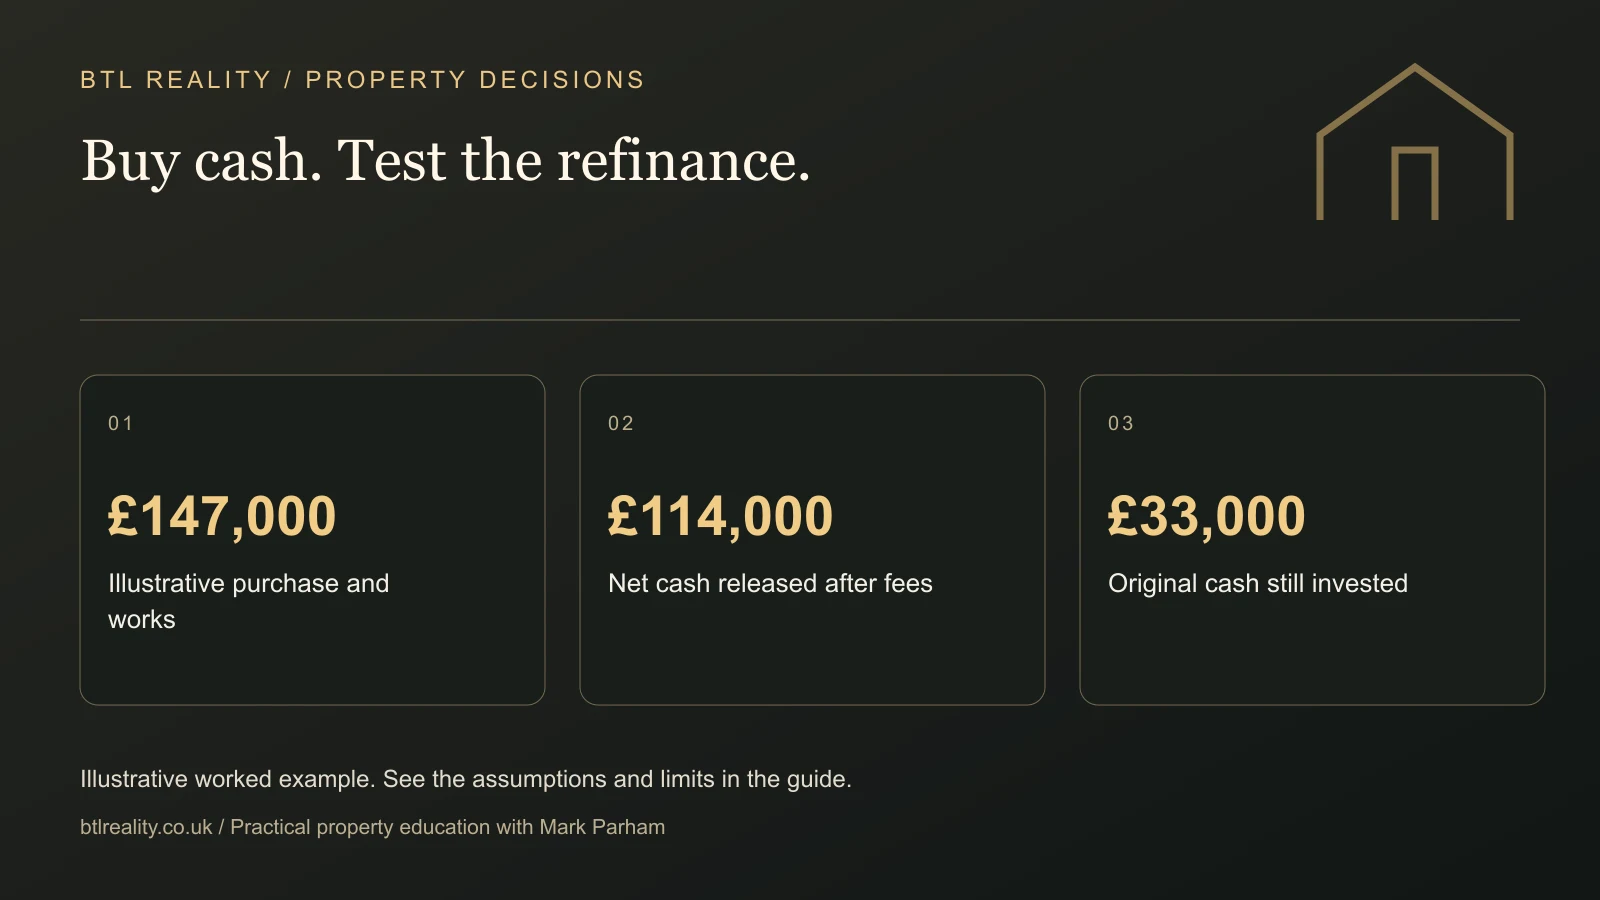
Buying with cash then refinancing? Model the loan, cash left invested and a lower valuation, and check what happens if the mortgage is delayed.
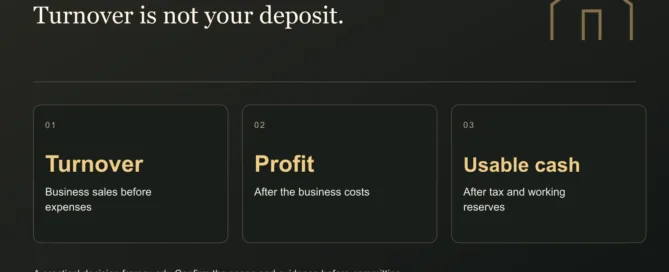
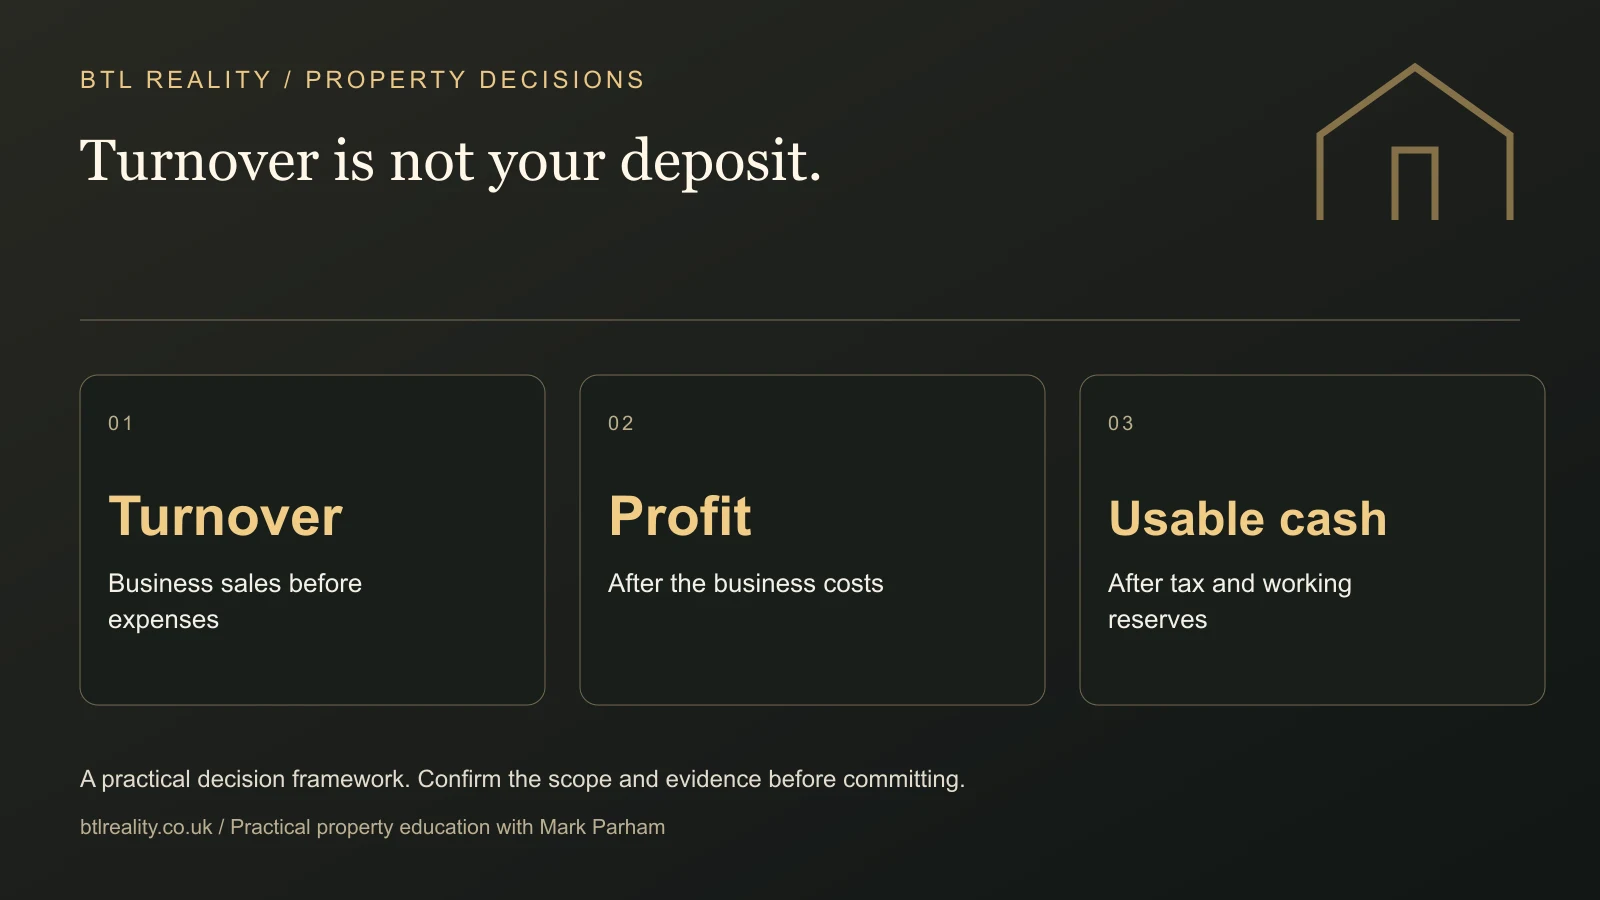
Understand the evidence self-employed buy-to-let applicants may need. Separate turnover, profit and usable cash, then prepare a stronger broker discussion.
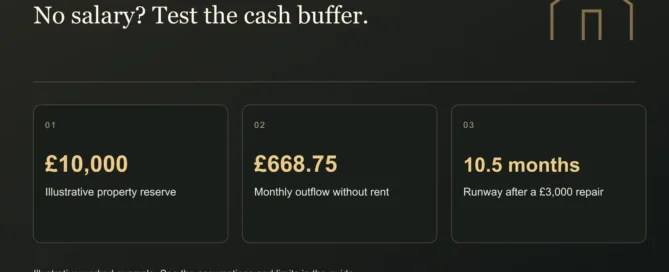
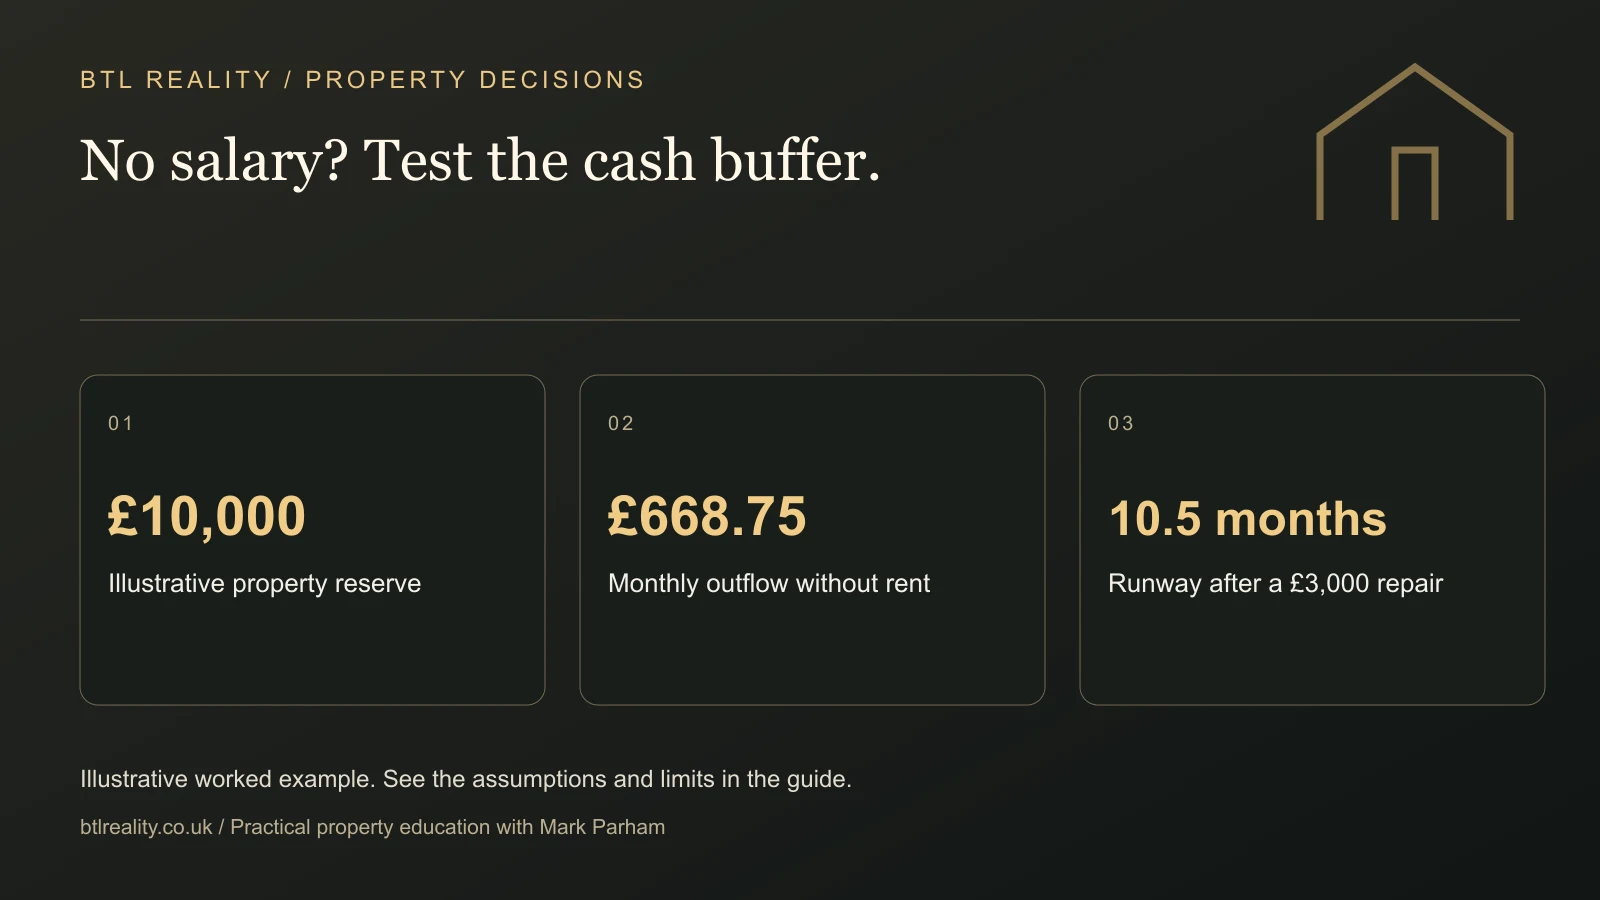
No salary does not always rule out a buy-to-let mortgage. Learn what lenders may check and test your cash reserves with our interactive planner.
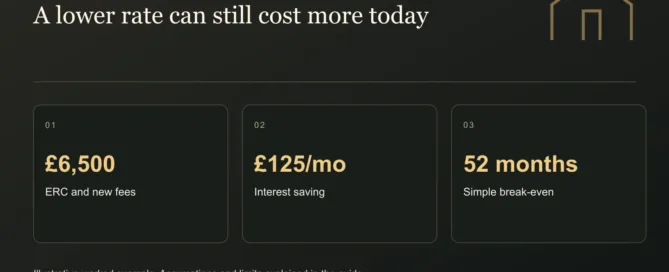
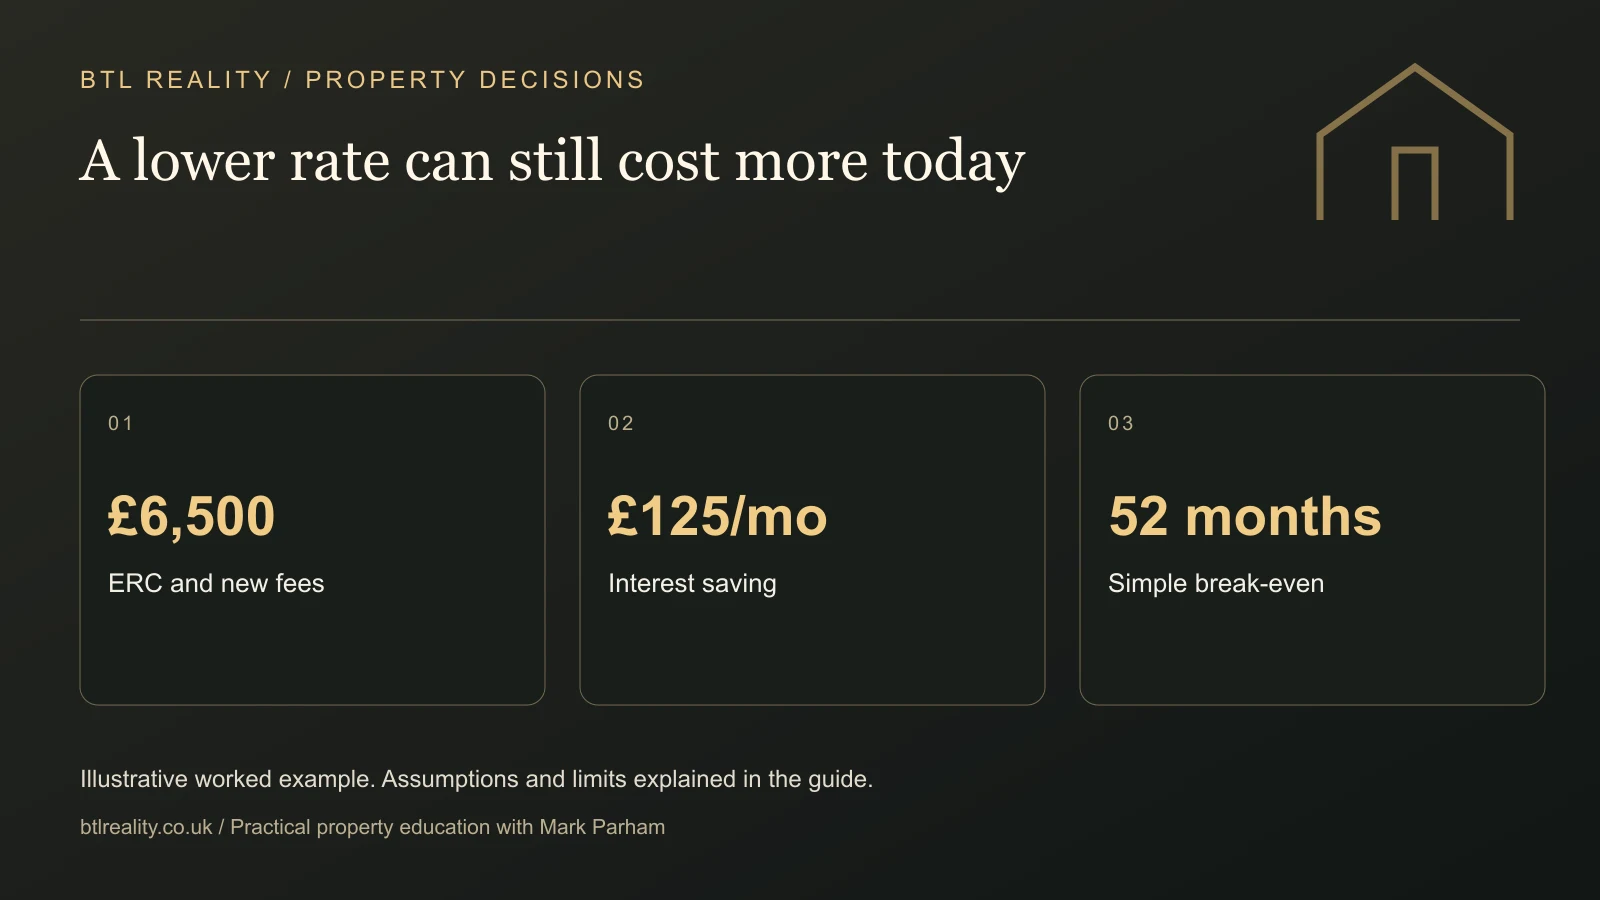
Compare an early refinance with waiting. Calculate charges, fees, interest savings and usable equity release before breaking a buy-to-let mortgage deal.
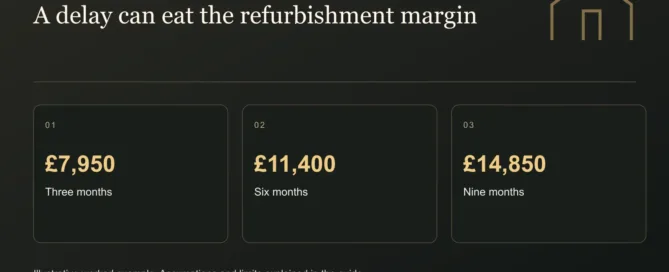
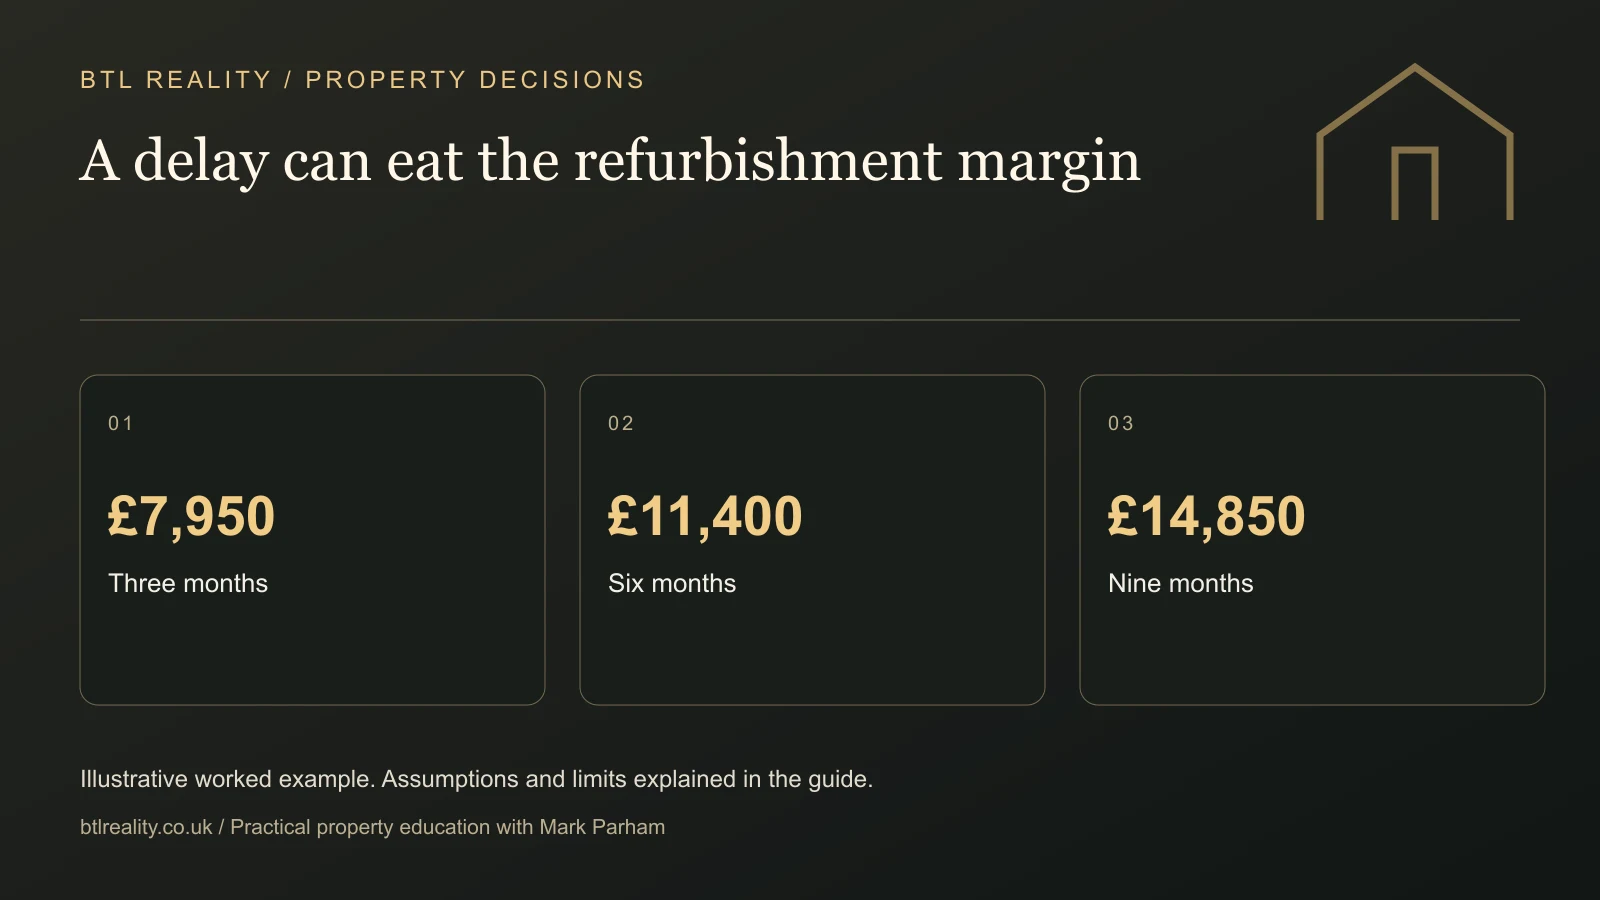
Compare bridging costs over three, six and nine months. Check usable advances, delays and refinance exits before funding a buy-to-let refurbishment.
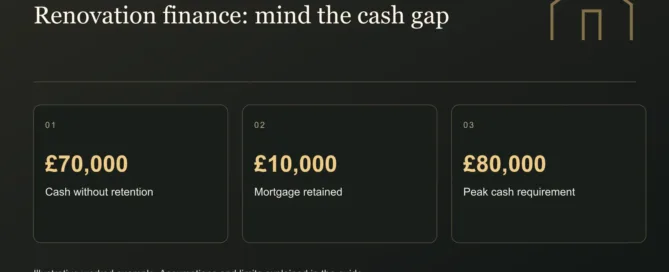
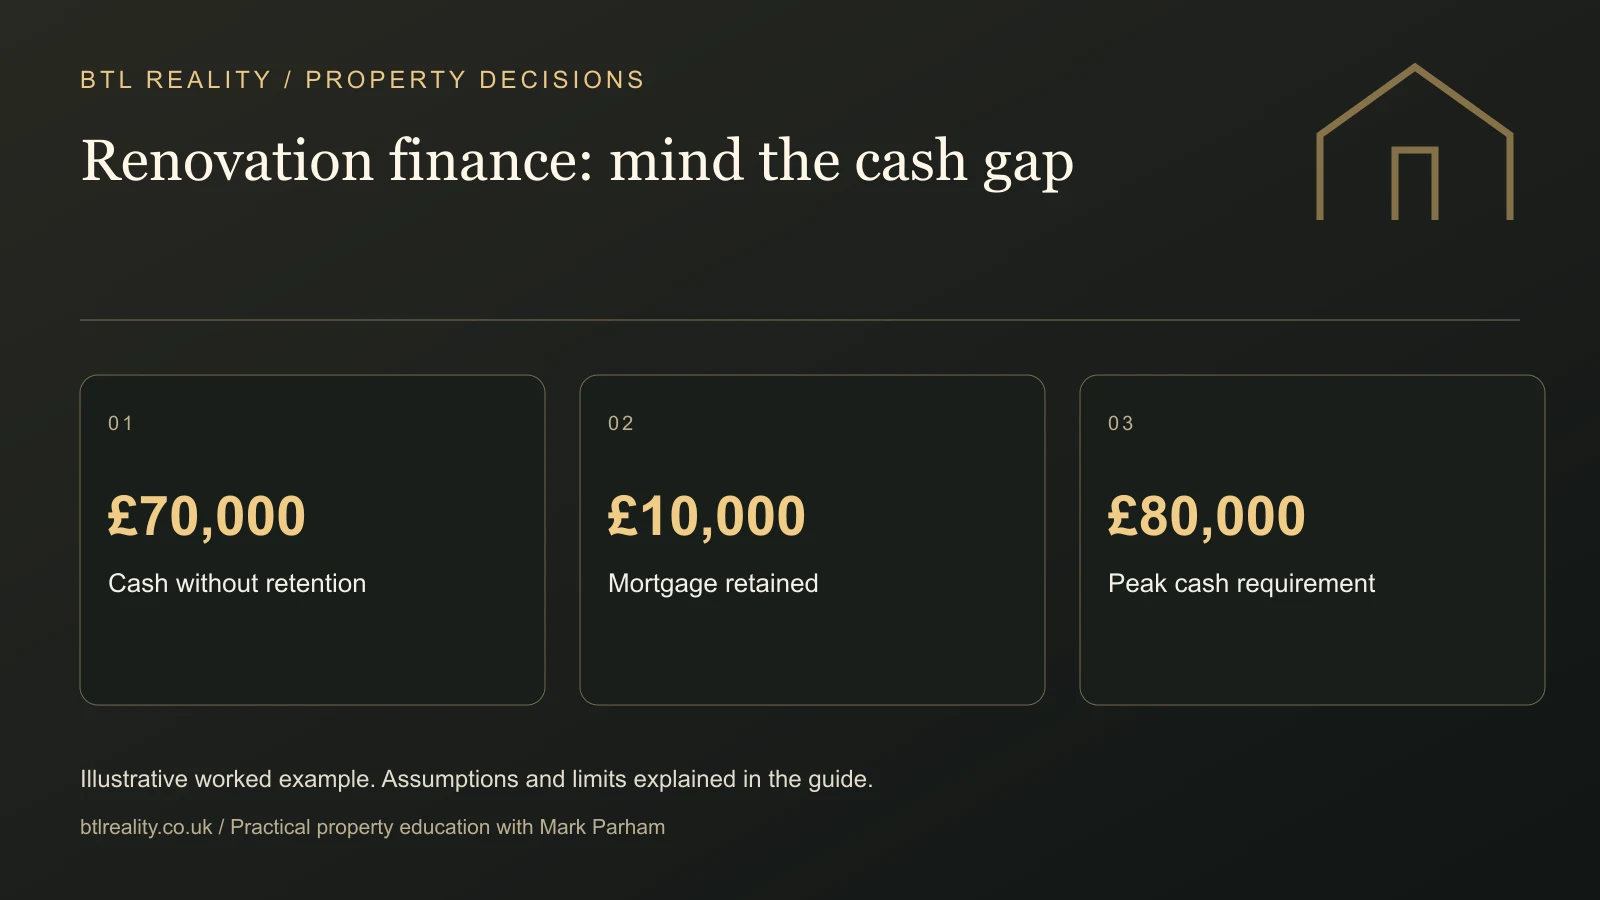
Check how property condition affects buy-to-let finance. Compare cosmetic work, mortgage retentions and specialist funding with a cash-budget example.
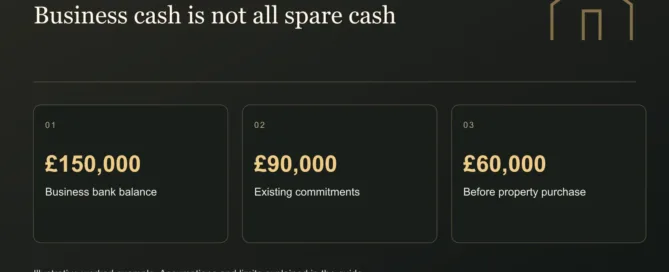
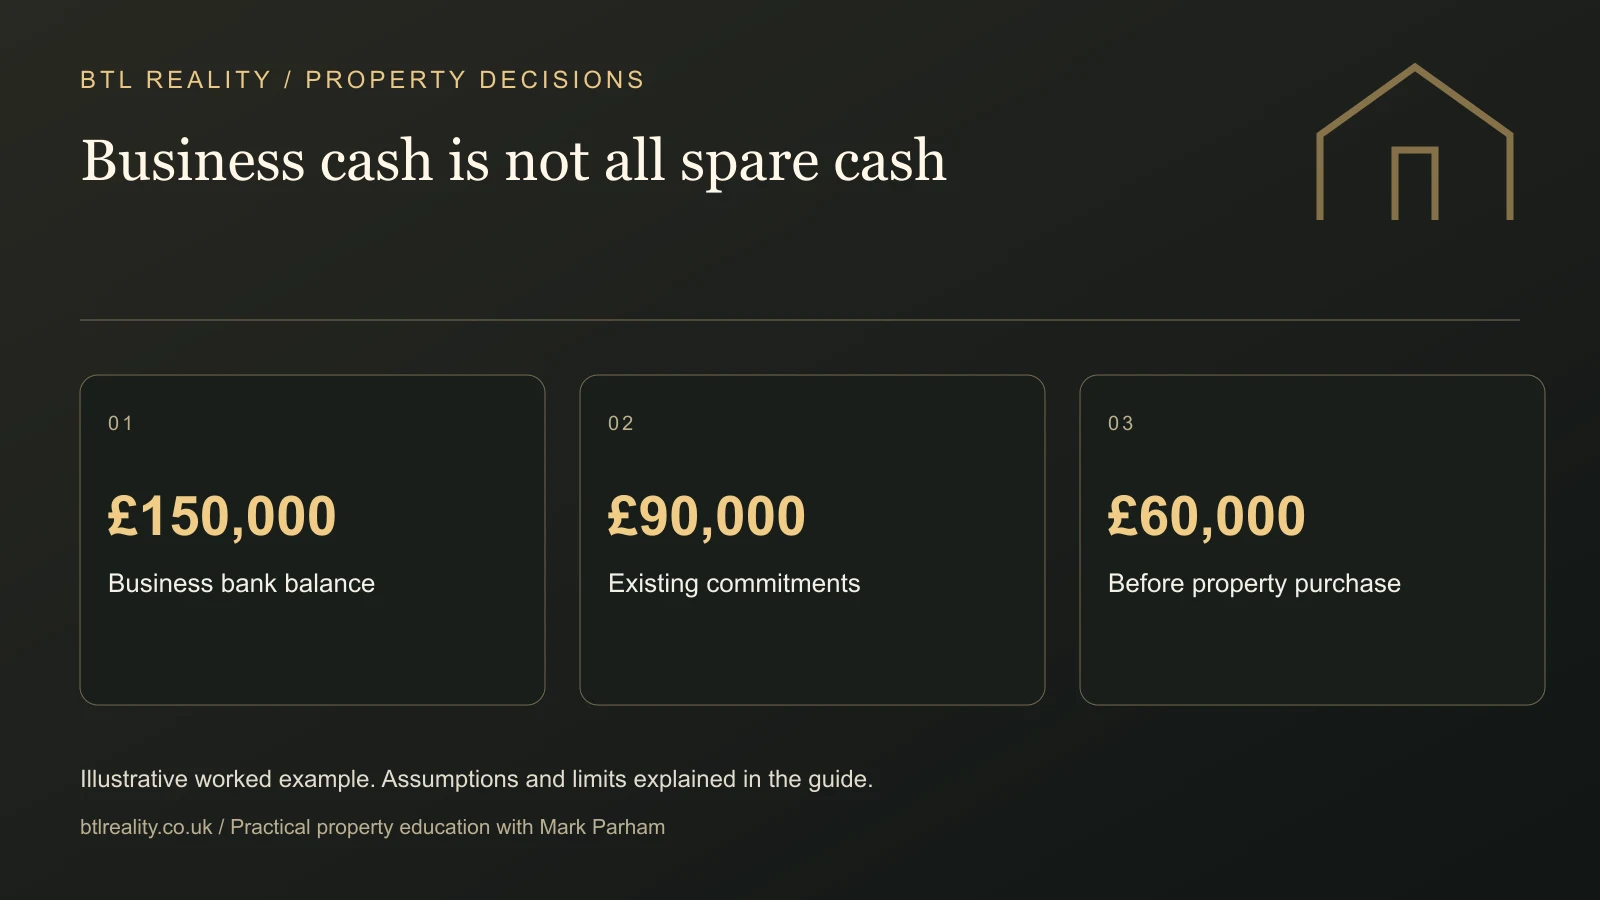
Compare buying through an existing trading company with a property SPV. Check finance, business cash, guarantees and questions for your accountant.
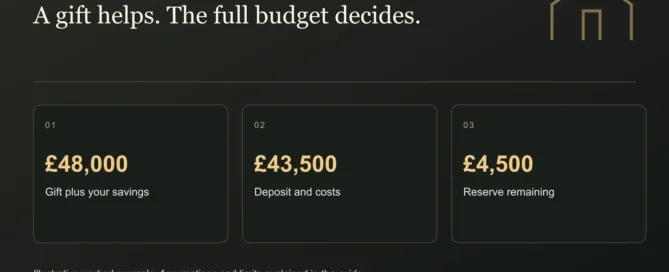
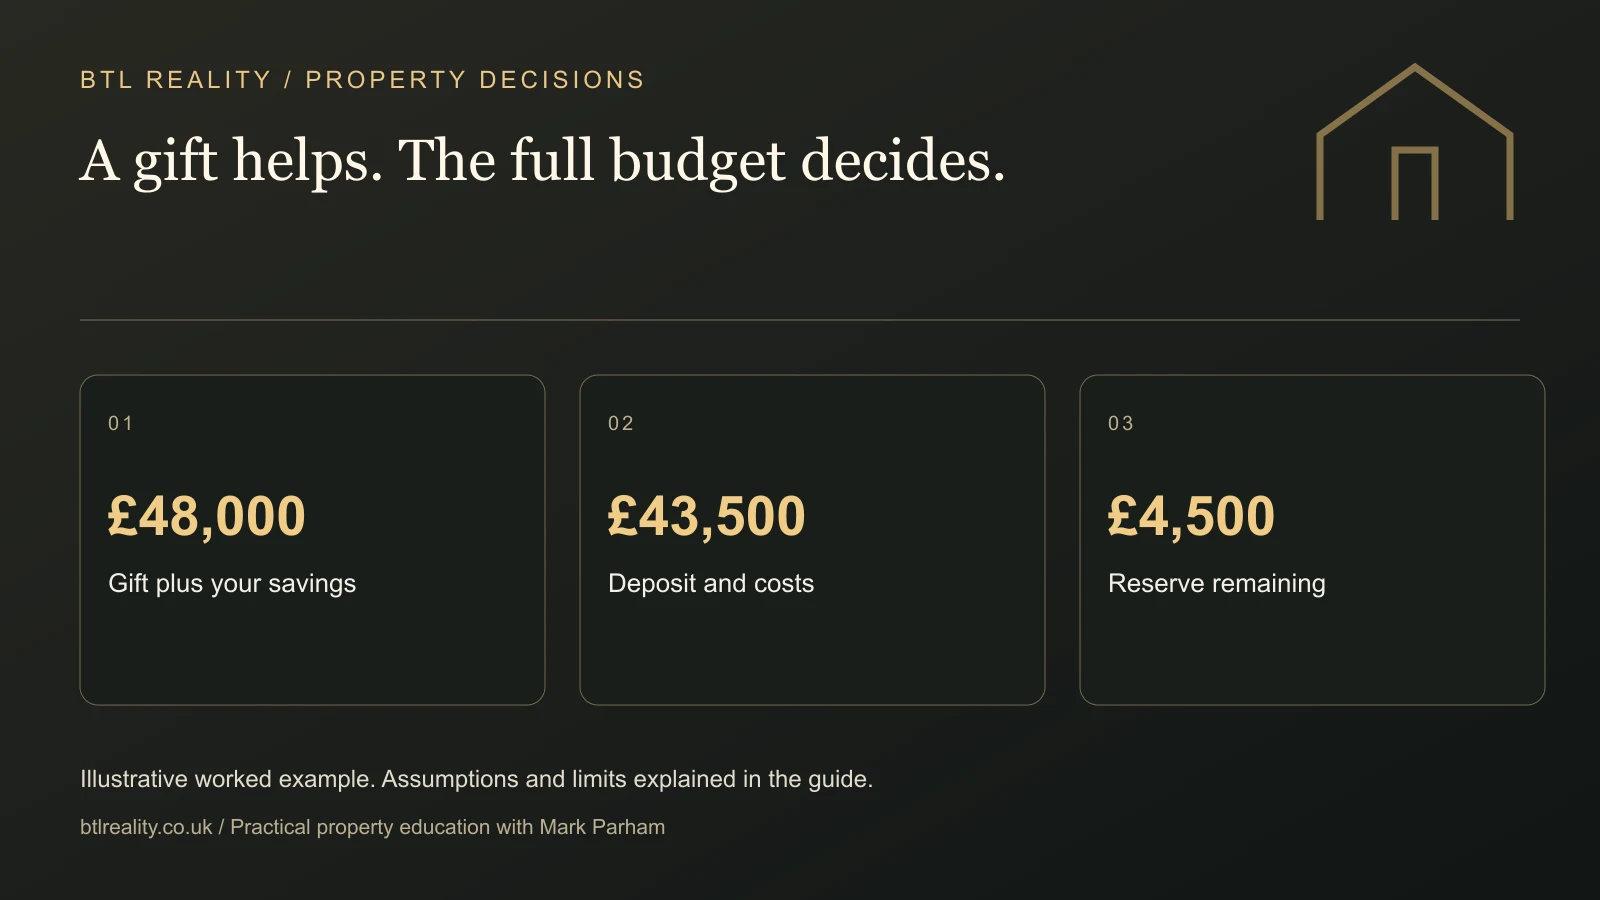
Can family help fund your buy-to-let deposit? Check lender acceptance, gift versus loan, source-of-funds evidence and the full cash budget.