UK Property Investing for Busy Professionals: A Practical Guide
October 14, 2026
Property investing for busy professionals starts with a practical question: what can you own and oversee without building a second job that you do not want? Having a salary or a deposit helps, but neither tells you which property, financing arrangement or level of support fits your life.
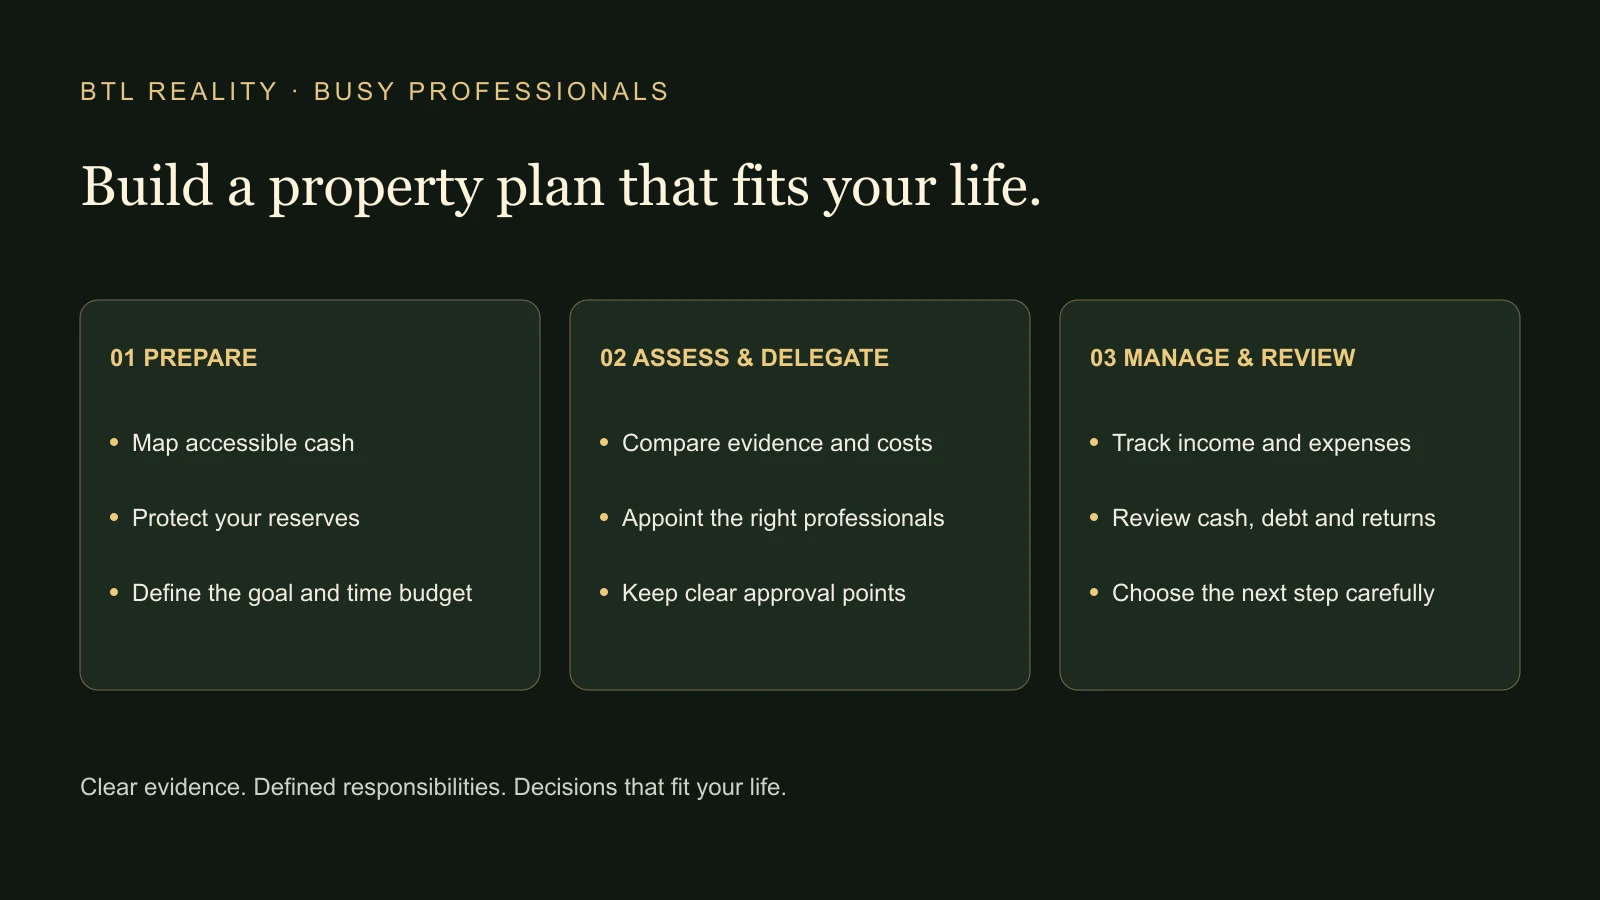
I would organise the decision into three stages: prepare your finances, assess and delegate a purchase, then manage and review the investment. This guide connects the detailed articles and free tools for each stage so you can work on the next useful decision instead of trying to learn everything at once.
It is a framework for thinking, not a recommendation to buy. Property can lose value, borrowing magnifies outcomes and neither rent nor refinancing is guaranteed. A manageable plan includes those possibilities from the beginning.
Choose your starting stage
Find your next useful task
Separate accessible purchase cash from your net worth and retained reserves.
Your selection is not saved or sent. This suggests a learning task, not a personalised investment recommendation.
If you are unsure which stage fits, begin with your current position. Looking at properties before understanding your cash commitments can make an unsuitable opportunity feel urgent. There will always be another listing; your household finances deserve a considered decision.
Stage one: prepare your finances and your time
Start with a clear distinction between net worth and cash you can actually commit. Equity in your home, pension savings and accessible bank balances are different resources with different constraints. A large balance sheet does not necessarily mean a comfortable purchase budget.
Use the net worth calculator to organise your position, then read how much money you need to start investing. The purchase budget should include more than the mortgage deposit: costs, any works and a reserve all compete for the same cash.
The cash reserves guide explains why money left uncommitted has a job. Decide how household emergencies and property problems would be funded without assuming that every investment can be sold or refinanced quickly.
Next, describe the purpose of the investment. A plan aimed at income today differs from one prioritising long-term growth or learning through a first manageable purchase. The three-step property investment plan gives you a structure for relating the objective to the next action.
Put your diary into the budget
Be honest about the time you can protect. There is a difference between two reliable hours a week and a theoretical free weekend that is routinely lost to work and family commitments. List the decisions you must make personally and the execution you might commission.
A hypothetical investor with £60,000 available might separate £10,000 as a property reserve, £8,000 for purchase costs and £5,000 for initial work, leaving £37,000 towards a deposit. Those are illustrative allocations, not recommended amounts or a statement of actual transaction costs. The point is that £60,000 is not automatically a £60,000 deposit.
The same principle applies to time. Spending your whole weekly allowance browsing listings leaves nothing for reviewing evidence, speaking with professionals or overseeing ownership. Protect a decision-making block before committing the rest to research.
Stage two: assess a deal and delegate defined work
Once your brief is clear, compare opportunities on a consistent basis. A high advertised yield can conceal additional costs, uncertain rent or a property that requires more attention than you can provide. The guide to comparing two buy-to-let deals helps you look beyond the headline.
Build an appraisal with the free deal calculator. Keep a note of where each input came from. Where a figure is only an estimate, show the effect of a less favourable outcome rather than quietly treating it as certain.
A useful proposal should answer three questions: why this property fits your brief, what evidence supports the numbers and what still needs investigation. Attractive presentation is not a substitute for any of those answers.
Assemble the right professionals
Read who you need on your property investment team to separate the roles of broker, legal professional, surveyor, accountant, letting agent and sourcer. Each has a different job and a defined scope.
Do not assume an introduction means someone else has appointed, instructed or paid that professional. Confirm who is responsible for each task and who will explain the findings to you. The gaps between services are often where a busy buyer loses track of an important issue.
If you use a sourcer, work through the sourcer due diligence guide. Agree the fee, brief and service in writing before treating someone else's shortlist as your own investment plan.
Delegate with approval points
The companion guide on delegating a property purchase sets out five approval points, from appointment to operating handover. It is designed to keep your review time focused on decisions that change the cost, obligations or risk.
Ask for a regular summary of evidence received, unresolved questions, budget changes and decisions required. An update that says “all progressing” is less helpful than one that identifies the specific finding that needs your attention.
Keep the purchase timeline guide beside the plan. Several workstreams run together, and delays are possible. A target completion date should not become a reason to ignore an unresolved legal, financial or condition issue.
Stage three: manage, measure and review
After purchase, the question changes from “does this deal look attractive?” to “is this property performing as expected, and what needs attention?” Put a simple monthly review in the diary before the first tenant moves in.
Start with rent collected, actual expenses, arrears, repairs, cash reserves and upcoming commitments. Compare actual results with the original appraisal, but do not treat every short-term difference as a reason to change the entire strategy. Separate timing effects from persistent problems.
If a letting agent manages the property, agree the reporting and approval process. Our letting agent fees guide explains why the service matters as much as the percentage. Outsourcing day-to-day tasks still leaves decisions and oversight with the owner.
Measure returns without mixing different things
Rental cashflow, changes in value and repayment of debt affect your position differently. The property return on investment guide helps distinguish them. A rise in an estimated valuation does not automatically create cash you can spend.
That matters when you are considering another purchase. Read when to refinance an investment property before assuming that growth means the next deposit is available. A refinance depends on lending criteria, valuation, costs and your circumstances at the time.
Explore alternatives using the refinance calculator, then take the relevant questions to a broker and other advisers. The calculator illustrates assumptions; it does not approve finance or predict what a lender will offer.
Which BTL Reality product fits which problem?
If your main need is understanding and ongoing accountability, Starter Club combines a personal property roadmap, monthly live group call, community and relevant professional introductions. Founding membership is £39.99 a month while the offer remains available. Mark participates in the founding group WhatsApp weekly for your first 12 months while subscribed, within the published terms.
If you prefer structured learning, explore the Blueprint. The current preorder includes an invitation to the two-day Oxfordshire recording event and access to the finished course after production. Check the provisional dates, payment options and refund deadline before booking.
If finding the property is the bottleneck, Done For You is sourcing against an agreed brief. It is not an automatic promise that all legal work, finance, refurbishment and ongoing management are included.
For more complex personal and portfolio decisions, Private Mentorship provides individual support, modelling and strategy discussions, subject to the published entry criteria. Use the free call if you need to discuss which service fits; the short form comes before choosing a time.
A practical next step this week
Choose one stage and one decision. If you are preparing, finish your cash map. If you are assessing, replace one important assumption with evidence. If you already own property, reconcile the latest figures and identify the next issue to resolve.
All our on-page calculators and resources are free to use without joining the club. Optional personalised PDF reports ask for contact details. You can use the tools, read the linked guides and decide whether paid support would help later.
A strong property plan should leave you with fewer unclear decisions, not simply more information. Progress is being able to explain what you are doing next, why it fits your position and what would make you pause.