Can I Buy a Rental Through My Existing Limited Company?
October 6, 2026
An existing limited company may be able to buy a rental property, but that does not mean it will qualify for the buy-to-let mortgage you want. A trading business and a company set up specifically for property can be treated differently by lenders. The structure also has accounting, tax and commercial consequences beyond the mortgage application.
If your business has cash available, buying property can feel like an obvious next step. I would first ask whether that cash is truly surplus, which entity should own the asset and how the purchase fits the business owner's wider plans.
Separate legal ownership from mortgage eligibility
A company owning a property is one question. A particular lender agreeing to lend to that company is another. A lender can restrict its products to certain company activities, ownership arrangements or registrations even where the proposed purchase is otherwise possible.
For example, The Mortgage Works' limited-company criteria describe lending to special purpose vehicles, or SPVs, established for specified property activities. Its policy also addresses matters such as company ownership and guarantees. That is one lender's criteria, not a universal rule for every commercial or buy-to-let lender.
The practical step is to tell the broker exactly what your existing company does and how it is owned. Do not change a description or classification merely to make a trading business look like a different borrower.
What is a property SPV?
An SPV is a company used for a particular purpose. In this context, it usually means a company focused on property ownership and letting rather than combining rentals with an unrelated trading activity.
The term does not make the business risk-free or automatically tax-efficient. You still have accounting responsibilities, borrowing costs and decisions about how money moves between you and the company. Lenders can have different requirements for acceptable activities and shareholders.
Nor does creating a fresh company mean it can immediately borrow any amount. The lender may still assess the individuals behind it, the deposit source, rental coverage, property and wider financial position. A company certificate is not a mortgage approval.
Three routes to discuss before making an offer
The first route is purchase through the existing trading company. This may keep money and property together but can narrow finance choices and mix the investment with the company's other activities and liabilities.
The second is a separate property company funded through an arrangement your accountant and solicitor have assessed. How money reaches it matters. A loan, dividend, share subscription or other transfer can have different consequences; they are not interchangeable labels.
The third is personal ownership using money you lawfully extract from the business. That requires a separate assessment of extraction costs, personal ownership and financing. Compare the complete chain rather than treating money inside a company as if it were already personal cash.
Make the example your own
Existing company or dedicated property company?
Use this to organise the evidence and questions before your next decision.
0 of 6 checks reviewed
This is an organiser, not approval to invest. Selections stay in this page and are not saved or sent.
First prove the cash is available to invest
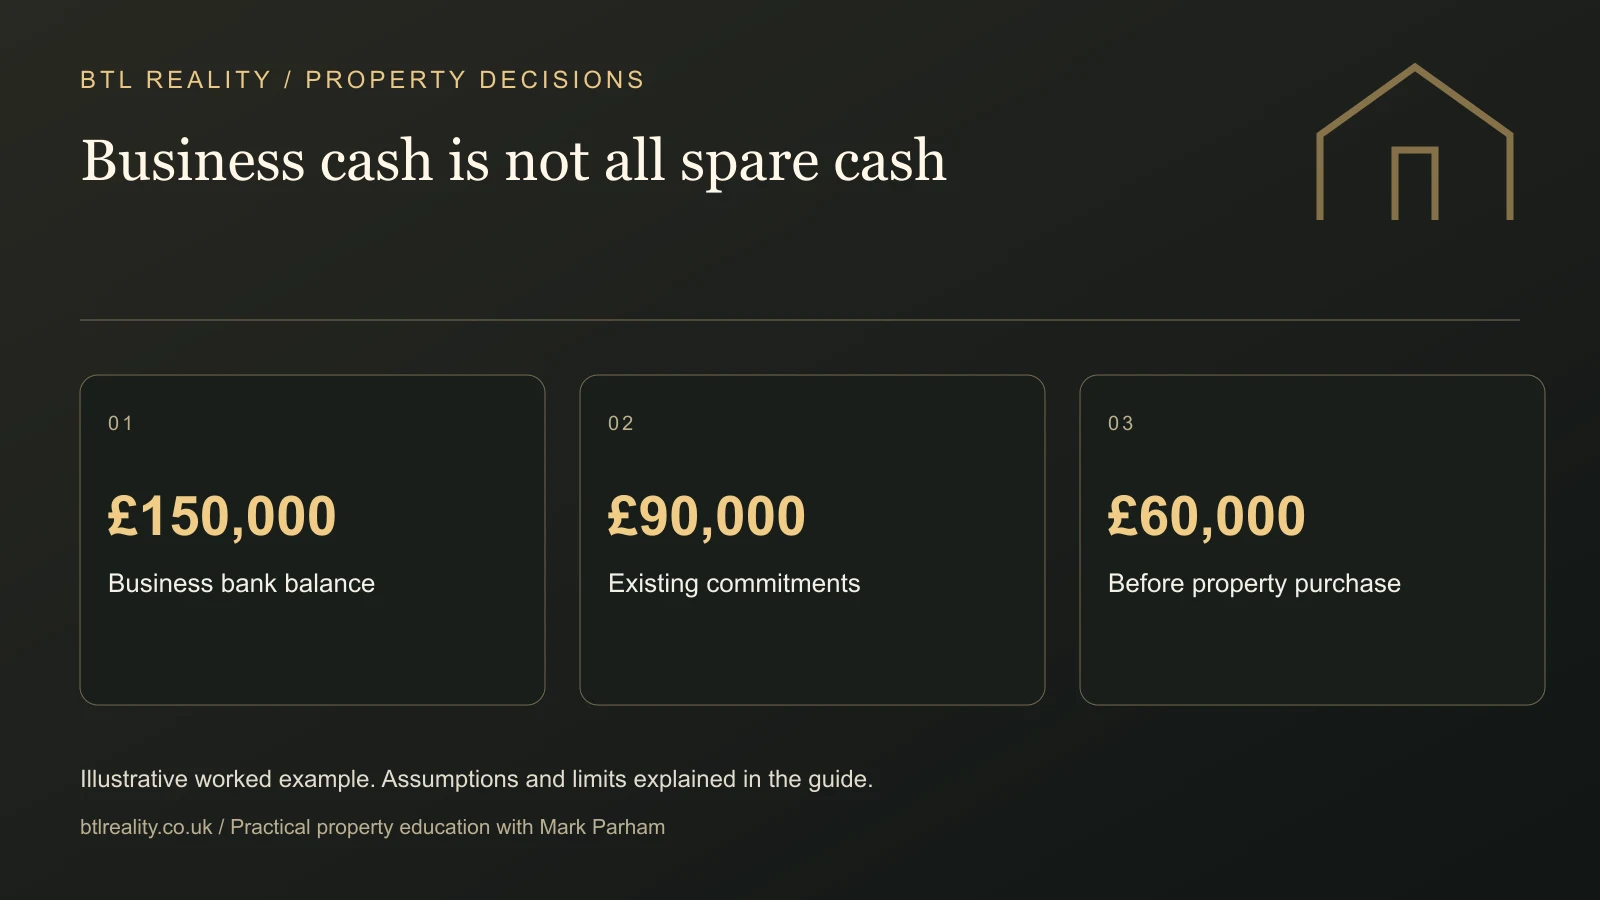
Suppose a business bank account holds £150,000. It is tempting to describe that as a £150,000 property budget. Now identify £30,000 allocated to tax, £40,000 required for ordinary working capital and £20,000 for known near-term commitments.
Only £60,000 remains before any additional safety margin. If a property requires £52,000 for deposit, costs and initial work, you would have £8,000 left from that remainder. Whether this is sensible depends on the trading business's cash cycle and the property's needs.
These amounts are an illustration, not a recommendation for reserves. The point is that a bank balance contains money with different jobs. Investing tax provisions or payroll money creates a problem even if the rental itself looks profitable.
Compare the whole cost of each structure
Ask for a comparison that includes borrowing rate, lender fees, legal costs, accounting costs, purchase taxes, ongoing tax and eventual extraction or sale. Some costs arise immediately; others appear when you want to take income personally.
Do not decide using one headline rate. A lower rate of tax inside a company does not automatically mean more money in your household after every subsequent step. Similarly, a more expensive mortgage may outweigh a projected tax benefit for a particular deal.
Use our buy-to-let deal calculator for the property economics and give those assumptions to the accountant. The calculator is not a substitute for a structure-specific tax comparison. My personal-name versus company guide introduces the broader ownership decision.
Think about business risk and future plans
What happens if the trading company faces a claim, needs funding or is sold? What happens if a co-owner wants to leave? Holding rental assets inside the same company can make those conversations more complicated.
Conversely, a separate company introduces its own administration and funding arrangements. It should not be presented as a magic shield. Security, guarantees, connected transactions and the actual legal structure affect what protection exists.
Explain your likely next five years to your advisers. A structure designed only for this month's purchase may be awkward if you later sell the trading business, bring in another investor or want to live from the rental profits.
Understand any personal guarantee
A limited company does not necessarily mean your personal exposure ends at the money invested. A lender may require directors or other relevant individuals to guarantee borrowing, subject to the wording of the agreement.
Read the guarantee with appropriate legal advice. Establish who is giving it, which obligations it covers, whether it is limited and what happens when a director or shareholder changes. Do not assume signing is a harmless formality because other landlords commonly do it.
This is a reason to compare risk alongside return. Borrowing through a company can be commercially useful while still creating personal obligations. Both facts can be true, and the decision is better when neither is hidden.
Keep the paperwork and money trail clear
The company buying the property should be clearly identified from the start. Tell the estate agent, broker and solicitor which entity is intended to purchase and who can authorise decisions. Changing the buyer late can introduce delay and additional work.
If funds come from another business or a director, document the arrangement and keep appropriate records. Confirm what the lender accepts before transferring money. An accountant recording a transfer correctly does not, by itself, mean the lender accepts that deposit source.
Keep personal and company spending separate. GOV.UK's guidance on taking money out of a limited company explains why different types of payment require different treatment. Those distinctions also matter when you later want the rental portfolio to support your lifestyle.
Questions for the accountant, broker and solicitor
- Is the proposed investing money genuinely surplus to business obligations and working capital?
- Which ownership routes fit the commercial objective, rather than just this mortgage application?
- Which lenders accept the actual company activity, ownership and deposit source?
- What guarantees, security or connected-company obligations would be required?
- What is the combined cost now, during ownership and when money is withdrawn or the property sold?
- What changes if the trading business is sold, an owner leaves or your residency changes?
Get the professionals discussing the same facts. Three individually sensible answers can still conflict if the accountant assumes one structure, the broker another and the solicitor receives a third instruction.
Choose the structure before committing
I would rather spend time resolving ownership and funding before agreeing an aggressive completion deadline. That preserves choices and makes the property search more accurate. The aim is a purchase that fits both the investment and the business behind it.
For help organising the wider property strategy, Private Mentorship describes the support and application criteria. It can sit alongside professional mortgage, legal and tax advice; it does not replace it. Start with a clear brief, an honest cash budget and a structure the relevant professionals have actually assessed.
Frequently asked questions
Can my trading company get a buy-to-let mortgage?
It depends on the lender and company circumstances. Some buy-to-let products are restricted to property SPVs, while other finance routes may consider trading businesses. Give the broker the actual activities, ownership and accounts. Do not assume that a product advertised for limited companies accepts every type of limited company.
Do I need a new company for each rental property?
Not necessarily. The appropriate structure depends on financing, ownership, risk, administration and future plans. Creating multiple companies introduces additional obligations and may not improve the result. Discuss the intended portfolio with your accountant and broker before deciding, rather than treating a separate company per property as a universal rule.
Can my business lend money to a property SPV?
That possibility needs an assessment of the actual companies, ownership, lender rules and legal and tax consequences. Do not transfer money first and ask later. The accountant, solicitor and broker should understand the same proposed arrangement, including repayment terms and how it affects the trading business's liquidity and obligations.
Does adding a property SIC code turn my trading company into an SPV?
No label alone changes the business's real activities or makes it acceptable to a lender. The application must accurately describe the company, its history and ownership. Ask the broker what the lender requires and your advisers whether a structural change is appropriate. Do not use a classification change to conceal ongoing trading activity.
Am I personally liable for a limited-company property mortgage?
Your exposure depends on the agreements, security and any personal guarantee. A company borrower may still require individuals to assume obligations. Have the documents explained before signing, including limits, enforcement and changes in ownership. Limited-company status by itself is not enough to conclude that your personal assets cannot be exposed.
Is buying property through a company always more tax-efficient?
No. The comparison depends on your income, financing, costs, plans for profits, eventual sale and extraction, among other factors. A company-level tax figure is only one stage. Obtain a current comparison of the full ownership period and household outcome before choosing a structure, especially where an existing trading business is involved.
Put the next step into practice
Use the free tools to test your numbers, then choose the level of support that fits your next decision.