Do I Need a Separate Bank Account for Rental Income?
October 19, 2026
A separate account for rental income is usually a practical way to keep the property finances clear, even where an individual landlord is not subject to a blanket rule requiring a dedicated account. A limited company's position is different: its money and records should be kept distinct from the director's personal finances, using an appropriate account for the company.
The account itself does not calculate profit, protect a tenant deposit or make spending deductible. Its value is that it makes receipts, costs, reserves and owner transfers easier to understand. This guide explains a simple setup that helps you see what the property actually produces and what cash is already committed.
Start with the ownership structure
If you own the rental personally, the income and expenses belong in your personal property-business records, subject to the relevant tax rules. A separate account can simplify those records without changing who owns the property or how it is taxed.
If a limited company owns the property, rental receipts and expenses are company transactions. GOV.UK's company-record guidance explains the records directors must maintain. Running company activity through a personal spending account makes that distinction harder to demonstrate and manage.
Ask the bank which account is appropriate and whether its terms permit the intended use. An account marketed as personal may restrict business activity, even where you are an individual landlord. The bank's product terms and the legal ownership question are related but not identical.
A separate balance is useful, but not a profit figure
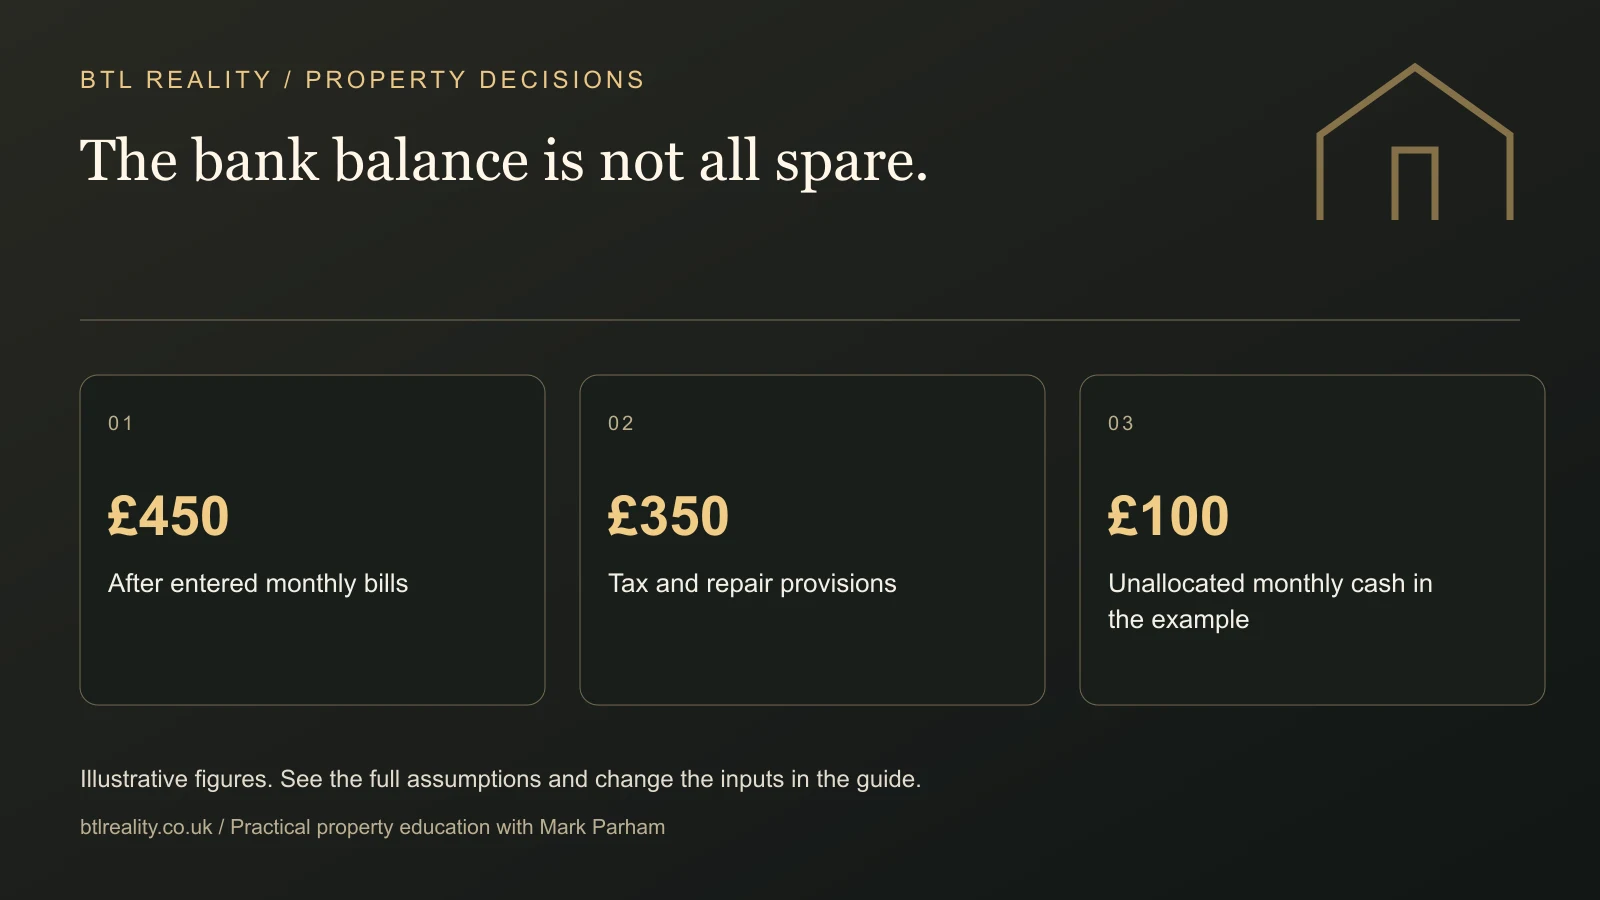
Imagine £1,200 rent arrives. The property pays £500 mortgage costs and £250 other operating bills, leaving £450 in the account from that month's activity. It is tempting to call the £450 spare money.
Now allocate an illustrative £150 towards future tax and £200 towards repairs or vacancy reserves. Only £100 remains unallocated under that plan. The account still contains money earmarked for future obligations, so the visible balance can overstate what you can sensibly withdraw.
The tax provision is an example, not a calculated liability. Taxable profit and cashflow can differ, especially with different ownership and mortgage arrangements. Ask the accountant to establish the appropriate provision and review it as the year develops.
Make the example your own
How much of the monthly cash is unallocated?
Separate paid bills from money earmarked for future tax, repairs and vacancies. Provisions are your planning amounts.
No tax liability is calculated. Reserve transfers are not expenses for tax just because money is set aside. Negative unallocated cash means the planned allocations need funding or review. Excludes existing balances and unentered obligations. Illustrative only. Inputs stay in this page and are not saved or sent.
The calculator separates cash after entered bills from cash after your planned provisions. Moving money into a reserve is not itself a tax-deductible expense. It is an allocation that helps prevent future commitments being mistaken for spendable income.
Keep five categories visible
A simple system distinguishes rent received, operating payments, finance payments, reserve allocations and transfers involving the owner. Within the records, retain enough detail to identify the property, date, supplier or payer and purpose.
Rent received is not necessarily rent due. A late payment or part-payment should be visible rather than hidden by a monthly total that looks close enough. Likewise, a payment from you to top up the account is funding, not additional tenant income.
An owner withdrawal is not automatically an expense of running the property. For a company, the transfer might be salary, dividend, expense reimbursement or director-loan repayment, each requiring the correct treatment. Record what it actually is rather than using a generic label for everything.
Reconcile the agent statement with the bank
Where a letting agent collects rent and deducts fees or repairs before paying you, the bank receipt may be a net amount. The underlying records still need to show the gross rent and the deductions, with supporting statements and invoices.
For example, a £1,000 rent payment less £120 management and a £180 repair produces a £700 transfer. Recording only £700 rent can obscure both the income and the costs. On the other hand, recording £1,000 plus the £700 bank transfer as income would double-count receipts.
Reconcile the statement to the account each month. If the amount differs, identify whether it relates to timing, arrears, a retained balance or another deduction. Small unexplained differences become harder to resolve when several months accumulate.
One account per property is optional, not a universal answer
For a small personally owned portfolio, one dedicated rental account with clear property-level records may be manageable. Separate accounts or pots can make particular reserves or joint-ownership arrangements easier to follow, but they also create more transfers and administration.
For different legal owners or companies, keep the ownership boundaries clear. Do not mix several entities' receipts in one account simply because the same person controls them. Ask the accountant how the arrangement should be structured and recorded.
Choose the simplest system that preserves a reliable audit trail. Five accounts with poor descriptions can be less useful than one appropriate account with excellent reconciliation and separate records for each property.
Reserves should be allocated, not counted several times
If £10,000 is earmarked for repairs and vacancies across four properties, it is one £10,000 fund. It is not £10,000 protection for each property simultaneously. Keep the total available cash and the intended allocations visible together.
You may choose separate savings pots for tax, known work and emergency costs, subject to suitable account access and terms. The label does not change the ownership or tax character of the money, but it can improve spending discipline.
Review access timing too. Money needed for an urgent repair should not be assumed instantly available if it sits in a product with notice periods or withdrawal restrictions. Match the cash arrangement to the purpose, not just the advertised interest rate.
A tenant deposit is not your operating reserve
Handle tenancy deposits through the required protection arrangements and records for the relevant jurisdiction and tenancy. A separate rental bank account does not by itself satisfy deposit-protection obligations.
Do not count a refundable tenant deposit as money available to cover routine mortgage payments, improvements or personal spending. Keep the liability and protection status clear so the cash position is not overstated.
GOV.UK's tenancy deposit guidance provides the starting point for the applicable protection process. Check the rules relevant to the actual tenancy, particularly where the property is outside England or Wales.
Record money you put in and take out
For an individual landlord, owner funding and drawings should be distinguishable from rental receipts and property costs. Retain explanations for transfers so your accountant can follow the transaction without guessing from a bank reference.
For a company, money introduced by a director may be recorded as a loan or another properly documented funding route. Our director's loan guide explains why money the company owes you differs from company profit and why the balance needs regular reconciliation.
If you pay a company expense personally, keep the invoice and obtain the correct accounting entry. Avoid repeatedly moving money in and out without records, then treating the final bank balance as evidence that everything has cancelled out correctly.
Tax records need supporting evidence
A bank statement proves a payment moved; it does not necessarily establish what was bought or how it should be treated for tax. Keep invoices, receipts, agent statements, mortgage records and relevant correspondence in an organised file.
GOV.UK's rental-tax guidance distinguishes income and allowable expenses and notes differences in treatment. Your accountant should determine the actual position rather than the account name or a budgeting category doing that work.
A repairs pot does not make every eventual project a revenue expense. Our repairs versus improvements guide explains why the nature of the work matters. Keep a description of substantial projects alongside the payment record.
A short monthly review is enough to catch many problems
Choose a regular review date. Match expected rent to receipts, reconcile agent statements, categorise payments, update reserves and investigate unexplained transactions. Then compare the actual month with the forecast.
Ask whether the apparent surplus depends on an unpaid bill, a personal top-up or a reserve that has quietly been spent. Note upcoming insurance renewals, mortgage changes and known work so the next few months are visible, not just the last one.
Keep the process proportionate. You do not need a complicated dashboard to spot missing rent or an upcoming £3,000 bill. You need accurate records and a habit of looking at them before transferring money out.
Use clearer banking to make better investment decisions
Once the records are reliable, compare each property on actual receipts, costs and cash demands. This helps you decide whether to improve an existing asset, strengthen reserves or buy another one. An attractive forecast is less useful if you never compare it with reality.
The free property portfolio calculator helps explore future scenarios, while Starter Club supports practical planning. Start with your verified current figures and keep the difference between profit, cash and returned capital visible.
A separate account is a tool for clarity. The stronger habit is knowing what every important balance represents and which part of it is actually available for your next decision.
Frequently asked questions
Must an individual landlord use a separate rental bank account?
There is no single blanket requirement that every individual landlord must open a separate account solely for rent. However, accurate records are necessary and the bank's terms may restrict business use. A dedicated appropriate account often makes reconciliation and financial decisions much easier.
Can a limited company use the director’s personal account?
The company is a separate entity and its finances should be kept distinct, using an appropriate company account. Mixing them with personal spending creates accounting and control problems. Ask the bank and accountant about the correct setup and properly record any director-funded expenses or transfers.
Should each property have its own account?
Not necessarily. One suitable account with clear property-level records may work for a small portfolio under the same ownership. Separate legal entities need clear boundaries. Choose a system that supports reliable reconciliation without creating unnecessary transfers or confusing one property's reserve with another's.
Where should I hold repair and tax reserves?
Use suitable accounts or clearly tracked allocations with access that matches when the money may be needed. Keep the ownership and total available cash clear. A reserve label is a budgeting tool, not a tax deduction or a guarantee that the eventual bill will match the amount saved.
How should I record money I pay into the rental business?
Identify it as owner funding rather than rent and retain the transfer evidence. For a company, agree whether it is a director loan, share funding or another appropriate entry. Record repayments and withdrawals consistently so the account balance and amounts owed can be reconciled.
How often should I reconcile rent and expenses?
A monthly review is a practical starting point, with more frequent checks where transactions or risks justify them. Match rent, agent deductions, bills and owner transfers to the records. Resolve discrepancies promptly and update upcoming commitments before deciding how much cash is available to withdraw.
Put the next step into practice
Use the free tools to test your numbers, then choose the level of support that fits your next decision.