Repairs or Improvements: Which Rental Property Costs Are Deductible?
October 12, 2026
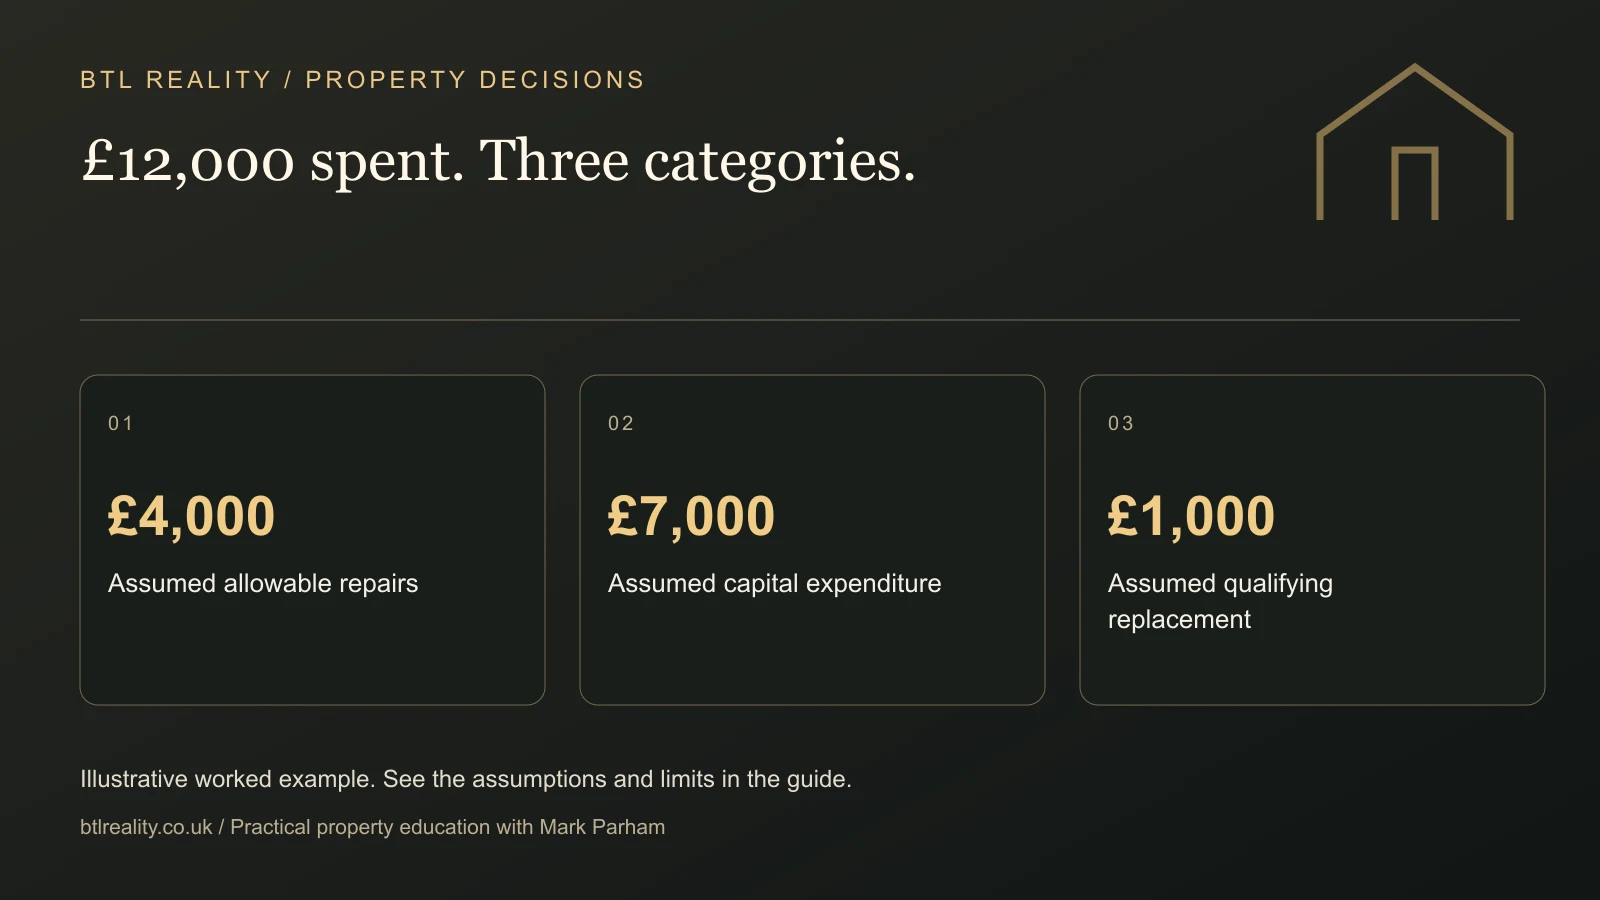
A rental property can consume £12,000 of cash without giving you a £12,000 deduction against this year's rental income. The difference usually starts with what the work actually does. Restoring an existing feature, creating something new and replacing furniture can fall into different tax categories, even when the same builder sends one invoice.
The useful habit is to keep two records: the cash you spent and the tax treatment your accountant confirms. Both matter. Confusing them can make a property look more profitable than it is, or leave you relying on a tax saving that never arrives. This guide explains the questions to ask, with illustrative examples rather than a personalised tax calculation.
Start with the work, not the description on the invoice
A builder might describe an entire job as a refurbishment. That word does not decide whether the expenditure is a repair or capital improvement. Ask what existed before, what changed, whether the asset was restored or substantially enhanced, and whether separate jobs can reasonably be identified.
HMRC's repairs guidance distinguishes ordinary repairs from capital expenditure. Using a modern equivalent does not automatically turn a repair into an improvement. However, substantially changing or reconstructing an asset can produce a different answer. The surrounding facts matter more than the headline price.
Consider repainting tired walls, building an extension and replacing a tenant's worn washing machine. All three might be sensible landlord expenditure. They do not become the same tax category simply because they make the property easier to rent. Rental purpose is one question; the character of the spending is another.
Before commissioning a large project, put each element on its own line. Record the original condition, proposed specification and reason for doing it. This also helps you challenge unnecessary work. Good records improve the investment decision before they help with the tax return.
Repairs normally restore what was there
A repair generally puts an existing asset back into working condition. It does not need to use obsolete materials or reproduce every detail. The practical comparison is the property's function and character before and after the work, assessed in context.
For example, repairing a leak and making good damaged plaster differs from adding an entirely new room. Replacing a worn component might still be repair work, while replacing or creating an entire asset can require different treatment. Do not use the size of the invoice as your only test. A large repair is not automatically capital, and a cheap improvement is not automatically deductible.
Keep dated photographs and the inspection report showing the defect. Ask the contractor to describe the work accurately rather than choosing wording to support a preferred tax outcome. Your accountant needs evidence of what happened, not an invoice engineered around a deduction.
Improvements need their own investment case
An improvement may create additional space, increase capability or substantially change the asset. If expenditure is capital, it generally does not reduce ordinary rental profit in the same way as an allowable revenue repair. Possible relief on a later disposal depends on the relevant rules and circumstances; it is not a promise that every capital pound will eventually be recovered.
This makes the purchase appraisal important. Suppose you propose a £15,000 alteration because you expect another £100 monthly rent. That is £1,200 additional gross rent a year before extra costs, vacancies, tax or finance. The project needs justification on those economics, not an assumption that you can immediately write off its whole cost.
There may be other reasons to proceed, such as making a property suitable for the intended tenants or reducing future maintenance. State those benefits separately. A claimed increase in resale value should have evidence, and it should not be counted as spendable cash before a sale or completed refinancing.
Use the buy-to-let deal calculator to include the full works budget in your cash requirement. Tax classification does not make the contractor's payment disappear.
A kitchen replacement is not one universal answer
A kitchen is a useful example because people often ask for a simple yes or no. Replacing a worn kitchen with a broadly comparable standard can differ from materially upgrading it as part of a larger redevelopment. Layout changes, extensions and the relationship between individual elements can affect the analysis.
Give your accountant both specifications. Include cabinets, appliances, plumbing, electrical work and any structural alteration. Identify which items were already present and which are being introduced for the first time. Do not assume that everything bought from the same kitchen supplier follows one treatment.
The purchase context matters too. A kitchen in a functioning rental that has worn out is a different factual starting point from a derelict building bought for conversion. An online example cannot decide the treatment without those facts.
Furniture and appliances have separate questions
Replacement domestic items relief has its own conditions. HMRC's property income manual explains that qualifying replacements differ from initial furnishing, with limits where an upgraded item replaces the old one. Disposal proceeds and associated costs can also matter.
Record the old item, why it needed replacing, the replacement purchased and what happened to the original. Keep receipts for removal or delivery where relevant. An appliance that is part of a larger building project may need careful analysis rather than a quick category selected in bookkeeping software.
The management benefit is straightforward: an inventory makes the next replacement easier to budget. If you have several properties, identify the address and item on every receipt. A folder of unlabelled purchases creates avoidable uncertainty when your accountant prepares the return months later.
A worked example: the cash leaves either way
Imagine a landlord spends £12,000 on a mixed project. After reviewing the actual facts, their accountant classifies £4,000 as allowable revenue repairs, £7,000 as capital expenditure and £1,000 as a qualifying domestic replacement. These classifications are assumptions for this example, not rules for your project.
The bank account is £12,000 lower. Under the assumed treatment, £5,000 enters the relevant current expense calculation, while the £7,000 is recorded separately. It would be wrong to show only £5,000 of spending in the property's cashflow, or to deduct the full £12,000 from rental profit without checking.
A deduction also is not a refund of the invoice. In a simplified illustration, an eligible £1,000 deduction reducing income taxed at 20% saves £200 of tax. The expense still costs £800 after that assumed saving. Your actual result depends on the applicable rules, tax position, losses and timing.
Run the rental yield calculator using the real operating costs, then obtain a separate tax calculation. Gross yield, cashflow and taxable profit answer different questions. None should be used as a substitute for the others.
Build your evidence file before the work starts
Use this checklist to organise a discussion with your accountant. Completing it does not classify the expenditure or confirm eligibility for relief. The aim is to make the professional review quicker and more useful.
The £12,000 project: assumed accountant classifications
Make the example your own
Build the works evidence file
These checks help your accountant assess the facts. They do not produce an automated tax classification.
0 of 6 checks reviewed
This is an organiser, not approval to invest. Selections stay in this page and are not saved or sent.
For mixed works, ask for sensible itemisation at quotation stage. Trying to reconstruct a split after completion is harder, especially when labour covered several tasks. Keep evidence of the allocation method as well as the final figures.
Do not claim the same expenditure twice through different categories. Equally, do not discard uncertain invoices. Put them in a review folder with the relevant facts so they can be considered properly.
Work before the first tenant needs extra care
The date of the first tenancy does not settle every question. HMRC's pre-commencement guidance describes circumstances in which qualifying revenue expenditure before a property business begins may be considered. Capital expenditure does not become a revenue expense simply because it was incurred shortly before letting.
Explain whether this is your first rental, another property in an existing business, or a former home. Explain whether the property was usable when bought and whether the price reflected its condition. Private use and the nature of the initial works can change the analysis.
From an investment perspective, budget for every pre-let month. Council tax, insurance, finance and utilities may continue while rent is absent. Ask about tax treatment separately, but keep those cash commitments in the project forecast regardless of the answer.
Turn the records into a better buying decision
Before approving a refurbishment, write down the work needed to make the property safe and lettable, optional improvements, expected downtime and the remaining contingency. Then compare the resulting all-in cost with a property that already meets your brief.
This is where clear thinking beats a headline discount. A cheaper purchase can require more cash and expose you to more uncertainty. Conversely, planned work can be worthwhile when its cost, delivery and tenant benefit are well supported. The tax category alone does not decide which route is better.
Starter Club provides property education and support with planning your next steps. Use that support to improve the investment questions you ask, while retaining a qualified accountant for your own tax treatment and reporting.
Frequently asked questions
Is a replacement kitchen a repair or an improvement?
It depends on the actual work and wider project. A broadly comparable replacement of a worn kitchen may differ from substantial enhancement or redevelopment. Provide before-and-after specifications, photographs and itemised costs to your accountant instead of relying on the invoice label alone.
Can I deduct repairs before the first tenant moves in?
Potentially, where the expenditure and circumstances meet the relevant rules. The distinction between revenue and capital still matters, as do the start of the property business and any private use. Keep the evidence and have the treatment checked before submitting your return.
Is replacing single glazing with double glazing an improvement?
Not automatically for this tax distinction. HMRC recognises that using a modern equivalent can still form part of a repair. The context and scale of the wider works matter, so do not extend that example into a rule that every window-related project is immediately deductible.
Can I claim mortgage capital repayments as an expense?
Repaying borrowed capital is not an ordinary rental expense deduction. Interest and other finance costs are separate, and personal residential landlords and companies can face different treatment. Keep repayment and interest figures separately so cashflow is not mistaken for taxable profit.
What records should I keep for mixed repair and improvement work?
Keep itemised quotes, invoices, payment records, dated photographs, survey findings, specifications and the reasons for each task. Note the property address and any reasonable cost allocation. Retain the accountant's classification so the same expense is not later treated inconsistently or claimed twice.
Are the tax rules identical for personal and company landlords?
No. Although understanding the nature of the expenditure matters in both cases, the applicable tax system and finance-cost treatment can differ. Ask for advice based on the actual owner and business structure. A calculation for another landlord may not describe your position.
Put the next step into practice
Use the free tools to test your numbers, then choose the level of support that fits your next decision.