Can I Rent a Buy-to-Let Property to a Family Member?
October 13, 2026
You may be able to provide a rental home for a family member, but you should not assume an ordinary buy-to-let mortgage allows it. The relationship can affect the mortgage route, and discounted or informal arrangements can affect the tax analysis. A supportive family decision still needs a workable property budget and properly checked legal arrangements.
This is a different question from whether your relative will pay reliably. A lender can restrict family occupation even when the proposed tenant has a strong income and would pay full market rent. Conversely, buying without a mortgage removes the lender's permission question but does not remove landlord duties, tax considerations or the need to agree how the home will be used.
Start with the intended arrangement, describe it accurately to your advisers and build the figures around the rent you will actually receive.
Tell the broker who will live there
Explain the exact relationship, whether you will also occupy the property, who owns it and whether ownership is personal or through a company. Do this before choosing a product or making a binding commitment. The relevant mortgage route depends on the facts, not the label you give the property.
As one lender example, The Mortgage Works' general criteria exclude letting to immediate family members. Other options must be considered on their own terms. Charging a normal rent does not override a lender's occupancy restriction.
The FCA's mortgage perimeter guidance distinguishes arrangements involving occupation by the borrower or related people when explaining regulated mortgage contracts and buy-to-let exclusions. Rather than self-classifying from an internet definition, ask a qualified mortgage adviser to identify the appropriate route for your circumstances.
Do not submit an application describing an unrelated tenant if the actual plan is for your child or parent to move in. Accuracy now prevents the investment being built around finance that does not fit its intended use.
Separate three reasons for buying
You might want to earn a commercial return, help a relative obtain a stable home, or do both. None of those intentions is inherently wrong, but the budget needs to reflect them honestly. A property offering family support at a discount should not be presented to your own finances as if it produces full market income.
Write down the priority. If the main goal is support, how much monthly subsidy can you afford? If the main goal is investment, would you apply the same rent, deposit, maintenance standards and tenancy terms to an unrelated applicant? If the goals conflict, decide how you will resolve that before the keys are handed over.
Also consider duration. A two-year plan may change if the relative's job, health or household changes. You cannot assume that an informal understanding provides a simple right to recover possession on a particular date. Have the arrangement checked against the law applying where the property is located.
Model the discounted rent explicitly
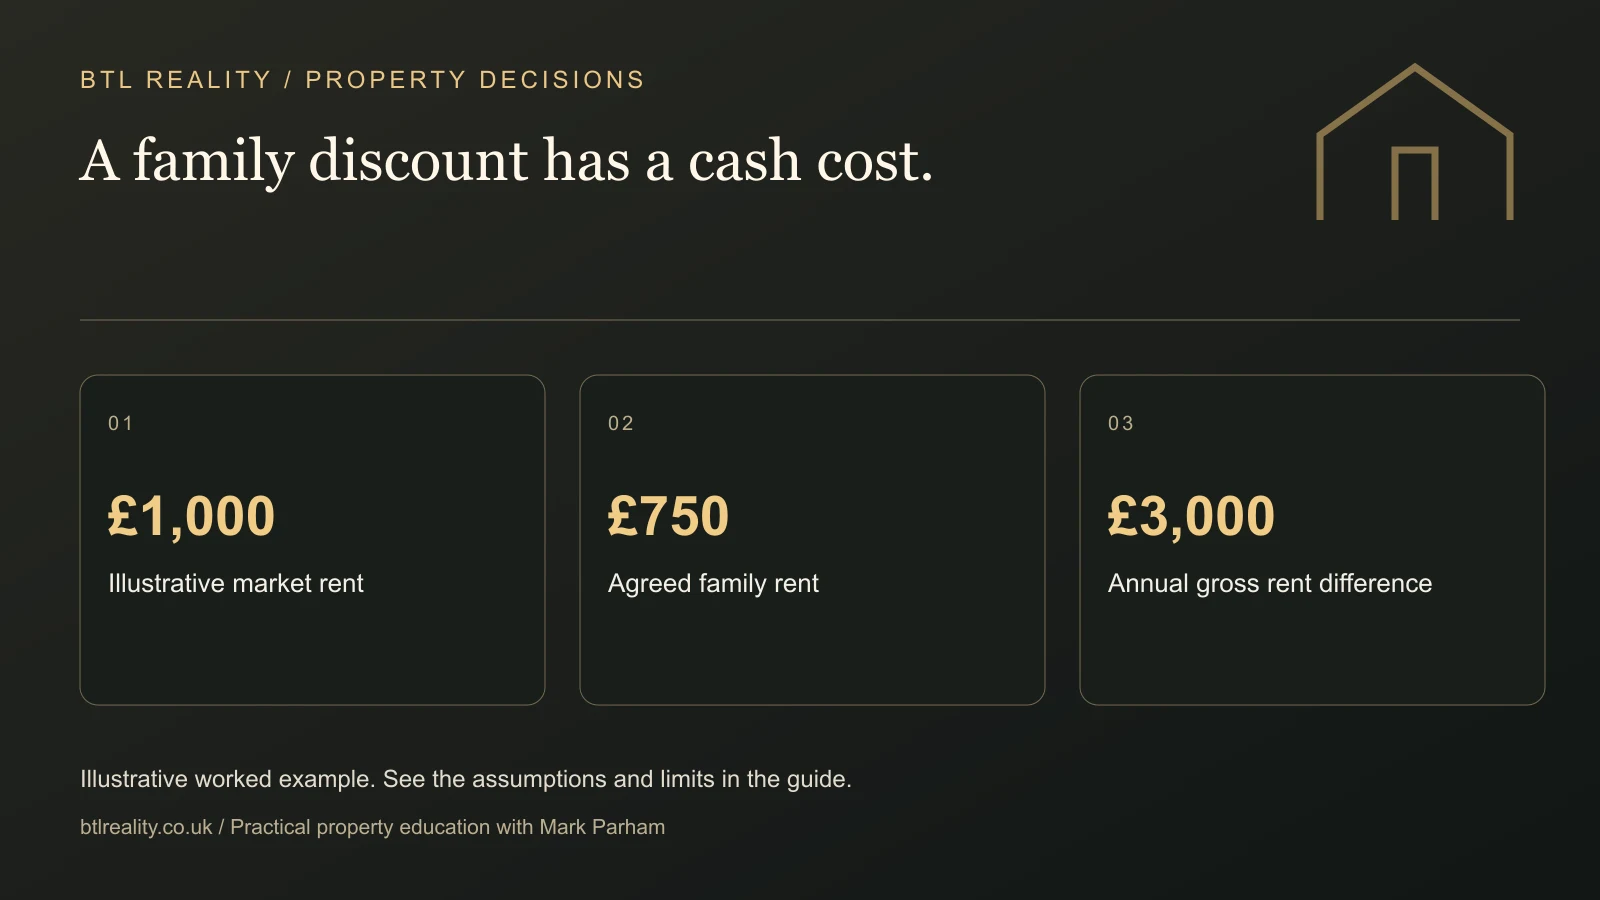
Assume a property could achieve £1,000 monthly rent on normal commercial terms. Suppose the family arrangement is £750, while monthly mortgage payments are £500 and operating costs and allowances are £250. At full rent, the simplified cashflow is £250 monthly before tax. At the discounted rent, it is zero.
The £250 monthly discount costs £3,000 a year in foregone gross rent. Over three years with unchanged figures, that is £9,000. It may be support you are happy to provide, but it is still a real difference in the plan.
Now raise the finance payment to £650. Full-rent cashflow becomes £100 monthly, while the family arrangement needs £150 from you each month. That is £1,800 annually before tax or exceptional costs. A £2,500 repair would be additional, not covered by an income surplus that no longer exists.
Make the example your own
What does discounted family rent change?
Compare market rent with the rent you intend to charge. This is cashflow only, with no tax or lending assessment.
No tax, voids, exceptional repairs or rent changes. A negative cashflow needs funding from elsewhere. Family occupation and expense deductions require separate checks. Illustrative only. Inputs stay in this page and are not saved or sent.
The calculator compares cashflow only. It does not decide whether the proposed mortgage is permitted, whether the tenancy is legally appropriate or which expenses are deductible. Those questions need separate answers before the model becomes a real arrangement.
Below-market letting can change the tax result
HMRC's guidance on properties not let at a commercial rent explains restrictions where a property is provided rent-free or on uncommercial terms. For below-market letting, its guidance limits expense deductions to the relevant rental receipts rather than allowing an excess to create a loss available against other commercial lettings.
The important distinction is the commercial nature of the arrangement, not simply the surname of the tenant. Full market rent and normal terms need to be evidenced if that is the position you are claiming. Discounts, private use and mixed arrangements should be explained to your accountant rather than hidden inside an ordinary rental spreadsheet.
Do not apply a headline tax rate to the cashflow calculator and assume you have the answer. Mortgage capital payments, finance-cost treatment, ownership and expense classification can produce differences between cashflow and taxable profit. Ask for a calculation based on the actual arrangement.
Agree the practical responsibilities in writing
Families often avoid paperwork because it feels unnecessarily formal. Clear terms can reduce future tension by making ordinary expectations visible. Who pays utilities? Who reports repairs? Can another person move in? What happens if the rent becomes unaffordable? How will inspections and access be arranged lawfully?
Use appropriate professional help to establish the correct agreement rather than copying a form intended for a different type of occupation. The legal position can depend on whether the landlord lives there, the nature of the arrangement and the UK nation involved. A written label alone cannot change the underlying facts.
Keep the property's maintenance standard independent of the family relationship. A relative should not be expected to tolerate an unsafe or poorly maintained home because the rent is discounted. Equally, the owner needs a clear process for being told about problems before they become expensive damage.
Make a reserve for the relationship as well as the property
The reserve is not only for broken boilers. It also gives you time to respond sensibly if your relative loses income. If missing one rent payment means you cannot meet the mortgage, both the investment and the family relationship are under immediate pressure.
Suppose unavoidable monthly costs during non-payment are £700 and you want to model six months plus a £3,000 repair. That scenario needs £7,200: six times £700, plus £3,000. It is an illustrative planning figure, not a required or universally sufficient reserve.
Keep this money distinct from funds earmarked for other properties or household emergencies. If the same £7,200 is protecting three separate commitments, the spreadsheet is overstating your resilience. Use the buy-to-let deal calculator to establish the full purchase cash requirement before allocating any remaining savings.
Check insurance, lease and local requirements
Tell the insurer the actual occupancy and letting arrangement. Confirm the relevant cover, exclusions and conditions in writing. Do not assume a normal home policy, or a policy chosen for an unrelated tenancy, automatically fits the family arrangement.
For a leasehold property, ask the conveyancer to check the lease and any necessary permissions. Local licensing and landlord requirements may also apply. A family connection is not a universal exemption from property regulation, and requirements differ across the UK.
GOV.UK's landlord responsibilities overview provides a starting point, with links to the relevant guidance. Use it alongside advice for the property's location and your exact arrangement. The aim is to resolve these issues before occupation, not discover them when an insurer, lender or council asks a question.
Plan how the arrangement could change
Agree how you will review the rent and what information will trigger a discussion. The owner's finance costs may change, while the relative's ability to pay may not. A review process is more useful than a vague expectation that everyone will work it out later.
Think through a sale, a change of owner, separation, illness or death. These are reasons to obtain appropriate legal and estate-planning advice, particularly where several family members contribute money or expect an eventual share of the property. Do not assume that paying part of the deposit creates the ownership arrangement everyone has in mind.
Keep investment decisions and promises aligned. If you tell a relative the home is secure for the long term, do not fund the purchase with a strategy that requires selling quickly if refinancing is unavailable. The financial plan should support the commitment you are making.
Choose a plan you can explain without optimistic assumptions
A sensible family letting arrangement has confirmed finance, appropriate legal terms, a clear tax treatment and cashflow based on the actual rent. It also states the subsidy you are choosing to provide and the reserve that supports it.
If you want help understanding property budgets and comparing ways to build your portfolio, Starter Club can support that planning. Mortgage, tax and tenancy decisions still belong with the relevant qualified advisers. The best outcome is a home that works for your relative and a commitment you can sustain without pretending it is a different investment.
For the spending side of the plan, our guide to rental repairs versus improvements explains why paying for work and obtaining a tax deduction are separate questions.
Frequently asked questions
Can my child live in my buy-to-let property?
Possibly, but you must check the mortgage conditions before occupation. Some ordinary buy-to-let lenders prohibit immediate family tenants. Explain the relationship and ownership to a qualified adviser so the correct route can be considered. A child paying full market rent does not automatically remove the restriction.
Do I need a different mortgage to let to family?
You may need a different product or lending route, depending on the arrangement and lender. Family occupation can affect how the mortgage is classified and assessed. Do not assume consent will be given after completion; resolve the intended use before relying on a particular loan.
Can I charge a relative below-market rent?
You can consider a discounted arrangement, subject to the applicable mortgage, legal and other requirements. Budget using the discounted amount and check the tax consequences. The subsidy is still a cost to your finances even if you are happy to provide it and no money changes hands separately.
Do family tenants still need a tenancy agreement?
Have the correct legal arrangement documented for the circumstances and jurisdiction. Family occupation does not justify assuming that ordinary rights and responsibilities disappear. A solicitor or appropriately qualified housing adviser can identify the suitable terms, particularly where occupation is shared or the arrangement is informal.
Can discounted family letting affect deductible expenses?
Yes. Uncommercial letting can restrict deductions and the use of losses. The precise treatment depends on the facts, including rent, terms, private use and ownership. Explain the arrangement to your accountant and retain evidence rather than assuming the property's cash deficit is automatically a tax loss.
Who should check the mortgage and tax position before I proceed?
Use a qualified mortgage adviser for lending suitability, a property tax accountant for the tax treatment and a conveyancer or housing solicitor for the legal arrangement. Give each the same accurate facts. Their answers need to fit together before you commit to the purchase or allow occupation.
Put the next step into practice
Use the free tools to test your numbers, then choose the level of support that fits your next decision.