Should I Buy an Off-Plan Property as a Buy-to-Let?
October 19, 2026
Buying off-plan means committing to a property before it is completed, usually using plans, specifications and a proposed delivery timetable. It can offer a new home with a particular layout or location, but it also creates a gap between the purchase decision and the moment you can inspect, finance and let the finished asset.
The key question is not whether new-build property is good or bad. It is whether the contract, funding, price and delivery risks work together for your circumstances. This guide shows how to investigate those risks and model a delay or lower completion valuation before signing a binding agreement.
A developer discount is not proof of market value
An advertised reduction from a launch price does not establish what an independent buyer or mortgage valuer will consider the completed property worth. The starting price may itself be a marketing figure. Incentives, furniture packages or paid fees also need to be understood and disclosed to relevant professionals.
Compare completed sales of suitable properties, adjusting cautiously for location, size, specification, tenure and timing. A brand-new unit may differ from older stock, but that does not justify any premium the brochure suggests.
Ask what evidence supports the rent as well as the price. A developer's rental forecast should be checked independently with local letting agents and relevant completed lets. Keep the forecast separate from any contractual arrangement, and examine the terms of anything described as guaranteed.
Know when you become committed
Reservation, exchange and completion can involve different payments and obligations. Your solicitor should explain the actual documents, including what is refundable, what can be retained and what happens if either side cannot perform.
Do not assume a reservation payment has the same protection as a contract deposit, or that all money paid towards a new build is automatically protected. Ask how each payment is held, who receives it and what security or protection applies to that amount. NHBC's pre-completion cover explanation illustrates that protection has specific qualifying events and policy conditions; confirm the actual cover on your purchase.
The developer's sales team can explain its process, but your independent solicitor should interpret the legal commitment. A deadline to reserve at a promotional price is not a reason to sign terms you have not understood.
Investigate the developer and the deliverable
Review the developer's relevant track record, completed projects and the entity you will contract with. A familiar marketing brand and the legal seller are not always identical. Ask your solicitor what checks are appropriate for the structure and deposit arrangements.
Read the specification carefully. Establish the included finishes, appliances, parking, storage, outdoor areas and rights to shared facilities. Ask what substitutions or variations the contract permits and how a material change would be handled.
Clarify the inspection, snagging and handover process. A warranty or developer promise is not the same as a perfectly finished property on day one. Include time and cash for identifying and resolving issues before assuming rent starts immediately after legal completion.
Make the example your own
What if completion is later and the valuation lower?
Keep the contracted price fixed, then vary the accepted value and delay. A deposit already paid is credited towards the price.
Simplified lending basis; other criteria may reduce the loan. Gross rent delayed is not net profit lost. No contract rights, deposit protection, lender approval, interest on tied-up money or cost timing is inferred. Illustrative only. Inputs stay in this page and are not saved or sent.
The model compares the effect of delay and a lower valuation. It does not assess the contract, developer solvency, mortgage approval or deposit protection. Those are separate checks that cannot be reduced to a forecast return.
A completion valuation can create an extra cash demand
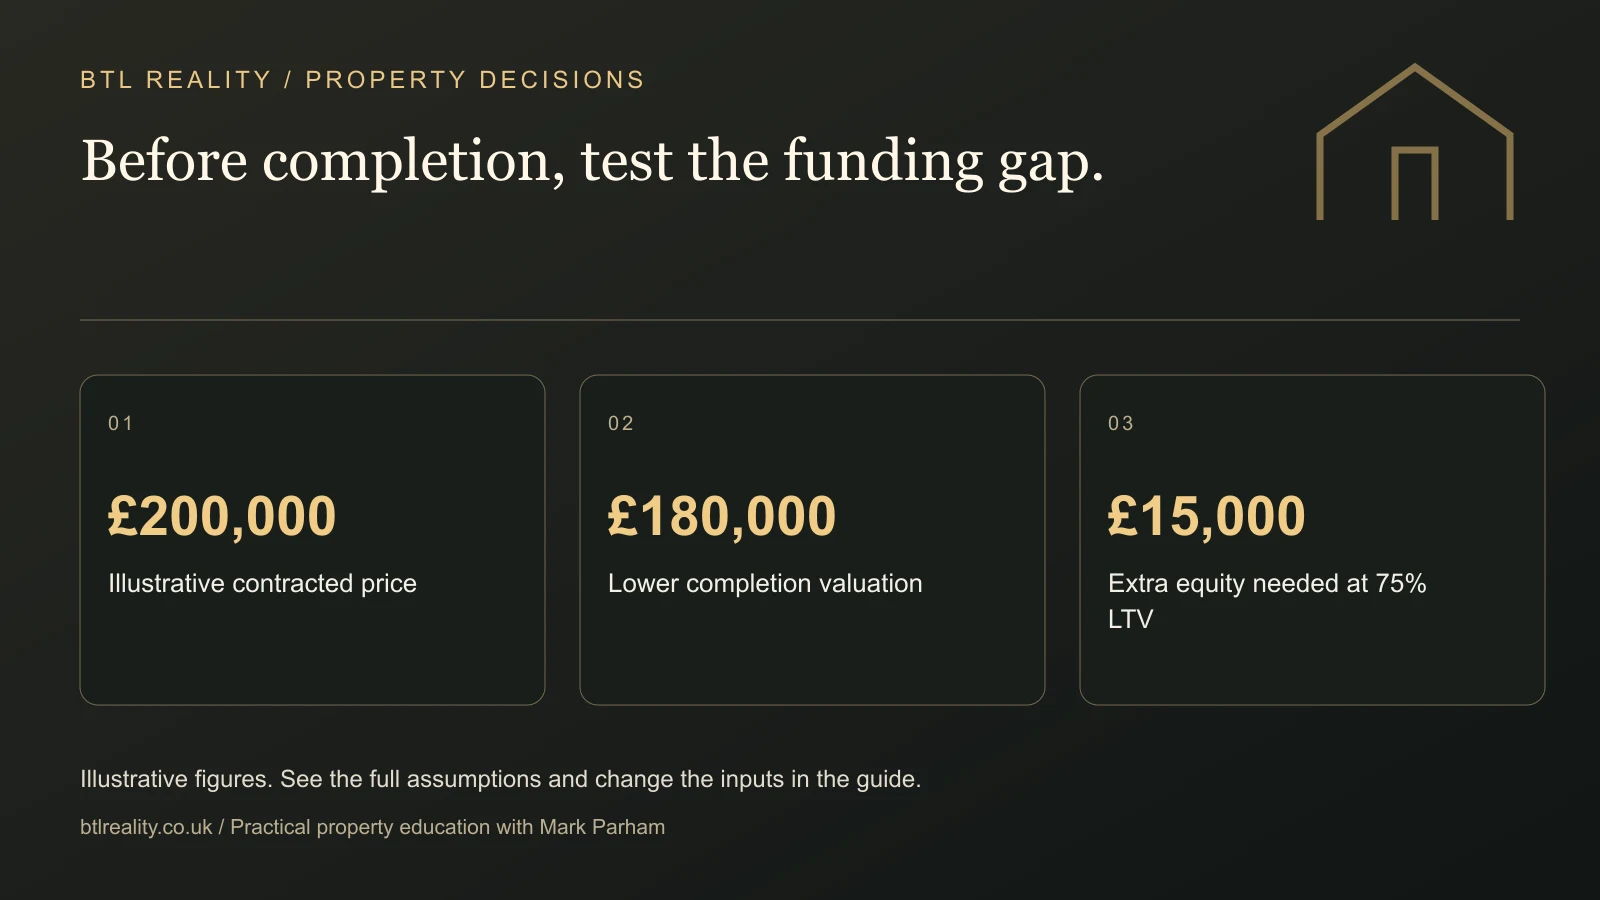
Imagine an agreed price of £200,000 and an expected 75% loan-to-value mortgage. The assumed loan is £150,000 and the total equity contribution towards the price is £50,000, before transaction costs and reserves.
If the lender accepts a completed value of £180,000 and limits borrowing to 75% of that value, the loan falls to £135,000. The equity contribution needed to pay the unchanged price rises to £65,000. That is £15,000 extra cash.
Any deposit already paid is part of the equity contribution, not an additional cost to add twice. If you have already paid £20,000, the remaining price contribution in this lower-valuation example is £45,000, plus other completion costs. Check the actual contract and lender treatment of incentives or retentions.
The down-valuation guide explains the same mechanism for a conventional purchase. Off-plan buying can make it harder to respond because your commitment may predate the final valuation.
Delay affects more than the first rent payment
Suppose the intended rent is £1,200 a month and completion is six months later than expected. That represents £7,200 of gross rent arriving later than the original plan. It is not automatically a £7,200 net loss: some costs may also start later, and the relevant comparison depends on what else you could have done with the capital.
Still, the timing can matter. Money tied up in a deposit is not available for another purchase or an emergency. If you rely on rental income beginning by a specific date, a construction delay can affect the wider household or portfolio plan.
Model three cases: the expected timetable, a moderate delay and a longer delay combined with a weaker valuation. You are not forecasting that these events will occur. You are checking whether your commitment remains fundable if they do.
Mortgage offers and building timetables can diverge
A mortgage offer has a validity period, while a development has an estimated completion programme. One does not automatically extend to match the other. Ask the broker how the lender handles new-build delays, extensions and updated valuations.
The Mortgage Works' general criteria provide one example of specific offer-validity and new-build extension arrangements. Do not apply that lender's policy to every product or assume an extension preserves the same rate and loan amount.
Our mortgage offer expiry guide gives a practical timeline check. If completion may move beyond the funding deadline, raise the issue before you are left choosing between expensive emergency finance and a contractual problem.
Understand the long-stop and delay provisions
Ask the solicitor to explain the expected completion wording, notice-to-complete process and any long-stop date. Find out what rights you have if delivery slips, what notice is required and whether recovering money could involve conditions or a dispute.
A long-stop provision is not the same as a guarantee that the property will be finished on the original target date. Nor should you assume every contract contains identical cancellation rights. Read the actual mechanism with your adviser.
Keep the dates and triggers in a concise summary alongside the mortgage deadlines. This helps you see where a contractual commitment might remain in place after your original funding plan stops working.
Review the lease and building costs before completion
For a flat, obtain advice on the lease, service charges, management arrangements and rights over shared areas. Initial budgets may be estimates rather than a long history of actual costs. Ask how the building will be managed as units are occupied and facilities become operational.
Clarify planned amenities and when they are expected to be available. A tenant may value a gym or concierge, but those features also create ongoing costs. Do not count the rental benefit from a facility while omitting its service-charge burden.
Review letting restrictions, including any limits on short stays or use by multiple occupants. Buying a new flat does not automatically permit every rental strategy shown in the developer's investment presentation.
Compare off-plan with an available alternative
Model a completed property you could realistically buy instead. Compare total cash, expected income, condition, management effort and the timing of rent. Off-plan may still fit your objectives, but the comparison should include the cost of waiting and the remaining uncertainty.
Use the buy-to-let deal calculator for each option. Keep appreciation assumptions separate from operating income. If the off-plan case only wins because you assume a large price increase before completion, make that dependence explicit.
For BTL Reality's Done For You sourcing service, the agreed brief should set out whether off-plan opportunities are acceptable and what evidence and cash limits apply. A finished, rentable property may better suit someone who values immediate visibility and a simpler funding sequence.
Make the decision with the complete commitment visible
Before signing, summarise the money due now, money due later, funding conditions, delivery rights, expected rent, building costs and downside cash requirement. Identify which points are confirmed and which remain estimates.
A good-looking brochure can explain an idea beautifully, but the investment rests on documents, evidence and your ability to fund the less convenient outcome. Proceed only when the potential benefit makes sense alongside the risks you are actually agreeing to take.
Frequently asked questions
Is an off-plan discount the same as proven market value?
No. A reduction from a developer's advertised price does not establish independent value. Check relevant completed-sale evidence and disclose incentives to your broker and solicitor. The mortgage lender's eventual valuation may differ from both the original launch price and your agreed purchase price.
What happens if completion is delayed?
The contract determines the relevant rights, obligations and possible remedies. A delay can postpone rental income and keep capital tied up, while affecting mortgage validity. Ask the solicitor to explain the delay and long-stop provisions and model the cash consequences before committing.
Can my mortgage offer expire before the property is ready?
Yes. A construction programme and a mortgage-offer deadline are separate. An extension or new offer may be possible but is not automatic. Discuss the lender's process early and test the outcome if rates, valuation or your circumstances change before completion.
What if the completed property is valued below the agreed price?
The mortgage may be smaller, increasing the cash you need to complete at the contracted price. Your contractual options need legal advice. Model the shortfall in advance rather than assuming the developer must reduce the price or the lender must use the agreed figure.
Is my reservation payment or deposit protected?
Do not assume it is. Ask the solicitor to identify the protection, holder, limits and conditions for each payment, including any relevant warranty or deposit arrangement. Different payments can have different treatment, and a marketing statement does not replace the actual documents.
What should my solicitor check before I commit?
Ask about the seller, title, contract, deposit arrangements, specification changes, completion triggers, long-stop provisions, lease and relevant approvals or warranties. Coordinate this with the broker's funding review. The exact checks depend on the development and contract, so obtain transaction-specific independent advice.
Put the next step into practice
Use the free tools to test your numbers, then choose the level of support that fits your next decision.