Gilt Yields and Mortgage Rates: What Higher UK Borrowing Costs Mean
I explain the connection between government borrowing costs and mortgage pricing, and why I want property deals to work without relying on cheaper debt.
I explain the connection between government borrowing costs and mortgage pricing, and why I want property deals to work without relying on cheaper debt.
I separate the home I want to live in from the properties I want to invest in. My Dubai rental shows why flexibility and the use of capital matter to me.
A quarter-point rise adds £5,000 a year to £2 million of interest-only borrowing. I explain how I review cash flow, refinancing dates and new purchases.
One landlord’s reason to sell can be another investor’s opportunity. I explain how I assess the seller, the price, the borrowing and the rental figures.
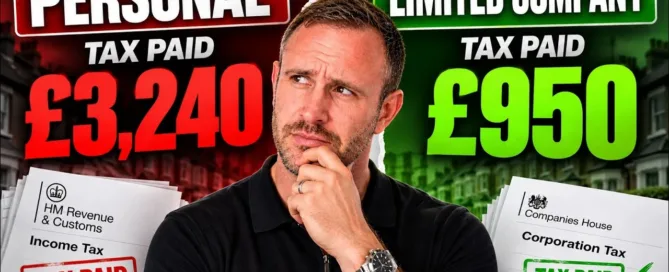
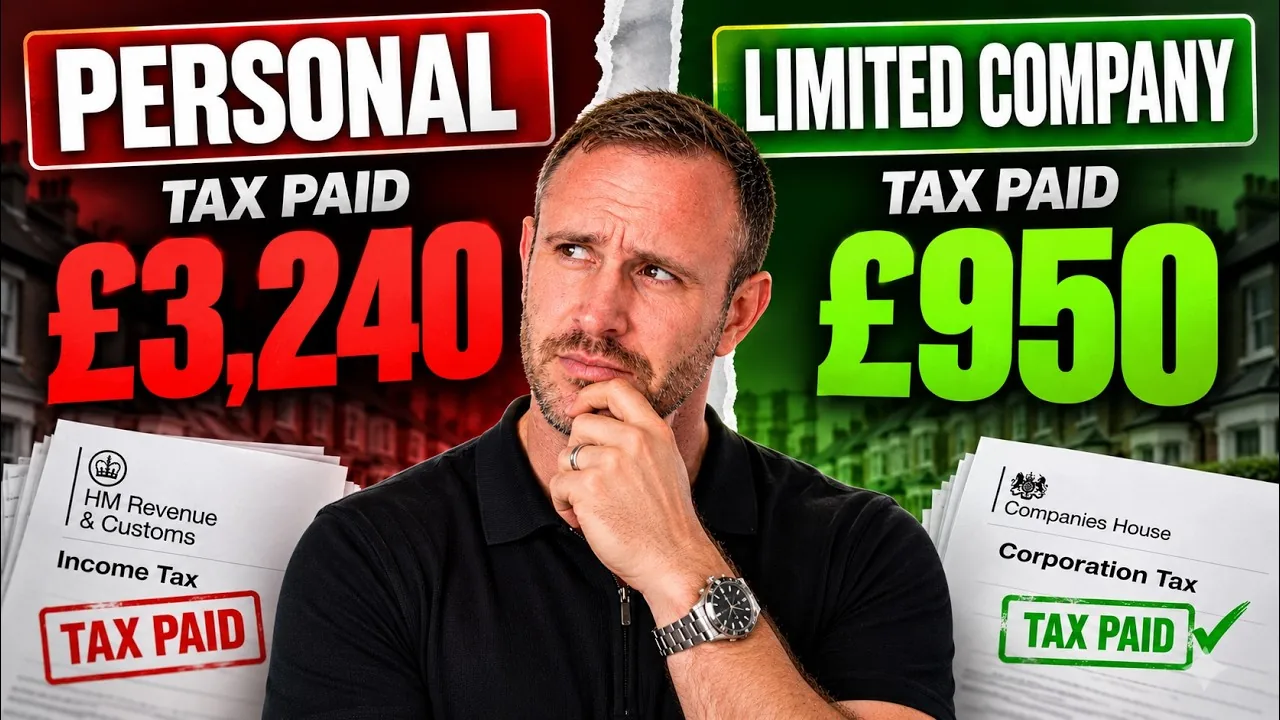
I compare personal and company buy-to-let ownership, a £150,000 tax example, reinvesting profits and how to plan for taking money out.
My £50,000 property plan: buy below market value, retain rent and refinance carefully. I explain the ten-year model, costs and assumptions.
I explain August 2026’s 2% asking-price fall, why it differs from sold prices and how I look for value when buyers have more negotiating power.
I compare saving, index funds and property on the journey to your first £100,000, including monthly contributions, debt, cash and equity.
My beginner’s guide to index funds: diversification, fees, ISAs, monthly investing and the assumptions behind building a £1 million portfolio.
I compare property and index funds using my ten- and twenty-year examples, explaining discounts, leverage, rental income and the costs models miss.