Does Adding a Bedroom Really Improve a Rental Property’s Return?
October 19, 2026
Adding a bedroom improves a rental property's return only if the resulting accommodation is lawful, desirable and produces enough extra net income to justify the full cost. Another room on a floor plan is not automatically another rent payment, a higher valuation or a better investment.
The strongest appraisal asks two questions in order. Can the proposed layout and occupation properly work? If it can, does the additional income compensate for the work, delays, running costs and any loss of appeal elsewhere in the property? Use the calculator below to test that second question without skipping the first.
Start with the property people will actually live in
Look beyond whether a bed fits. Think about light, ventilation, access, privacy, storage, shared facilities and the circulation between rooms. Consider the needs of the likely occupiers rather than designing solely around the largest advertised rent total.
Turning a living room into a bedroom removes something as well as adding something. A family or group may value the shared space enough that the revised property becomes less attractive. A nominally larger bedroom count can therefore produce a smaller uplift than expected, or none at all.
Draw both layouts and ask experienced local agents to assess them. Request evidence from comparable completed lettings where available, not just ambitious advertised rents. Explain the actual sizes and remaining shared space so the comparison is meaningful.
Check permissions and standards before counting the rent
The proposed change may require assessment under planning, building regulations, licensing and other rules. The answer depends on the building, jurisdiction, work and occupation. The government's building regulations guidance is a starting point for England and Wales, not a design approval for an individual room.
If the change increases occupation by separate households, investigate the HMO position. An additional room and an additional permitted occupier are not the same thing. Read the HMO planning and Article 4 guide and ask the council and suitable advisers about the specific proposal.
Check title or lease restrictions, lender terms and insurance as well. Approval under one system does not settle the others. Keep the evidence alongside the floor plan before commissioning work or advertising the extra accommodation.
Compare two complete rental products
Write a short description of the property before and after the change. Include target occupants, room sizes, shared space, bathrooms, furnishings, bills and management arrangement. This makes it harder to compare a basic existing let with an unrealistically perfect upgraded one.
Then create a full income and cost schedule for each option. If the new strategy involves different tenants or room-by-room letting, the operating costs may change materially. Utilities, management, turnover, cleaning, compliance and maintenance deserve explicit consideration.
The useful measure is incremental net cashflow: the additional rent actually expected, minus the additional ongoing costs. It is not the total rent of the new bedroom if adding it reduces rent elsewhere or changes how the whole property is let.
Annual net uplift after £50 monthly added costs
Make the example your own
Does the extra bedroom repay the project cost?
Compare additional rent with additional operating costs. Enter the complete incremental project spend without double counting downtime.
No tax, financing costs, replacement work, discounting or capital-value change. Non-positive net uplift has no finite rental payback. Legal occupancy, technical suitability and rent evidence must be checked separately. Illustrative only. Inputs stay in this page and are not saved or sent.
This is a simple, undiscounted payback model using your entered uplift and costs. It does not establish lawful occupancy, forecast capital value or calculate tax. A non-positive monthly uplift has no finite payback from rental income in this model.
A worked example: £200 extra rent is not £200 extra profit
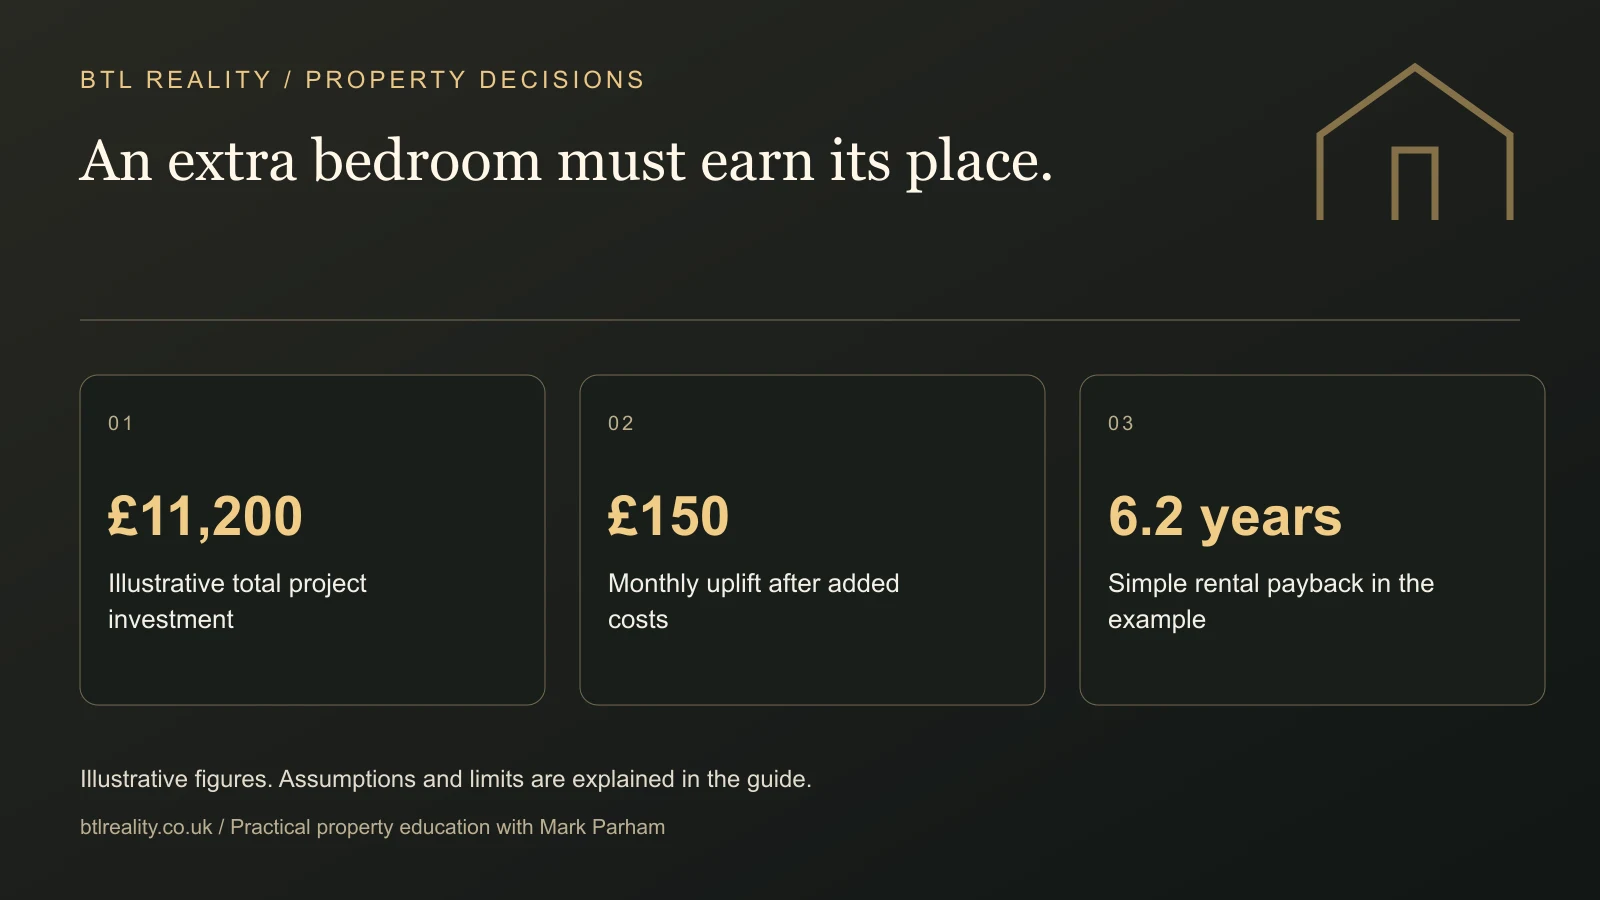
Assume a proposed alteration costs £8,000. Add £2,000 for professional fees and contingency, plus £1,200 of incremental holding or lost-net-income costs during the work. The total modelled investment is £11,200.
Suppose the revised property achieves £200 more monthly rent but adds £50 of monthly operating costs. The net uplift is £150 a month, or £1,800 a year. Dividing £11,200 by £1,800 gives a simple payback period of approximately 6.2 years.
That calculation assumes the uplift continues without change and excludes tax, borrowing costs on the works, later replacements and the time value of money. It is an initial comparison, not a guaranteed return. Make sure the holding-cost entry does not count the same lost income or bills twice.
Test the lower-rent case before approving the work
If the extra achievable rent is only £100 a month while additional costs stay at £50, the net uplift is £50 monthly, or £600 annually. The same £11,200 investment then takes approximately 18.7 years to recover through that uplift alone.
If extra rent equals extra operating costs, there is no rental surplus available to repay the initial investment. A claim that the room “pays for itself” would need another clearly evidenced basis, such as a realistic sale-value effect, rather than an income calculation producing zero.
Use the sliders and inputs to test several cases. Small changes in rent can have a large effect when the net margin is thin. A project with a comfortable payback only at the highest estimate deserves more investigation before spending begins.
Include the work that does not appear in the first quote
Ask for a specification covering the complete proposal. Depending on the project, this may involve design, structural input, electrical changes, heating, ventilation, doors, finishes, inspections and making good. A price for building a partition may be only one part of the job.
Plan the sequence and access. Work in an occupied property raises different practical and legal issues from work during a genuine vacant period. Do not assume that a tenant can simply be moved around or required to tolerate any proposed programme without proper arrangements.
Keep contingency separate enough to see it. If the entire budget is consumed by the first quote, you have no allowance for discoveries, changes or delay. The rental flooring payback guide also shows why durability and replacement frequency matter alongside the initial installation price.
Do not assume an immediate valuation uplift
An extra bedroom may influence value, but the effect depends on location, overall size, quality, layout and comparable evidence. A cramped additional room may not produce the same value as a genuinely larger house with suitable shared space.
Ask a surveyor or relevant valuation professional about the appropriate evidence. If you plan to refinance, the lender's accepted valuation and criteria determine borrowing, not the figure that makes the refurbishment spreadsheet look best.
Keep rental payback and capital-value assumptions separate. You can consider both in an overall appraisal, but neither should be presented as certain. If the rental case is weak and the whole project depends on an unverified valuation increase, make that dependency explicit.
Check whether a simpler improvement wins
Before changing the layout, compare other ways to improve the existing property's appeal and performance. Necessary repairs, better presentation, more durable finishes or a more effective letting process may offer a different balance of cost and disruption.
Use the same method for each option: upfront spending, expected net income effect, durability, downtime and uncertainty. Do not give the bedroom proposal a detailed upside forecast while dismissing the alternatives without evidence.
Sometimes the best decision is to retain a good layout and price the property realistically. The goal is a stronger rental business and a suitable home, not the largest possible number on the bedroom field of an advert.
Put the final decision into the whole-deal model
The bedroom appraisal is only one part of the investment. Add the chosen work and its realistic cashflow effect to the buy-to-let deal calculator, alongside purchase costs, mortgage, management, maintenance and voids.
Check the cash remaining after completion and works. A worthwhile long-term improvement may still be poorly timed if it leaves no reserve for repairs or a slower letting period. Consider whether staging permitted work or waiting for a suitable vacancy better fits the finances and tenant arrangements.
For a broader comparison of income and equity, use the property portfolio calculator. Keep growth and refinancing scenarios distinct from the actual extra rent expected from the alteration.
Turn the numbers into an action plan
A practical decision file contains both layouts, professional checks, local rent evidence, a complete quote, a contingency, the planned timetable and at least one downside case. Note which assumptions are confirmed and which remain estimates.
Set a clear decision rule before becoming committed. For example, you might require acceptable permissions, a funded works budget and a satisfactory return under the lower-rent case. Your threshold depends on your circumstances; the point is to avoid moving it every time another cost appears.
Starter Club can help you work through the wider property strategy and appraisal questions. The calculators are free to use without joining, and the legal and technical suitability of alterations should be established with the relevant professionals.
Frequently asked questions
Can I turn a living room into a rental bedroom?
Possibly, but first check whether the proposed room, layout and occupation meet the relevant requirements and permissions. Consider the loss of shared space and its effect on demand. A room that physically accommodates a bed is not automatically suitable or lawful to advertise as an additional rental bedroom.
Does another bedroom automatically mean another permitted occupant?
No. Occupancy can be affected by licensing, room and amenity standards, planning use and other requirements. Have the actual arrangement assessed before including additional rent in your forecast. Also distinguish a property's marketing description from the occupation that is authorised and appropriate for the completed accommodation.
Could the change create an HMO?
It could, depending on how the property is occupied and the applicable rules. The number of bedrooms alone does not settle the question. Explain the proposed households, shared facilities and occupation to the relevant advisers and council, then check licensing and planning separately before changing the letting strategy.
How do I estimate the extra achievable rent?
Compare the whole property before and after, using relevant local evidence and informed agent feedback. Account for any loss of shared space or changes in bills and management. Use a range rather than the highest advertised comparison, and test whether the lower estimate still justifies the spending.
What if the extra room reduces the property's overall appeal?
The income uplift may be smaller than expected, and vacancies or tenant turnover could offset it. Consider the needs of the likely occupants and test both layouts with local letting professionals. Retaining a well-proportioned home can be a better investment decision than maximising bedroom count at the expense of usability.
How should I calculate payback after all extra costs?
Add the incremental works, professional costs, contingency and correctly measured downtime costs. Divide that amount by the annual net rental uplift after extra ongoing expenses. If the uplift is zero or negative, there is no finite rental payback. Keep tax, financing and any assumed sale-value benefit separate unless explicitly modelled.
Put the next step into practice
Use the free tools to test your numbers, then choose the level of support that fits your next decision.