Which SIC Code Does a Buy-to-Let Property Company Need?
October 20, 2026
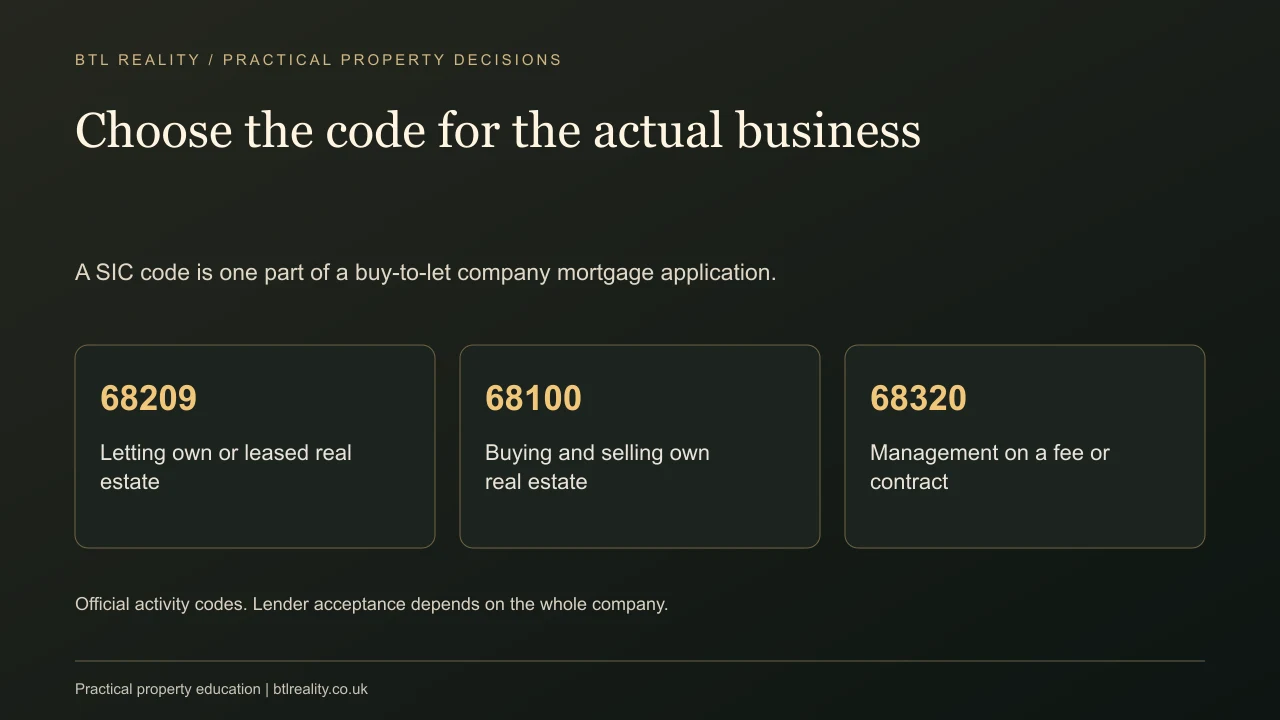
For a company buying and letting its own rental property, SIC code 68209 is a common starting point. But the right classification must describe what the company actually does, and a mortgage lender may impose its own accepted-code and company-structure requirements.
Adding a property code does not turn an unsuitable company into an acceptable mortgage borrower. It does not move a personally owned house into the company, create tax relief or establish that a trading company is a property SPV. Treat classification, ownership and finance as connected tasks with different purposes.
What is a SIC code?
SIC stands for Standard Industrial Classification. Companies House uses codes to describe a company’s business activity. Its official condensed code list is the place to check the wording, rather than copying a number from an unrelated company.
The relevant property entries distinguish selling your own property, letting property and providing property-management services for a fee. Codes 68100, 68209 and 68320 relate to those different activities. Read the official wording in the linked list before choosing.
A company holding and renting its own houses should consider the actual letting activity, rather than choosing a management code simply because its director manages the properties. Managing somebody else’s property for a fee is not the same business as collecting rent on the company’s own investment.
Which code fits the intended business?
| Code | Activity in plain English | Question to resolve |
|---|---|---|
| 68100 | Buying and selling the company’s property | Is the company trading in property rather than simply holding rentals? |
| 68209 | Renting out the company’s own or leased property | Is this the company’s actual rental activity? |
| 68320 | Providing property management for a fee | Is it managing property for others for a fee? |
Discuss a mixed business with the accountant. A company might carry out more than one activity, but that does not mean every buy-to-let lender will accept it. The practical aim is an accurate register and a structure suitable for the finance you intend to use.
Do not select codes solely because a lender accepts them. A classification should be truthful. If the planned activity and the proposed finance do not fit, the solution is to review the business structure or lender, not disguise the activity.
What does SPV mean in mortgage lending?
SPV means special purpose vehicle. In this context, a lender uses the term for a company established for a defined property purpose, within its criteria. It is still a company with directors, ownership records, accounts and obligations.
Checked on 19 October 2026, The Mortgage Works’ limited-company criteria accept specified SPV codes including 68100, 68201, 68209 and 68320. They also restrict company structures and activities, require a private limited company and exclude certain layered ownership arrangements. Accepted code numbers are only part of the policy.
Another lender may have a narrower list or a different view of mixed trading. Ask your broker to check the whole policy before incorporating or changing a company for a purchase. A general article cannot establish which lender will accept your particular shareholders and business.
Why an existing trading company can be different
Suppose a consultancy company has accumulated profits and its owner wants to buy a rental. Adding 68209 may record a new activity, but the company’s consultancy contracts, trading history, assets and liabilities do not disappear. It may still fall outside a lender’s SPV definition.
The distinction matters because the mortgage is made to the legal company, not just to the property code. Underwriting may examine the business, directors, shareholders, funding and guarantees. The lender wants to understand what else can affect that borrower.
For the broader choice, read buying property through an existing limited company. Keep this SIC-code question focused on accurate classification and application consistency, rather than treating it as an incorporation or tax recommendation.
Check the company records before applying
Read the company’s current Companies House entry. Check its exact legal name, registration number, status, officers, persons with significant control, share information and business codes. Compare those details with the mortgage application and the solicitor’s instructions.
A company name can be very similar to another company’s name. Use the registration number to identify the borrower. Also distinguish a registered-office address from a property address or a director’s home. Inconsistent details can create avoidable questions even where the underlying transaction is straightforward.
The Mortgage Works specifically describes Companies House validation in its application process. That is a useful reminder to resolve genuine discrepancies before submitting an application. Ask the adviser what records the proposed lender needs and how recent changes are handled.
How do you change a SIC code?
Companies House’s guidance on keeping SIC codes accurate directs companies to update codes by filing a confirmation statement. The CS01 page also provides the relevant SIC-change form and online filing route.
Before filing, confirm the intended activity with the company’s accountant or adviser. If the company already has borrowing, check whether a proposed change also needs the lender’s consent. A Companies House filing is not itself mortgage permission.
Save the submitted statement and evidence that the register has updated. Ask the broker when the lender’s systems can recognise the change. Do not time a binding purchase commitment around an assumption that every database updates immediately.
A company-setup delay has a cash cost
Consider a planned purchase where a structural or record mismatch delays completion by three weeks. Assume the buyer genuinely incurs £120 a week of additional storage or temporary accommodation and £75 a week of other transaction-related carrying costs. Those illustrative amounts total £195 a week.
Over three weeks that is £585. If an additional £250 of professional work is needed, the total becomes £835. These are not standard SIC-change fees and not inevitable costs. They show why resolving the company setup before a purchase becomes time-critical can matter.
Use the buy-to-let deal calculator for the purchase and include genuine professional costs in your cash budget. Avoid entering an arbitrary “company setup” allowance without asking what work the accountant, broker and solicitor each provide.
Keep funding records separate from the code
If the director provides the deposit, record how that money enters the company. A director’s loan, share subscription and funds from another company are different arrangements. The lender may have restrictions and need an audit trail, regardless of the SIC code.
The director’s-loan guide explains the distinction between company money and money lent by a director. Give the accountant and broker the same description of the funds so that the accounts and mortgage application agree.
Similarly, personal guarantees do not follow from the code alone. They arise from the lender’s legal requirements. Read the company mortgage guarantee guide before assuming limited liability removes personal exposure.
Keep the descriptions consistent
Describe the same business consistently to the accountant, broker, insurer and solicitor. If you intend to hold long-term rentals, do not describe the company as a property trader in one document and a letting business in another merely because a form offers a convenient option.
Where the strategy changes later, review the records and finance terms again. Starting to develop and sell properties, manage for third parties or add another company as a shareholder can change the business the lender originally assessed. Updating the register accurately and obtaining any required consent are separate parts of keeping that change properly documented.
A useful order of work
First describe the proposed activity and ownership structure in plain English. Then ask the accountant about company and tax implications and ask the broker which lenders can consider that structure. Once the route is coherent, establish or amend the records accurately and prepare the source-of-funds evidence.
Finally, have the solicitor confirm the legal borrower and purchase documentation match. This order is usually more useful than incorporating quickly with a familiar code and discovering later that a shareholder, existing trade or funding arrangement rules out the intended mortgage.
Questions about property-company SIC codes
Is 68209 the SIC code for a buy-to-let company?
It describes other letting and operating of own or leased real estate, so it commonly fits a rental-property business. Choose codes that accurately describe the actual activity and check the intended lender’s accepted-company criteria.
Should I use 68100 or 68209?
68100 describes buying and selling own real estate; 68209 describes the relevant letting activity. The right classification depends on the business. An accountant can help with mixed activities, while the broker checks financing implications.
Does adding a property code turn my trading company into an SPV?
No. The company’s existing activities and liabilities remain relevant. A lender assesses its own SPV definition and company structure, rather than treating a code change as proof that all other activity has disappeared.
Can I change my company’s SIC code?
Companies House provides a confirmation-statement route for updating codes. Check the accurate replacement or additional activity first, and consider any existing lender-consent requirements before making a change.
Does the correct SIC code guarantee a company mortgage?
No. The lender still assesses the property, rental income, directors, shareholders, credit position, deposit source and other criteria. Correct classification is one part of a consistent application.
Does changing the code transfer my personal property into the company?
No. A code describes business activity. Moving a personally owned property into a company is a separate legal and tax transaction, with financing and transaction-cost consequences that need their own assessment.