Is Rent Guarantee Insurance Worth It for a Landlord?
October 14, 2026
Rent guarantee insurance can be useful when it transfers a risk you cannot comfortably carry, on terms that fit your tenancy and management process. Its value depends on the cover, limits, exclusions and claims requirements, not just the premium or the word “guarantee”. You still need cash to run the property while a problem is being resolved.
The practical question is: if the tenant stops paying tomorrow, what costs continue, what would the policy actually cover and when might money reach you? That turns an abstract insurance decision into a comparison of exposure, available reserves and the protection being offered.
This guide provides a way to assess that decision. It does not rank providers, recommend an insurance product or estimate the probability of a claim. All policy details must come from the current wording and your insurer or insurance adviser.
Be clear about the type of protection
Rent protection insurance, a tenant guarantor and a guaranteed-rent management agreement are different arrangements. An insurance policy pays for covered losses under its terms. A guarantor's obligation depends on the guarantee. A management company promising rent creates a contractual commitment from that business.
Those differences matter when something goes wrong. You need to know who owes what, which conditions apply, what evidence is required and what happens if the organisation involved cannot perform. Similar marketing language does not make the arrangements interchangeable.
The NRLA's comparison of guarantors and rent protection highlights limits and conditions that can apply to insurance. Read the actual policy you are considering rather than assuming every product provides the same period or amount of cover.
Start with the loss you are trying to manage
List the costs that continue during unpaid rent: mortgage payments, service charges where relevant, insurance, essential repairs and other commitments. Some management costs may vary with collected rent, while others continue. Use your own contract rather than assuming every expense disappears when the rent stops.
Then distinguish cash outflow from lost income. If rent is £1,000 and continuing costs are £700, three months of non-payment means £3,000 rent not received and £2,100 of continuing costs to fund. Those figures answer different questions. You should not add them together and call £5,100 the same cash loss.
Before the problem, the simplified model would have produced £900 surplus over those three months. During non-payment, it requires £2,100 from reserves. The difference is the £3,000 missing rent. Keeping that relationship clear prevents double-counting in the investment forecast.
Test whether the reserve can bridge a claim
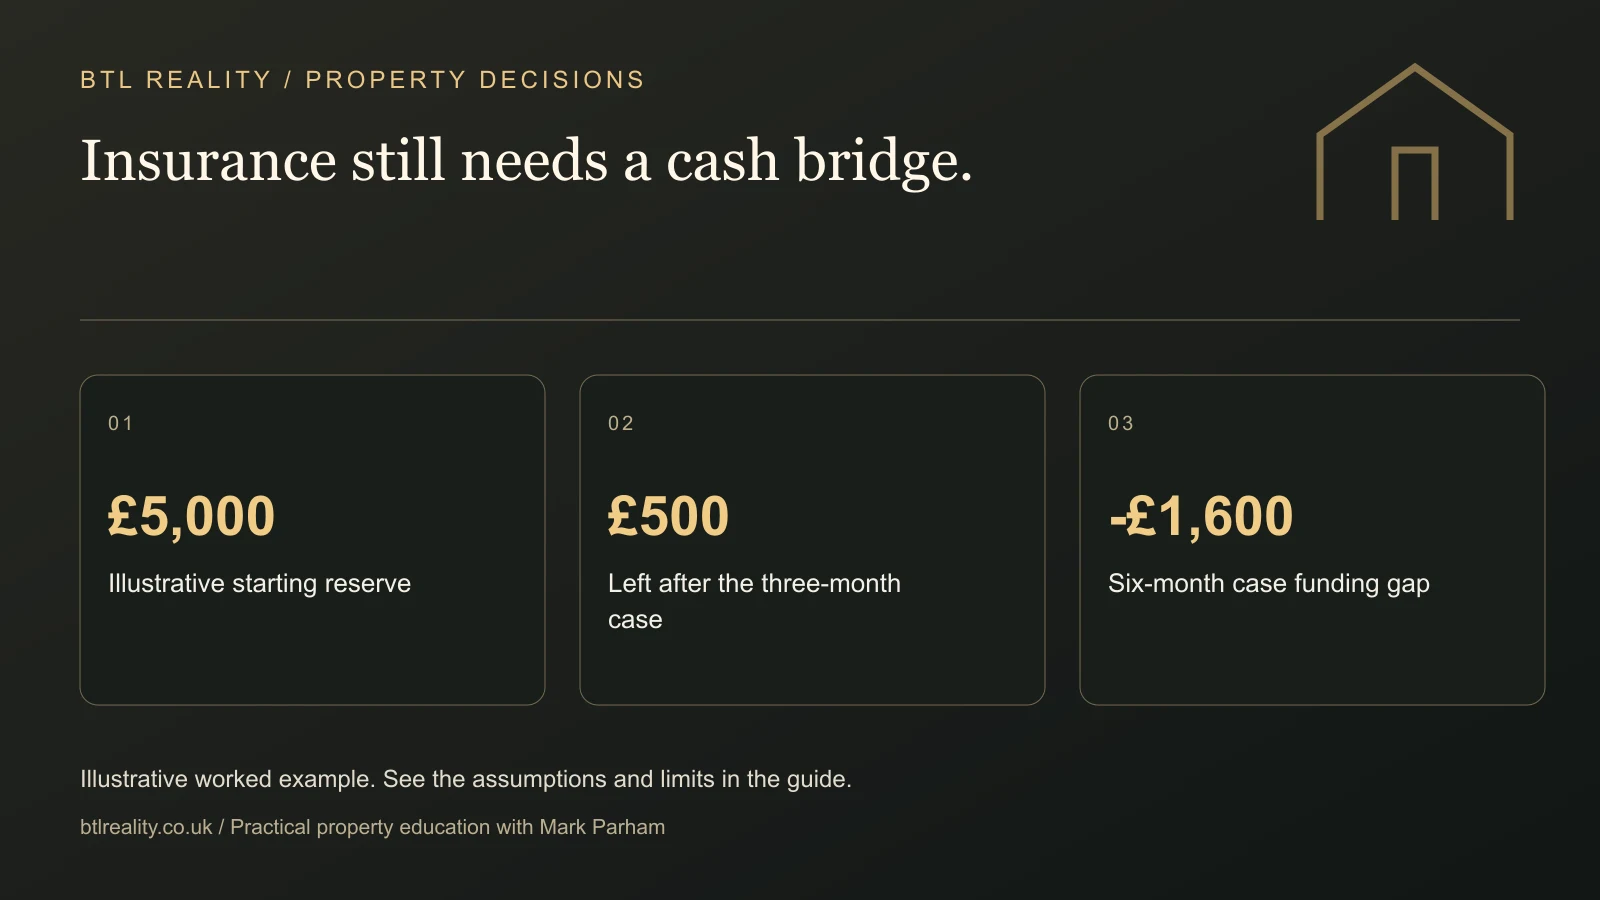
Assume £5,000 cash is reserved for the property. Continuing costs are £700 monthly, an unexpected repair costs £2,000 and the illustrative annual insurance premium is £400. With three months of no rent and no claim money received during that period, £500 remains.
At six months, the same model needs £6,600 in total, leaving a £1,600 funding shortfall. This says nothing about whether an insurer would accept a claim or how long any legal process takes. It simply tests whether the owner can meet the bills before relying on an uncertain future payment.
That is why insurance and liquidity solve related but different problems. A policy may compensate a covered loss while still leaving a timing gap. A reserve helps pay today's bill. Neither should be treated as proof that the property cannot produce an uncomfortable surprise.
Cash required before any insurance payment
Make the example your own
Could your reserve bridge unpaid rent?
Assume no rent or insurance receipts arrive during this period. Enter the costs you still need to pay.
Illustrative premium, not a quote. This tests liquidity without predicting claim acceptance, benefit size or payment date. Do not add lost gross rent to continuing costs and count it twice. Illustrative only. Inputs stay in this page and are not saved or sent.
Use the buy-to-let deal calculator to include the actual quoted premium and a suitable operating reserve in the initial appraisal. The £400 above is a hypothetical input, not a market quote or suggested price.
Read the definition of the insured event
Ask exactly what causes the cover to respond. Does it apply to unpaid contractual rent? Must specified tenant checks have been completed? Are pre-existing arrears excluded? Does cover depend on the tenancy type, property use or management arrangements?
Do not assume buildings insurance includes protection against unpaid rent. Similarly, a policy's cover for loss of rent following insured physical damage may be different from cover for a tenant who remains in occupation but does not pay. Ask the insurer to explain the distinction using your intended tenancy.
Keep the schedule, policy wording and any written answers together. A short product summary is useful for comparison, but it may not contain the conditions that decide a claim. If the wording remains unclear, resolve that before purchasing rather than relying on an informal interpretation later.
Compare limits, excesses and waiting periods separately
A monthly benefit limit, maximum claim duration and overall monetary cap can each restrict the payment. An excess may leave part of the loss with you. A waiting period can affect when cover begins or when a claim responds. Products use these concepts differently, so ask for a worked example based on the wording.
For example, ask the provider to explain a tenant missing three monthly payments, then six, at your actual rent. Ask what happens if the tenant leaves, the property remains empty, or a legal process is delayed. You are looking for the payment conditions and stopping points, not a headline promise.
The NRLA's current insurance product information illustrates how one offering sets out specific terms. Use such information to understand what to compare, not as a substitute for your own quotation or a claim that those terms apply throughout the market.
Make tenant checks fit the policy
Find out which referencing and affordability evidence the insurer requires and who is responsible for obtaining it. If a letting agent manages the process, confirm the policy requirements are included in their instructions. An agent's normal package and an insurer's conditions may not be identical.
Keep the relevant reports, agreement, rent records and other required documents securely. If the insurer needs evidence later, “the agent probably checked” is not a useful record. Equally, avoid collecting unnecessary personal data simply because it might conceivably be useful; use an appropriate, lawful tenancy process.
Ask what happens when tenants change, a guarantor is added, the rent changes or the tenancy arrangement is varied. Cover should be reviewed when the underlying facts change. Do not assume a policy bought for the original situation automatically follows every later change.
Understand the arrears and claims process
Ask when you must notify the insurer of a missed payment and which actions require its consent. The policy may set conditions about correspondence, legal representatives or how recovery is handled. Following a personal improvisation can create problems even when the original event would otherwise be covered.
A practical management file should record rent due, rent received, contact with the tenant and the dates of any notifications. Communicate respectfully and follow the applicable tenancy law. Insurance does not authorise shortcuts around a tenant's rights or allow the owner to take possession informally.
Where legal expenses cover is included, understand its scope and who appoints or approves the lawyer. Ask about exclusions, limits and the relationship with the rent-protection element. A policy containing two benefits does not necessarily mean both respond in every situation.
Compare the premium with the whole investment
Suppose the property would otherwise leave £250 monthly before tax and exceptional costs. That is £3,000 annually. An illustrative £400 premium reduces that to £2,600, before considering any other changes. You are paying a known cost for specified protection against uncertain events.
Do not decide solely by dividing the premium by the monthly rent. Also consider the reserve, mortgage commitments, how concentrated your income is in this property and how you would cope with a prolonged problem. A buyer relying on one rental for household bills faces different consequences from someone with substantial unrelated income.
You cannot calculate a reliable expected insurance profit without credible claim probabilities and the exact coverage. Avoid invented probabilities designed to make the policy look obviously good or bad. Compare the consequences you can carry with those you want to transfer, then obtain suitable advice on the available products.
Insurance does not replace a well-run rental
A property still needs realistic rent, timely repairs, clear records and competent management. Insurance cannot turn an overpriced purchase or an inadequate cash reserve into a strong investment. It may help manage a particular risk within an otherwise sound plan.
The rental yield calculator helps compare income with operating costs. Put the actual premium in the costs and keep a separate stress case for unpaid rent. That makes the ongoing price of protection visible without assuming a claim will occur.
Review the cover when renewing, refinancing or changing how the property is let. Read renewal changes rather than only the price. A cheaper premium is less attractive if the revised terms no longer match the risk you intended to insure.
Decide with a short written comparison
For each option, record annual cost, insured events, maximum benefits, exclusions, evidence requirements, claim procedure and the cash buffer you still need. If one of those headings is blank, ask before choosing.
Starter Club can help you build a clearer property plan and understand the questions behind a rental budget. Insurance suitability belongs with an authorised provider or adviser. The outcome you want is understandable protection, an affordable premium and enough cash to keep managing the property while a problem is resolved.
If you are letting a former home, first check the consent-to-let and buy-to-let comparison. An insurance decision should fit the permitted use of the property and the actual finance arrangement.
Frequently asked questions
Does landlord buildings insurance cover unpaid rent?
Not necessarily. Buildings cover, loss of rent after insured damage and protection against tenant arrears can be different benefits. Check your schedule and wording, then ask the insurer to explain what applies. Do not infer arrears protection from the fact that the policy is described as landlord insurance.
Is rent guarantee insurance the same as a guaranteed-rent scheme?
No. Insurance responds under policy terms, while a guaranteed-rent arrangement depends on the relevant business's contract and ability to perform. Compare the actual obligations, exclusions and remedies. Similar wording in an advert does not make the two forms of protection equivalent.
What tenant referencing does the insurer require?
It depends on the policy. Ask before the tenancy begins and ensure the person handling referencing follows the requirements. Keep appropriate evidence securely and check what changes need reporting. An otherwise thorough letting process may still differ from the insurer's specific conditions.
Are there waiting periods or excesses?
There can be, alongside monthly limits, overall caps and maximum benefit periods. Read each separately because they affect different parts of a claim. Ask the provider to work through an example at your rent rather than assuming all policies use the same rules.
Does rent protection cover an empty property?
Ordinary vacancy between tenants is not automatically the same insured event as rent arrears. Some policies may provide limited related cover under specified conditions. Check the exact wording and do not budget on the assumption that every empty month will be reimbursed.
Can I replace my cash buffer with insurance?
That would leave a timing and coverage risk. Costs may be due before a claim is accepted or paid, and some events or amounts may be excluded. Model a period with no rent and no insurance receipts so you understand the cash needed to keep the property operating.
Put the next step into practice
Use the free tools to test your numbers, then choose the level of support that fits your next decision.