Do I Pay UK Tax on Rental Income If I Live in Dubai?
October 10, 2026
Yes, UK rental income can be subject to UK tax while you live in Dubai. Moving abroad does not make a UK property business automatically tax-free. The amount payable and the reporting process depend on your residence, ownership, allowable costs, other income and the applicable rules. Keep those questions separate from whether an agent deducts tax before paying you.
The practical objective is straightforward: know what needs reporting, put aside enough money, keep good records and avoid treating gross rent as personal spending cash. This guide explains the decisions and an illustrative cash reconciliation. It does not calculate an individual's tax bill or recommend an ownership structure.
Residence and property location are different questions
A UK property remains a UK income source even when its owner lives elsewhere. Your tax residence is assessed under the relevant rules, not simply by the country shown on a business card. Time spent in the UK, ties and the wider facts can matter, while company residence needs its own analysis.
Ask an adviser to confirm your position for the relevant tax year, including any treaty considerations. Do not assume “resident in Dubai” answers every UK tax question or that a UAE company has the same treatment as an individual owner. The ownership documents and actual circumstances need to match the analysis.
HMRC's guidance on UK rental income while abroad explains the UK reporting position and the Non-Resident Landlord Scheme. Use it as a starting point, then apply the rules to your circumstances with appropriate professional help.
Gross payment is not a tax exemption
The Non-Resident Landlord Scheme concerns how rent is paid and tax collected. Depending on the arrangement, an agent or tenant may have withholding obligations. HMRC can authorise rent to be paid without deduction, but that does not mean the income is exempt from UK tax or that reporting disappears.
This distinction matters for cash planning. Two landlords with similar properties may receive different amounts into their bank accounts during the year because collection arrangements differ. That does not by itself establish their final liabilities. Reconcile any tax already deducted with the eventual calculation rather than treating withholding as the whole answer.
Keep approval notices and withholding records with the property accounts. If you change agent or ownership, check what needs updating. Do not ask an agent to ignore the overseas position simply because the rent is paid into a UK bank account.
Trace rent through the property account
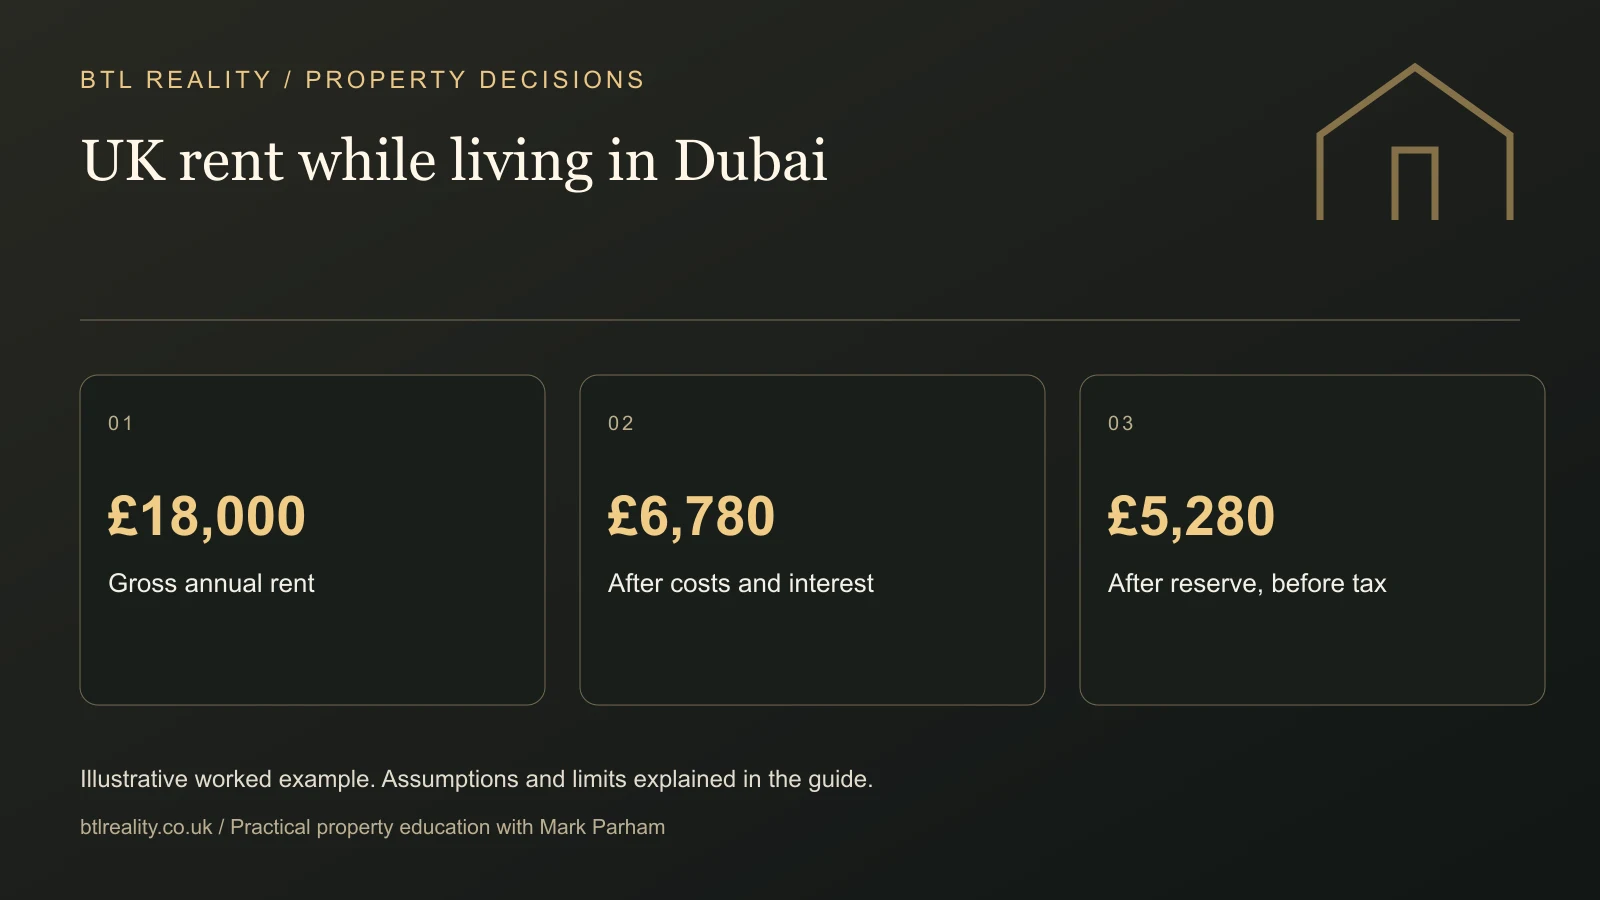
Consider an illustrative annual rent roll of £18,000. Assume management costs of £2,160, repairs of £1,200, insurance of £360 and mortgage interest of £7,500. The remaining cash before tax and other commitments is £6,780. That is £565 monthly on average, not the £1,500 monthly headline rent.
Now retain £1,500 as an additional future-work reserve. Cash potentially available before settling tax is £5,280, or £440 monthly. The reserve is a cash-planning decision, not automatically a deductible expense. Do not confuse moving money to a savings account with incurring a tax-allowable cost.
This example deliberately does not apply a personal tax rate. Its purpose is to show why the bank transfer, cash surplus and taxable profit can differ. Your accountant needs the underlying transactions, not just the amount you transferred to yourself.
Make the example your own
Rent, costs and cash kept aside
Keep the tax provision explicit. This tool does not calculate tax liability or allowable deductions.
Default tax provision is zero to avoid inventing a liability. Enter your adviser’s estimate before treating the remaining cash as available. Illustrative only. Inputs stay in this page and are not saved or sent.
Mortgage payments need careful classification
Interest and capital repayments are different. Repaying loan principal uses cash but is not the same as an operating expense. For individual residential landlords, the treatment of finance costs also differs from simply deducting all mortgage interest from rent in the way a basic cashflow spreadsheet might suggest.
HMRC's residential-landlord finance-cost guidance explains the basic-rate tax-reduction framework and its limits. Company ownership follows different rules. The lesson is to keep the cash model and tax calculation connected but separate, with the appropriate calculation for the actual owner.
Ask for mortgage statements that split interest, principal and fees. If borrowing has been used for several purposes, make the history clear. Do not assume every cost associated with a loan receives the same treatment or that a refinance automatically changes the tax position in the way you hope.
Repairs and improvements are not interchangeable
Keep itemised invoices and describe what was done. A routine repair, an improvement and work associated with acquiring a property may need different tax treatment. A £10,000 invoice labelled “refurb” provides less useful evidence than a breakdown showing individual tasks, dates and materials.
Photographs and a clear schedule can help your adviser understand the work, but they do not replace invoices. Record who paid, which property it concerned and whether any amount was reimbursed. Include letting-agent deductions rather than recording only the net rent transferred into your bank.
The rental yield calculator helps compare operating performance. It is not a tax return. Use its result as part of the investment picture and let the tax calculation reflect the correct classifications and your circumstances.
Do not assume you lose or keep every allowance
Entitlement to a UK Personal Allowance while non-resident depends on the applicable conditions, including nationality or treaty provisions in relevant cases. It should not be assumed either to disappear automatically or to remain available in full regardless of income.
Read HMRC's non-resident Personal Allowance guidance and confirm the position with your adviser. Other UK income can affect the overall calculation. Looking at the rental property alone may miss factors that determine the final bill.
If a company owns the property, the company's tax and your personal position are separate questions. Money remaining in the company is not automatically personal spending money, and withdrawing it requires an appropriate route and records. Avoid choosing a structure solely from a headline tax-rate comparison.
Build a monthly record that makes filing easier
Keep a ledger for each property with gross rent, agent fees, repairs, insurance, finance and other costs, supported by statements and invoices. Add a separate column for cash retained as reserve and another for tax paid or withheld. That makes it easier to explain differences without reconstructing a year from memory.
Reconcile the ledger to both the agent statement and the bank account. If £1,000 rent becomes an £820 transfer, identify the £180 difference. It could be a fee, repair, withholding or timing adjustment, each with different implications. A net bank receipt alone does not tell the full story.
Agree the filing timetable and method with your accountant early. Overseas returns can require information or software beyond a simple domestic online workflow. Use the HMRC non-resident landlord information collection to locate the appropriate current forms and guidance rather than recycling an old checklist.
Set a reserve from your own calculation
Ask for an estimated liability based on the real ownership and income, then decide how much to retain from each month's receipts. Review that estimate when rent, costs, borrowing, residence or other income changes. A generic “save 20%” rule can be too high or too low and may use the wrong starting amount.
Separate tax cash from maintenance cash. Both may sit in the same bank account, but your records should show what is committed. If one pot is counted twice, a tax payment can unexpectedly consume the reserve intended for a boiler or an empty period.
When assessing a new purchase, carry the likely tax and reporting costs into the investment decision before making an offer. Done For You can help with sourcing against an agreed property brief; it does not replace individual cross-border tax advice. A sensible deal needs both the property and the ownership arrangements to work.
Frequently asked questions
Do I pay UK tax on rent if I am tax resident in Dubai?
UK property income can remain taxable in the UK despite overseas residence. The amount depends on the applicable rules and your wider position. Have an adviser assess the actual ownership, income, costs and residence for the tax year instead of assuming that living in a low-tax jurisdiction removes UK obligations.
Does receiving rent gross mean HMRC says no tax is due?
No. Gross-payment approval changes how rent is collected under the relevant arrangements; it is not a declaration that the income is tax-free. Keep the approval and reporting records, calculate the liability correctly and retain sufficient funds. Tax already withheld and the eventual amount payable also need to be reconciled.
Can I deduct my whole mortgage payment from rental income?
Do not treat the full payment as an ordinary expense. Capital repayment and interest are different, and residential finance-cost treatment depends on the owner and rules applying. Provide statements that separate the components. A cashflow calculation can deduct a payment for budgeting without that amount necessarily being deductible in the tax calculation.
Do overseas landlords need a separate account for UK rent?
A dedicated account can make records and cash management clearer, but account arrangements and lender requirements should be checked for your circumstances. The key is a complete audit trail of rent, costs, transfers and reserves. Using a UK account does not itself determine tax residence or remove overseas-landlord reporting duties.
Can a UK limited company make my rental income tax-free abroad?
No such conclusion follows from company ownership alone. Company profits, owner withdrawals, residence and cross-border rules require separate analysis. Compare the full costs, finance options and reporting obligations before choosing a structure. Moving a personally owned property into a company can itself have significant transaction and tax consequences.
What should I send my accountant as an overseas landlord?
Provide ownership details, residence information, gross rent records, agent statements, invoices, mortgage breakdowns and any withholding or approval notices. Include acquisitions, disposals and major works with their dates. Ask for a tailored checklist early so missing evidence can be obtained before the filing deadline rather than reconstructed afterwards.
Put the next step into practice
Use the free tools to test your numbers, then choose the level of support that fits your next decision.