Buying a Flat With Major Works Planned: Who Pays the Bill?
October 14, 2026
If you buy a leasehold flat with major works planned, do not assume the seller will pay simply because the project was discussed before you arrived. The lease, demands, timing and purchase contract need to be checked together. Your conveyancer should establish the exposure and negotiate any agreed protection before you become committed.
A flat advertised at £130,000 can be a very different investment if a £20,000 contribution to roof, lift or external works is approaching. The headline rental yield will not reveal that difference. You need to know what is planned, what your share might be, when payment could be required and how uncertain the estimate remains.
This guide focuses on leasehold flats in England and Wales. Do not apply the Section 20 framework as a universal rule across all UK property ownership systems.
What does a Section 20 notice mean?
Section 20 consultation is part of the process for certain works and long-term agreements where costs are recovered through service charges. For qualifying works, consultation is generally required where any leaseholder's contribution exceeds £250. The Leasehold Advisory Service explains the procedure and the separate rules applying to longer-term agreements.
The £250 figure is a consultation threshold, not a normal maximum bill. A properly recoverable contribution can be much higher. Equally, the existence of a notice does not prove every proposed charge is reasonable, correctly apportioned or recoverable under the lease.
Ask which stage the project has reached. An early notice describing possible works is different from a tendered contract with a current estimate and payment timetable. Neither should be mistaken for a guarantee that the final cost cannot change.
Establish who can be asked to pay
There are two related questions. First, what can the freeholder or managing body recover under the lease from the person responsible at the relevant time? Second, what have the buyer and seller agreed between themselves about the economic cost?
A statement from an estate agent that “the seller will cover it” is not enough. Your solicitor needs to establish the mechanism in the contract, including which works are covered, the amount or calculation, timing and what happens if costs change. The arrangement should work when the actual demand arrives, not just sound reassuring during negotiations.
The Leasehold Advisory Service's transaction guidance highlights later service-charge demands and the possible use of a retention. It also explains why missing or incorrect management information should be raised with the conveyancer. Obtain specific advice on your transaction rather than treating a general explanation as an allocation of your bill.
Request the building's financial story
Ask for recent service-charge accounts, current budgets, reserve-fund information, relevant notices, estimates, consultation correspondence and the planned maintenance programme. Your conveyancer will identify the appropriate management enquiries and supporting documents.
Look for consistency. If the seller says the roof was replaced recently but the management papers show another roof project, ask what each involved. If a reserve fund appears substantial, find out which buildings and works it must support. A large balance spread across several blocks may provide less protection for your flat than it initially suggests.
Also ask about arrears, disputes and incomplete projects. They can affect how work is funded and delivered. You do not need to become the building's surveyor or lawyer, but you do need enough evidence to understand the cash commitments attached to the flat you are buying.
Model the bill against income you actually keep
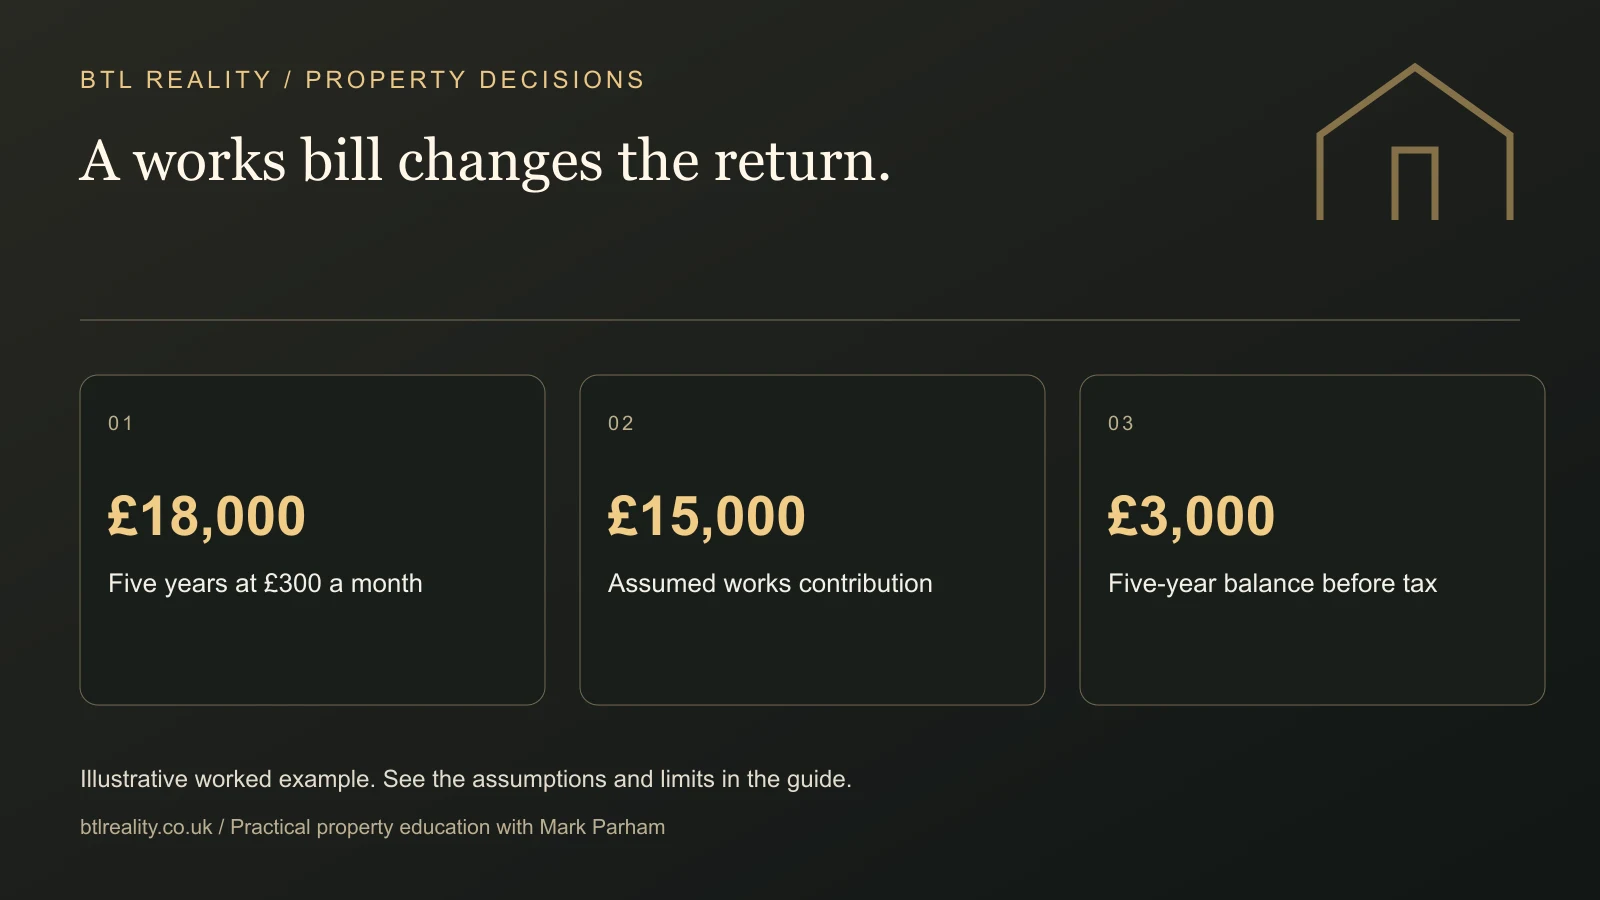
Suppose a rental is expected to leave £300 a month after ordinary operating costs and finance, before tax and exceptional work. That is £3,600 annually. Over five years, unchanged cashflow would total £18,000 before a major-works contribution.
A £5,000 contribution reduces that five-year figure to £13,000. A £15,000 contribution leaves £3,000. A £30,000 contribution produces a £12,000 deficit over the same period. These are simplified cash illustrations with no rent growth, tax or other shocks, but they make the scale visible.
The bill may be due near the start, not spread evenly across five years. Therefore a property can appear acceptable on a long-term average and still create an immediate funding problem. Model the payment date alongside the total amount. Expected future rent cannot pay a demand that arrives before the rent has been earned.
Five-year cashflow remaining after major works
Make the example your own
What does the works bill leave from five years of rent?
Use cashflow after ordinary costs and finance, before tax. The contribution may be payable upfront.
No tax, growth, inflation, voids or other exceptional work. The final contribution and liability need legal confirmation. Future rent cannot fund a bill due before it is earned. Illustrative only. Inputs stay in this page and are not saved or sent.
Use the buy-to-let deal calculator to rebuild the acquisition budget with any expected contribution and additional reserve. Keep major works separate from routine annual service charges so the same amount is not omitted or counted twice.
A price reduction and a retention do different jobs
A price reduction changes what you pay for the flat. A retention normally involves an agreed amount being held back under documented terms to deal with specified future liabilities. Neither is automatically sufficient; the detail matters.
With mortgage finance, a £10,000 price reduction may not leave you £10,000 more cash at completion. If borrowing is recalculated at 75% of the reduced price, a simple £10,000 reduction lowers the deposit by £2,500 and the loan by £7,500. You still need to fund the works contribution when it becomes due.
A retention raises different questions. Who holds it? What evidence releases it? What is the maximum amount? What happens if the bill arrives after the agreed period or exceeds the retained sum? Ask your solicitor to explain the protection and its limits in pounds and dates.
A reserve fund is helpful, but read the evidence
A well-funded maintenance plan can be a positive feature of a building. It may mean owners have been preparing for predictable expenditure instead of delaying everything until failure. A low annual service charge is not necessarily better if it reflects underfunding.
However, a reserve balance does not prove the whole upcoming bill is covered. Confirm the expected total works cost, the amount available for that project, how the lease apportions costs and whether other planned works compete for the same money.
For example, a building may hold £100,000 while several projects together are estimated at £250,000. The presence of a fund is useful information, but the £150,000 difference still needs an explanation. Do not divide balances equally between flats unless the actual lease allocation supports that calculation.
Check the effect on tenants and letting time
External works may involve scaffolding, noise, restricted access or disruption to shared areas. Ask the managing agent for the anticipated programme and have a local letting agent consider the likely effect on marketing and occupancy. Avoid assuming every project will cause a void, but do not assume it has no operational consequence either.
Keep any rent adjustment, additional management work or delay in your scenario model. A £15,000 contribution plus two months without expected £1,000 rent is different from a £15,000 bill alone. If modelling lost rent separately, avoid also deducting the same loss inside another cashflow assumption.
Building-safety work can involve additional legal protections and complex funding questions. Have your conveyancer assess those specifically. A generic major-works calculation should not be used to decide whether a particular leaseholder can legally be charged for remediation.
Do the works improve the investment case?
Necessary work can protect the building and support its long-term use. A properly planned roof replacement may be preferable to ongoing leaks and repeated emergency repairs. The existence of a project is therefore not an automatic reason to reject a flat.
The investment question is whether the total price, contribution, ongoing charges and risks make sense compared with alternatives. Ask what the works resolve and what they leave outstanding. A building can complete one large project while still needing another.
Do not assume a £15,000 contribution creates a £15,000 increase in your flat's market value. Some spending preserves existing value or restores expected condition. Treat any forecast uplift as a separate evidence-based assumption, not a refund of the money you paid.
Make a clear decision before exchange
Before committing, summarise the current estimate, your possible share, payment timing, remaining uncertainty and contractual arrangements with the seller. State how much cash remains afterwards. If a key answer is still missing, decide whether further investigation or different terms are needed.
BTL Reality's Done For You service sources properties against an agreed brief. For a flat, that brief should reflect tolerance for service charges, shared-building liabilities and immediate cash demands. Your conveyancer still determines the legal position, and relevant surveyors assess the physical works.
The attractive deal is the one whose complete costs you understand. A lower purchase price is useful only when it compensates adequately for the commitments that come with it.
Our valuation and survey comparison helps separate the lender’s checks from the condition investigations you may need as the buyer.
Frequently asked questions
What is a Section 20 notice when buying a flat?
It is part of consultation about qualifying works or agreements where costs may be recovered through service charges. Obtain the full papers and establish the stage reached. A notice is a prompt for detailed enquiries, not proof that your contribution is fixed or limited to £250.
Does a Section 20 notice tell me the final cost?
Not necessarily. Early consultation may describe proposed work before final tenders, scope and contributions are known. Ask for the latest estimate, assumptions, contingency and payment timetable. Keep a scenario for a higher contribution where the amount remains uncertain.
Does the seller or buyer pay for planned major works?
There is no safe universal answer based only on when the works were first mentioned. The lease, demands, timing and contract all matter. Your conveyancer should establish the position and document any agreed allocation or protection before you become bound to buy.
Can the purchase contract include a retention?
A solicitor may negotiate one where appropriate, but the seller must agree and the wording needs to address amount, scope, release conditions and timing. A retention can be insufficient if costs exceed it or arrive outside its terms. Understand the remaining exposure.
Can a reserve fund cover the whole bill?
Possibly, but only the building's actual finances and allocation support that conclusion. Check the amount available for this project and any other claims on the fund. A healthy-looking total balance is not automatically a personal credit allocated equally to each flat.
What should my solicitor ask the managing agent before exchange?
Ask about planned and completed works, notices, estimates, demands, accounts, reserves, arrears, disputes and the maintenance programme. Your solicitor should also check the lease's recovery and allocation provisions, and any specific building-safety issues. Make sure the latest answers reach your purchase budget.
Put the next step into practice
Use the free tools to test your numbers, then choose the level of support that fits your next decision.