Private Property Mentorship: What Does a Bespoke Strategy Include?
October 8, 2026
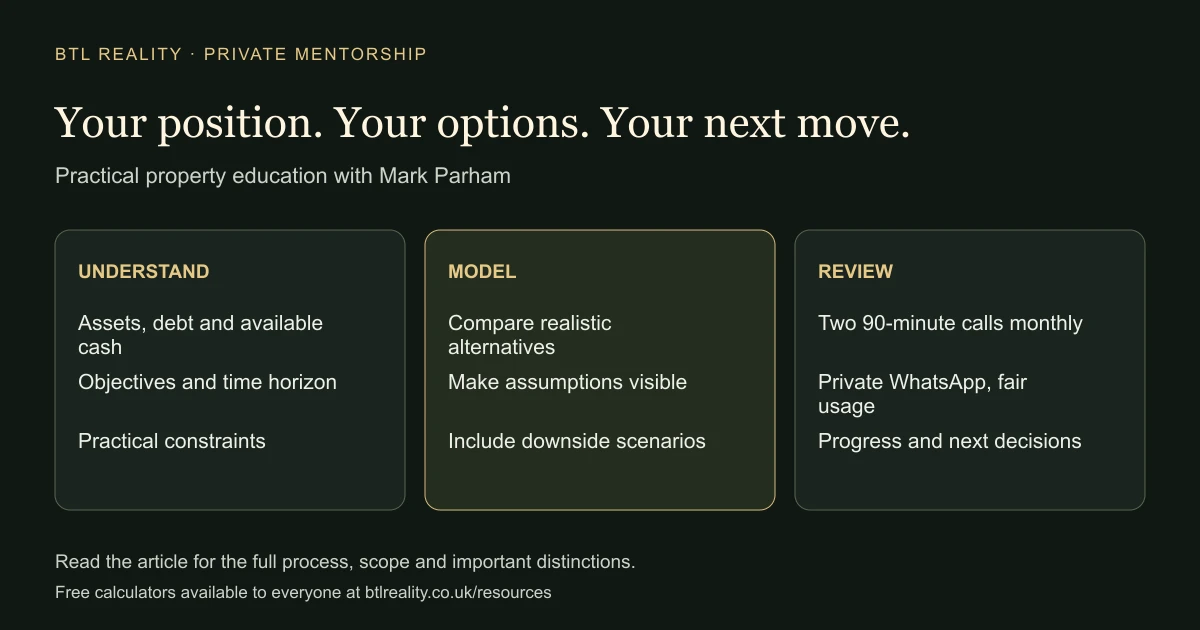
Private property mentorship should give you more than a longer version of a generic answer. Its value is the time spent understanding your position, examining the choices in front of you and building models that show what a plan depends on.
At BTL Reality, Private Mentorship is a twelve-month working relationship with me, Mark Parham. It includes two private 90-minute calls each month, private WhatsApp within fair usage, bespoke modelling and forecasting, and advanced strategy and planning.
This guide explains what that can look like in practice, how it differs from group support and who can apply. The examples are illustrative questions and frameworks, not a promise that a particular investment or financial outcome will follow.
When does a bespoke strategy become useful?
More complexity does not always mean more properties. You may have one property alongside cash, pensions, business commitments and a demanding career. Several plausible choices can compete for the same money and attention.
One option might create more rental income but tie up cash. Another might release capital through borrowing but increase interest costs and reduce monthly surplus. A third might involve doing nothing immediately while you improve reserves or gather evidence.
A generic “buy more property” answer cannot explain those trade-offs. A bespoke process starts with your actual objectives and constraints, then tests how the options behave under different assumptions.
The purpose is not to produce the most impressive-looking forecast. It is to make the decision clearer, including where the proposed plan is fragile or where the information is incomplete.
Start with a complete picture, not one headline number
Net worth, investable cash and income tell you different things. Someone can have substantial property equity and little readily available cash. Someone with a high salary may still have significant commitments or limited capacity to manage a project.
The starting picture needs to distinguish assets, liabilities, cash, ongoing income and foreseeable demands on those resources. Estimates may be useful initially, but their uncertainty should remain visible.
The free net worth calculator can help organise the information before applying. It does not provide a formal valuation or establish which investment is appropriate for you.
Then define what the plan needs to achieve. Current spendable income, long-term wealth, reduced management demands and preparation for a future life change can lead to different decisions. A useful strategy makes those priorities explicit rather than assuming growth is the only objective.
What bespoke modelling should show
A good model separates the inputs from the outputs. You should be able to see the assumptions about purchase prices, rents, finance, operating costs, works, reserves and timing rather than receiving only a final portfolio value.
It should also show the distinction between property value, debt, equity and usable cash. Releasing equity through refinancing creates borrowing; it does not turn the borrowed amount into profit.
For example, compare retaining a rental, improving it and selling it. Each route needs its own costs, timing and assumptions. A model that compares one route before tax and another after selected costs is not a fair comparison.
The aim is to understand which assumptions change the decision. If a modest increase in borrowing cost removes the expected surplus, that deserves attention before celebrating an optimistic long-term value.
Prepare your private strategy discussion
Tick the preparation steps you have completed. This is an organiser, not a readiness score or investment approval.
0 of 6 preparation steps completed
Your selections stay in this page and are not saved or sent.
Forecasts need alternatives, not just a central case
Forecasting can help you explore possibilities, but future growth, rents, costs and finance are uncertain. A single smooth line is easy to understand and easy to over-trust.
Useful scenarios might include slower progress, a period without rent, a larger repair, a lower refinance valuation or a purchase that takes longer than expected. The relevant stresses depend on the proposed plan.
The property portfolio calculator and refinance calculator offer free ways to explore some of these relationships. Bespoke modelling goes further by focusing the questions and assumptions on the position being discussed.
No model guarantees mortgage availability or investment returns. The purpose of seeing a downside is to decide what evidence, reserves or changes the plan might need, not to assume every risk can be calculated away.
How the calls and WhatsApp work together
The published Private Mentorship offer includes two private 90-minute calls each month. That gives dedicated time for discussing strategy, reviewing progress and working through more complex decisions.
The private WhatsApp conversation provides a way to raise questions between scheduled sessions within fair usage. It is not an emergency service, unlimited availability or a promise of instant replies at any hour.
A useful working rhythm is to identify the current decision, prepare the relevant information, discuss the alternatives and agree the next areas to investigate. Questions arising between calls can then connect to that work rather than becoming an unrelated stream of messages.
The exact matters discussed depend on your needs and the service scope. Private mentorship is not an instruction for me to operate your bank accounts, negotiate every transaction or replace the professionals required for a purchase.
Education and strategy still sit alongside professional advice
Mortgage suitability, tax treatment and legal documents require the appropriate professionals. A planning conversation can help identify the questions to ask, but it should not be presented as replacing those separate services.
For a property purchase, you may need a broker or lender, solicitor, surveyor and other specialists. Their instructions, fees and responsibilities are distinct from the mentoring relationship.
If a model depends on a particular tax treatment or financing assumption, that point needs confirmation from the relevant professional. It is better to mark it as unresolved than quietly let it drive a confident recommendation.
This distinction makes the strategy more useful. It connects the work without pretending that one person or one spreadsheet can provide every answer.
Who qualifies for Private Mentorship?
The application asks for all three financial figures, but you need to meet any one of the published thresholds:
- Personal net worth of £500,000 or more.
- Currently investable cash of £100,000 or more.
- Gross annual salary of £120,000 or more.
These are alternatives, not three requirements that must all be met. Complete every field honestly, including zero where appropriate, and use your current position rather than hoped-for future values.
The application describes investable cash as money currently available to invest, excluding emergency reserves and near-term commitments. It describes personal net worth as assets minus debts, including property equity and pensions. Salary is current annual salary before tax.
The figures are self-reported and used to assess the service’s entry criteria. Meeting a threshold does not mean a specific investment is suitable or that you should commit all available cash to property.
What happens after the application?
The Private Mentorship page asks about your experience, goals and current financial position. It explains how the details are stored in the customer system and used to process the request. Marketing consent is a separate optional choice.
If you meet the entry criteria, the published journey offers two options: book a free suitability call or proceed with direct online enrolment. You do not have to pay just because you submitted an application.
If you do not meet the criteria, that does not mean your property goals are unimportant. Starter Club and the free resources provide other ways to develop your understanding and plan your next step.
The price and direct-enrolment option
The standard price is £12,000 for twelve months. Applicants who qualify can choose direct online enrolment without the introductory call for £10,800 upfront, a 10% reduction for the same twelve months of support.
This is a single payment for the stated term, with no automatic renewal. Review the current service details and applicable terms before paying. A lower price is not a reason to skip questions you need answered about the format or scope.
If you are uncertain whether the service fits, use the suitability-call option. The direct route is there for someone who has read the details and is comfortable proceeding, not to imply that taking time to understand the offer is a mistake.
How this differs from Starter Club and sourcing
Starter Club provides a personal roadmap, monthly live group calls and the founding WhatsApp group arrangement. It is a group-support format at a different price and level of attention.
Private Mentorship provides private sessions and bespoke work for a more intensive relationship. It should be chosen because that additional depth addresses a real need, not simply because it is the most expensive option.
Done For You is property sourcing against an agreed brief. Private mentorship does not automatically include sourcing a property or every service involved in buying and letting one. Confirm any additional scope separately.
Prepare one decision before you apply
Write down the decision you would most like help exploring, the alternatives you currently see and the information you already have. Add the practical constraints that a model must respect.
That preparation makes your application more useful than a broad ambition without context. It also helps you decide whether you need private strategic work, a focused professional consultation, a sourced opportunity or more time using the free tools.
If the private format fits your needs and you meet an entry threshold, apply for Private Mentorship. The aim is a thoughtful plan you understand, with its assumptions and next steps made clear.
Frequently asked questions
Must I meet all three financial thresholds?
No. Meet any one of the net worth, investable cash or salary thresholds, but complete all three fields.
Is the £10,800 option an annual subscription?
No. It is the direct-enrolment upfront price for twelve months, without automatic renewal.
Does a bespoke forecast guarantee the result?
No. It explores assumptions and trade-offs. Markets, costs, finance and your circumstances can change.