Can I Use My Pension to Buy a Rental Property?
October 17, 2026
There are two very different questions behind using a pension to buy a rental property: can the pension itself own the property, and can you withdraw pension money personally and then invest it? Confusing those routes can lead to an expensive mistake. An ordinary residential buy-to-let is not a straightforward asset to place directly inside a SIPP, while a personal withdrawal has its own eligibility, tax and retirement consequences.
Before making either move, involve an appropriately qualified financial adviser and your pension provider. This guide helps you organise the comparison and the questions to ask. It is educational material, not a recommendation to transfer, withdraw or change pension investments.
Direct pension ownership is different from personal ownership
If a pension scheme buys an asset, the scheme owns it under the applicable pension rules. If you take a permitted withdrawal and buy personally, the money has left the pension and the property is subject to the rules applying to its new ownership.
The distinction changes tax, access, administration and the risks you carry. Calling a purchase “my pension property” does not establish which route has been used. Put the proposed owner, source of money and transaction steps on paper before discussing projected returns.
For investment-regulated pension schemes, HMRC's guidance on residential taxable property explains that acquiring taxable residential property can trigger substantial member and scheme tax charges. Ordinary houses and flats let to tenants should not be treated as an easy direct SIPP purchase. Specific exceptions and indirect structures require specialist assessment, not an assumption that a company or trust solves the issue.
Commercial property and property funds are separate routes
Some pensions can hold permitted commercial property, subject to the provider's rules and the transaction meeting the relevant requirements. That does not mean every property with a shop downstairs is wholly commercial for pension purposes. Mixed-use buildings and residential elements need careful analysis.
Property funds and other eligible investments can provide exposure to property without the pension directly owning your chosen rental house. Their risks differ from direct ownership: charges, diversification, liquidity, underlying assets and the ability to buy or sell all need review.
Do not choose a structure just because a label sounds tax-efficient. Ask the adviser and provider to explain exactly what is held, what can go wrong and how you access money later. A complex route that you cannot explain back in plain English deserves more investigation before any commitment.
What if you withdraw money and buy personally?
A permitted pension withdrawal may provide cash you can use for a property purchase, but the amount received is not necessarily the amount removed from the pension. Eligibility depends on your pension and circumstances, and taking benefits can affect tax and future pension contributions.
GOV.UK explains the tax-free treatment and limits for pension withdrawals. The rules are not a promise that an arbitrary withdrawal is wholly tax-free. The taxable element interacts with your other income and the way benefits are taken. Obtain an individual calculation before agreeing to a purchase that depends on a particular net amount.
Also distinguish taking money from an existing pension from transferring it. A transfer can involve giving up guarantees or other valuable benefits. That is a separate decision requiring appropriate advice, even if the eventual destination you have in mind is a familiar asset such as property.
Start with the net cash available
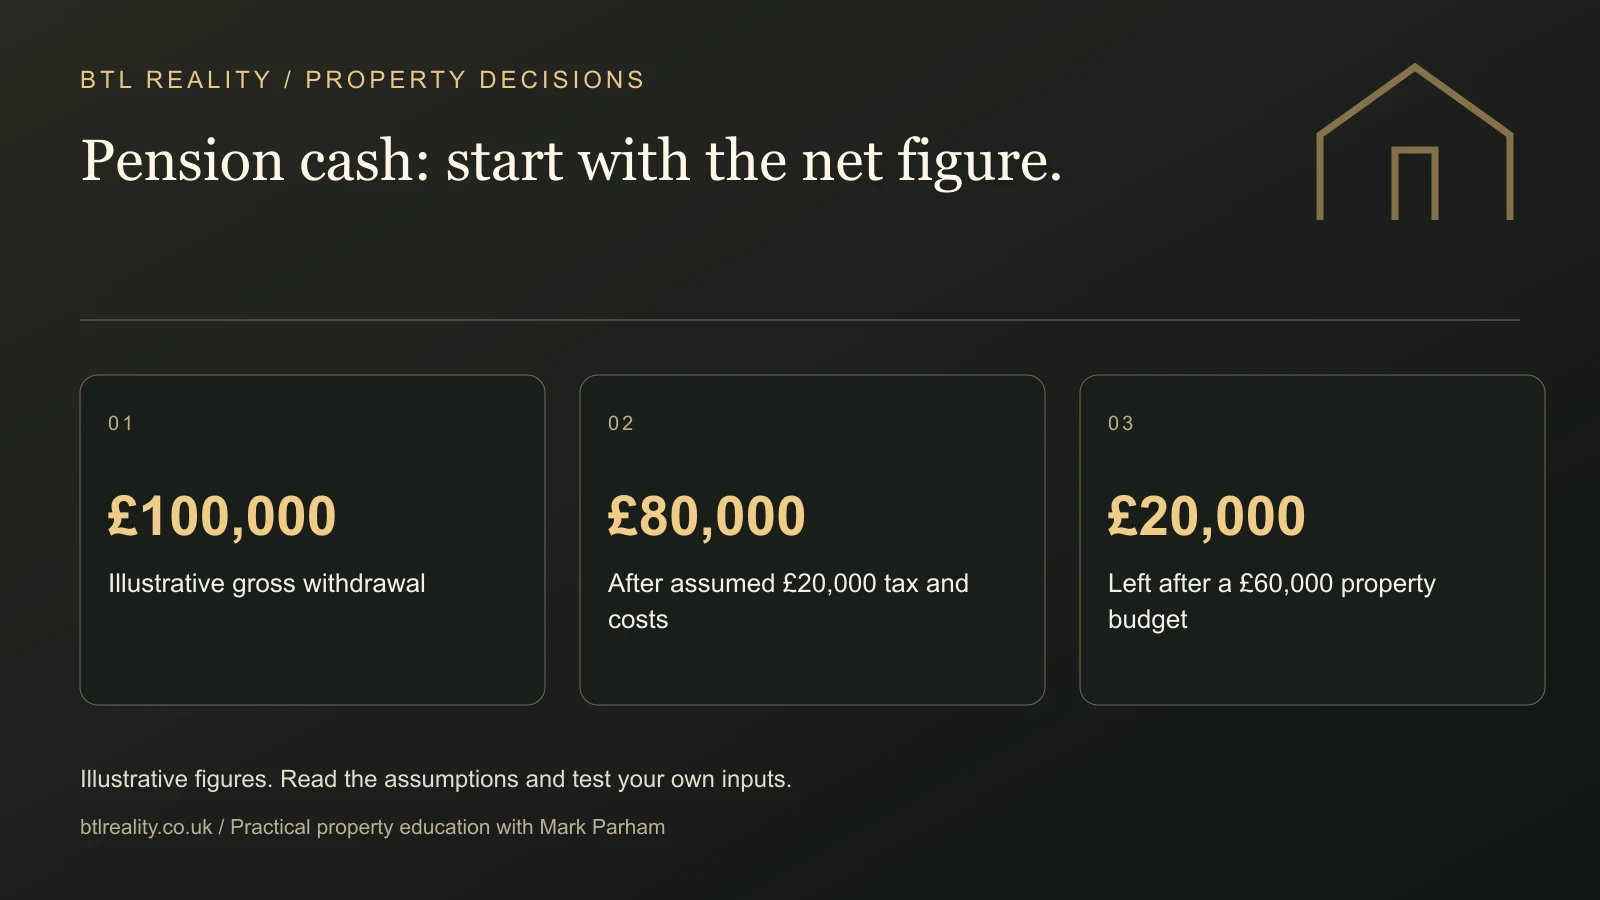
Suppose an illustrative withdrawal is £100,000 and your professional estimate of the associated tax and charges is £20,000. The available cash is £80,000, not £100,000. This is a modelling assumption, not a tax calculation or an estimate of what you personally would owe.
Now suppose your planned property purchase needs a £37,500 deposit, £12,500 for transaction costs and work, and a £10,000 reserve. The total is £60,000, leaving £20,000 from the assumed net withdrawal. That remaining money still has to fit your wider retirement and household plan.
If the tax and charges instead total £30,000, the net cash falls to £70,000 and the remaining amount to £10,000. A ten-thousand-pound difference in withdrawal proceeds can change your ability to absorb a void or repair. It is not a minor detail to resolve after the property offer is accepted.
Make the example your own
How much cash remains after the withdrawal and purchase?
Use tax and charge estimates provided for your own circumstances. No pension tax or eligibility is calculated here.
A negative final amount is a funding shortfall. This does not assess pension access, tax treatment, lost benefits or investment suitability. Keep retirement and household needs separate; seek qualified advice before withdrawing. Illustrative only. Inputs stay in this page and are not saved or sent.
The calculator uses an amount for tax and charges that you supply. It deliberately does not infer your pension entitlement, tax band or suitability from a few inputs. Use verified estimates and retain the assumptions with your plan.
Compare income on a consistent basis
A common mistake is comparing gross rent with a pension withdrawal after tax. A property advertising £12,000 annual rent does not provide £12,000 of spendable retirement income once finance, management, maintenance, voids, insurance and tax are considered.
For an illustrative rental producing £1,000 a month, deduct £500 finance costs and £250 operating costs. The result is £250 a month before personal tax and exceptional work. That is £3,000 a year on the £60,000 cash commitment in the example, or 5% before those remaining deductions.
This is not a forecast of property returns, and it does not include an assumed capital gain. A £5,000 repair could exceed a year's routine surplus. A £50 monthly increase in costs removes £600 a year, or one fifth of the initial £3,000 surplus.
Use the buy-to-let deal calculator to model the property separately. Then compare it with the pension options on the same after-cost, after-tax basis with an adviser. Avoid declaring a winner from two numbers measured differently.
Consider what becomes less flexible
A rental property cannot usually be sold in small monthly pieces. Accessing its value may involve refinancing or a sale, with costs, lending requirements and timing uncertainty. Money held for retirement expenditure needs a plan for being available when bills fall due.
Concentration also changes. Moving a substantial share of retirement assets into one building can expose you to one location, tenant market and maintenance history. You might know the property well, but familiarity does not remove the financial effect of a large repair or long vacancy.
Leverage adds another layer. A mortgage can increase exposure to the asset while reducing the initial deposit, but payments and eventual repayment remain obligations. If the strategy depends on borrowing throughout retirement, check the actual lender options rather than assuming today's product will always be available.
Model three timelines, not just the purchase day
First, model the transaction: withdrawal proceeds, tax, deposit, purchase costs and reserve. Second, model the next few years: reliable income, vacancies, maintenance, household withdrawals and mortgage changes. Third, model later life: management support, loan maturity, sale options and how the wider retirement fund behaves.
Keep an explicit allowance for the work of ownership. You may delegate management, but you still need oversight and cash for decisions. If circumstances change and you no longer want to manage property, the exit should not rely on ideal market conditions.
The free financial freedom calculator helps explore income targets and assumptions. Its scenarios are not retirement advice or guaranteed sustainable withdrawal levels. Use the results as questions for a professional discussion, particularly where debt-funded cash is included in a lifestyle plan.
Questions to take to an adviser
Ask what your pension currently provides, including guarantees, charges and beneficiary arrangements. Ask how the proposed withdrawal or transfer affects tax, future contributions, flexibility and the income you may need later. Request a comparison with leaving the pension in place and funding property another way, if that is feasible.
For the property, bring a complete appraisal rather than a headline yield. Include mortgage terms, likely operating costs, realistic rent evidence, reserves and an exit scenario. The adviser needs both sides of the comparison to evaluate the trade-off meaningfully.
MoneyHelper explains how to find a retirement or pension adviser. Check the person's permissions and the scope of the service, especially where a pension transfer or a specific investment recommendation is involved.
Use the tools without feeling pushed into a purchase
BTL Reality's free resources are available without joining Starter Club or buying a service. Use them to understand a potential rental and your wider objectives before deciding whether property is the appropriate next step.
The useful outcome may be buying, waiting, changing the funding route or leaving the pension untouched. The objective is a better retirement plan, not a property purchase at any cost. If the proposal only works by ignoring withdrawal tax, assuming uninterrupted rent or relying on an early refinance, those are issues to resolve before committing.
Frequently asked questions
Can a SIPP buy an ordinary residential buy-to-let?
An ordinary residential rental should not be treated as a straightforward direct SIPP investment. The taxable-property rules can impose substantial charges on relevant pension arrangements. Ask a specialist adviser and the scheme provider before pursuing any proposed structure, including one advertised as an indirect workaround.
Is commercial property treated the same as residential property?
No. Pension treatment can differ, and some schemes permit suitable commercial property. Mixed-use premises and residential accommodation need specific analysis. The provider's investment rules, costs and administration also matter. Do not assume that a building is wholly commercial simply because part of it is used by a business.
Can I use pension money after withdrawing it personally?
Once a permitted withdrawal has been made, the net proceeds may be available for a personal purchase. However, eligibility, taxation and the effect on retirement provision need checking first. The property is then outside the pension and has its own ownership, financing and tax consequences.
Could a large withdrawal create an unexpected tax bill?
Yes. The taxable portion and your other income can affect the overall liability, while the timing and method of taking benefits matter. Obtain a personalised estimate before relying on a gross withdrawal figure to fund a deposit. The calculator here uses your estimate rather than computing pension tax.
Can a pension hold property funds instead?
Some pensions offer eligible property-related funds or investments, depending on their rules and platform. That is different from directly owning a particular rental house. Review costs, liquidity, diversification and suitability with an adviser; indirect exposure is not automatically low-risk or the best choice for your circumstances.
Who should advise me before moving pension money into property?
Use an appropriately authorised financial adviser for pension and investment recommendations, with your pension provider confirming its rules. An accountant can help with relevant tax calculations, and a broker and solicitor can assess the property transaction. A property coach or calculator does not replace that regulated advice.
Put the next step into practice
Use the free tools to test your numbers, then choose the level of support that fits your next decision.