Can I Transfer My Buy-to-Let Into a Limited Company?
October 15, 2026
You can potentially transfer a personally owned buy-to-let into a limited company, but it is not simply a change of name on the rent account. The company becomes a different owner, and the transfer can involve property transaction tax, Capital Gains Tax, new finance and legal work. Any future benefit needs to justify those costs and fit how you intend to use the income.
The question is therefore not “Are companies good for property?” It is “Would moving this particular property, on these terms, improve my position after all the costs?” Buying a future investment through a company is a separate decision from transferring a property you already own.
Here is a practical way to organise the comparison before paying for a transaction that may take years to recover its upfront cost.
Start with why you want the company
Write down the intended benefit in plain language. You might want to retain profits for further purchases, organise ownership with another person or develop a long-term portfolio structure. The analysis will differ if you need to withdraw all the rental income for household spending.
Ask your accountant to compare money retained inside the company with money available personally after any extraction taxes and costs. A company bank balance is not automatically your personal spending balance. A headline corporation-tax comparison can miss the second part of the journey.
Also consider administration, accounts, lending terms and future disposal. The structure should support the whole plan, including eventual income and exit, rather than optimise one line in next year's calculation while making the rest harder.
The transfer can be treated as a disposal
Moving an asset into a company you control can have tax consequences even where no ordinary sale proceeds arrive in your personal account. Connected-party and market-value rules may be relevant. Do not assume a nominal transfer price determines the tax value.
HMRC's incorporation guidance explains the market-value disposal principle in the context of transferring a business. Your accountant needs the property's history, cost, ownership, improvements and proposed transaction to establish the actual position.
Keep the valuation evidence and the professional calculation. A remembered purchase price and an estimate from an online portal are not a complete transaction file. If relief is being considered, obtain a written explanation of the conditions, supporting facts and consequences rather than recording the tax cost as zero by default.
Stamp duty can apply without a cash purchase price
For property in England or Northern Ireland, HMRC's land and property transfer guidance explains that transfers to a connected company can be charged by reference to market value. The actual tax and any relief need to be assessed for the transaction.
Scotland and Wales have different property transaction tax systems. Do not use an English SDLT result as a UK-wide answer. The correct jurisdiction, ownership structure, residential-property rules and available reliefs all belong in the professional calculation.
The useful budgeting lesson is simple: “No cash changes hands” does not establish “No transaction tax”. Ask how much must be funded, by whom and on what timetable. A company receiving a property may need accessible money to complete even when the arrangement does not look like a normal open-market sale.
Incorporation relief is conditional
Incorporation Relief can defer qualifying Capital Gains Tax in appropriate circumstances when a business is transferred to a company in exchange for shares. It is not a blanket exemption for every landlord moving a rental property into a company.
Whether the activity and transaction meet the conditions is a factual and technical question. Ask your adviser to explain why relief applies, how the consideration is structured and what happens to the gain. Deferral is different from the gain disappearing permanently.
Do not proceed because a promotional example resembles your portfolio at a superficial level. Number of properties, how the activity operates, ownership arrangements and the transaction steps can matter. Obtain advice for your own facts, especially where a proposal promises to remove every tax cost through a complicated sequence.
The existing mortgage does not simply follow the property
The current mortgage is an agreement with the existing borrower. Changing the property owner can require the old loan to be redeemed and a new company mortgage arranged, subject to lender approval. Ask the broker and conveyancer to map the exact sequence.
List early repayment charges, new product fees, valuation costs, legal costs and any change in interest payments. Ask whether personal guarantees are required. Our guide to limited-company mortgage guarantees explains why company ownership and personal commitments need to be assessed separately.
Do not assume the company can borrow the same amount on the same terms. Its eligibility, the property, rent and the lender's criteria must work together. A transfer that looks attractive in the tax model can still be unsuitable if financing consumes the expected benefit or demands more cash than you have available.
A £30,000 transfer cost needs a meaningful benefit
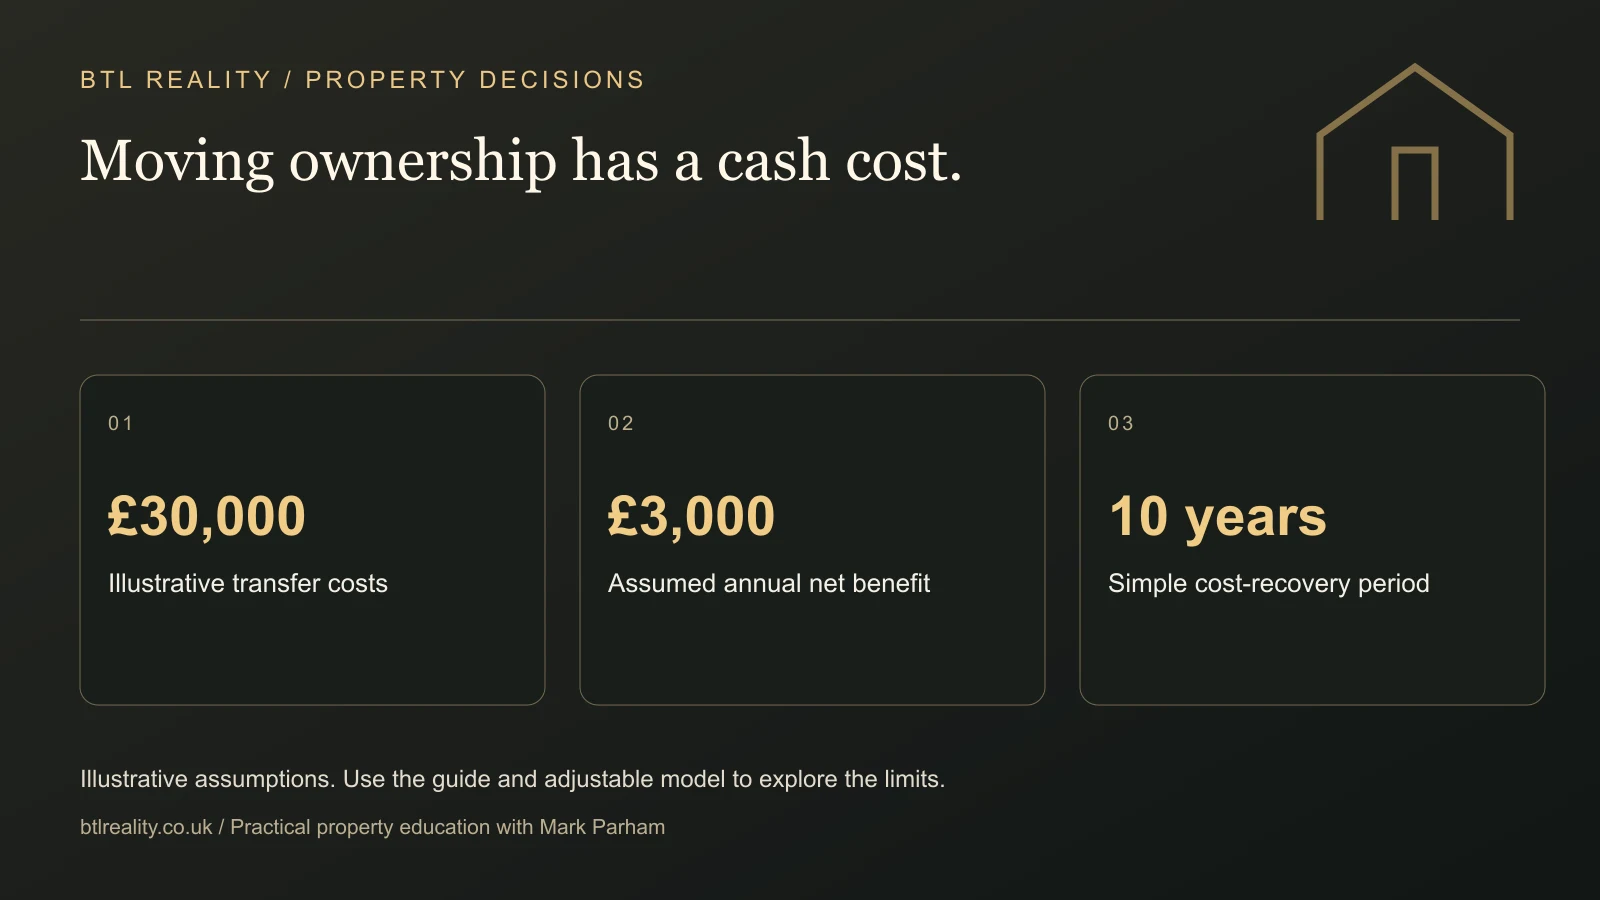
Consider a deliberately simplified example using professional estimates supplied for a hypothetical transaction. Combined tax costs are £20,000, exiting the old finance costs £3,000, arranging new finance costs £3,000 and legal and professional work totals £4,000. The total upfront cost is £30,000.
Now assume the properly compared annual benefit is £3,000 after the ongoing differences relevant to that owner's plan. Simple break-even is ten years: £30,000 divided by £3,000. If the annual benefit is only £1,500, it takes twenty years. At £5,000 it takes six.
These figures are not tax rates, quotes or a forecast. They illustrate why an apparently attractive annual saving can be small relative to the cost of changing ownership. The timing also matters: money paid now cannot be treated as equivalent to a possible saving received many years later.
Transfer costs versus ten years of assumed benefits
Make the example your own
How long would the transfer costs take to recover?
Enter professional estimates for your circumstances. The tool does not calculate tax or assume relief applies.
Compare benefits on the same after-tax and cash-withdrawal basis. No discounting, inflation, future tax changes or unentered costs. A zero or negative benefit has no positive recovery period. Illustrative only. Inputs stay in this page and are not saved or sent.
Calculate the annual difference consistently
Compare the same outcome on both sides. If the personal-ownership calculation ends with money available to spend, the company calculation should also reach that point. If the goal is reinvestment inside the company, label that clearly and do not call it personal take-home income.
Include ongoing accountancy and administration, differences in financing, relevant taxes and any other recurring cost changes. Use the same rent, maintenance assumptions and property performance unless there is a documented reason for a difference. Otherwise you may accidentally credit the company structure with an improvement caused by optimistic rental assumptions.
Run more than one future. What happens if rates rise, the property is sold sooner, or you begin withdrawing more income? A simple break-even tool helps frame the discussion, but it cannot replace a complete tax and cashflow comparison over the intended holding period.
Consider leaving the existing property where it is
One option may be to retain the current property personally and consider a company for future purchases. That avoids assuming every asset must sit in the same structure. It still requires advice on the overall position, but it is a legitimate comparison to put beside a full transfer.
Another option may be to wait for a relevant finance or business milestone before revisiting the decision. Timing can affect fees and available products, although future rules and rates cannot be guaranteed. The important point is to choose a deliberate review date rather than drift into a transfer because company ownership is fashionable.
You can also compare selling the existing property and reinvesting, but that creates its own costs, taxes and investment risks. Keep each route as a separate scenario. Do not mix the best assumptions from several different transactions into one apparently effortless outcome.
Assemble one pack for the advisers
Prepare the title and ownership details, purchase records, improvement invoices, current mortgage statement, tenancy information, rent history, costs and valuation evidence. Add your wider objectives: retained growth, personal income, joint ownership or eventual sale.
Ask the accountant, broker and conveyancer to use the same transaction assumptions. A tax estimate based on one structure and a mortgage quote based on another do not form a coherent plan. Confirm the proposed ownership and funding before relying on their combined figures.
Then record who is responsible for each step, what must be confirmed before commitment and how the costs will be funded. The transfer affects a real property and tenancy, so rent collection, insurance, notices and contractual arrangements should be reviewed as part of the implementation.
Make the decision on the full comparison
Use the property portfolio calculator to organise the broader investment picture, while keeping ownership-specific tax calculations with your accountant. The free tool helps explore assets, borrowing and cashflow; it does not decide whether incorporation relief applies.
Private Mentorship can support deeper portfolio strategy and modelling. Structural decisions should then be implemented with the appropriate tax, legal and mortgage advice. The goal is a portfolio organised around what you want it to do, with a clear reason for accepting the cost of any change.
Frequently asked questions
Is moving a rental into my company treated as a sale?
It can constitute a disposal for tax purposes even though you control the company. Market-value rules and possible reliefs need consideration. Ask your accountant to calculate the actual treatment using the property's history and the proposed transaction rather than assuming it is an internal administrative change.
Can stamp duty apply even if no cash changes hands?
Yes, SDLT can arise on a transfer to a connected company by reference to market value. The precise rules and reliefs depend on the transaction. Scotland and Wales use different property transaction taxes, so obtain a calculation for the property's jurisdiction.
Could a transfer trigger Capital Gains Tax?
Yes, a disposal can bring an accrued gain into consideration. Any available relief is conditional and may defer rather than eliminate the gain. Obtain a professional calculation before committing and ensure the transaction's funding can cover liabilities that are actually due.
Can I transfer the existing mortgage into the company?
Do not assume so. The lender must agree the relevant arrangements, and a new company loan may be required to redeem the personal mortgage. Check fees, eligibility, guarantees and the monthly cost with a broker before treating the finance as unchanged.
Does incorporation relief automatically apply to landlords?
No. The activity and transfer must satisfy the relevant requirements. Owning a rental property or registering a company is not enough on its own. Ask for advice explaining the factual basis, conditions and treatment of the gain in your particular case.
How should I compare upfront costs with future savings?
Add the independently estimated transaction costs, then compare consistent annual outcomes after ongoing finance, administration and relevant taxes. Test different holding periods and income-withdrawal plans. Simple break-even is a starting point and does not include investment returns, changing rules or the time value of money.
Put the next step into practice
Use the free tools to test your numbers, then choose the level of support that fits your next decision.