Can I Buy a Property With Cash and Mortgage It Later?
October 13, 2026
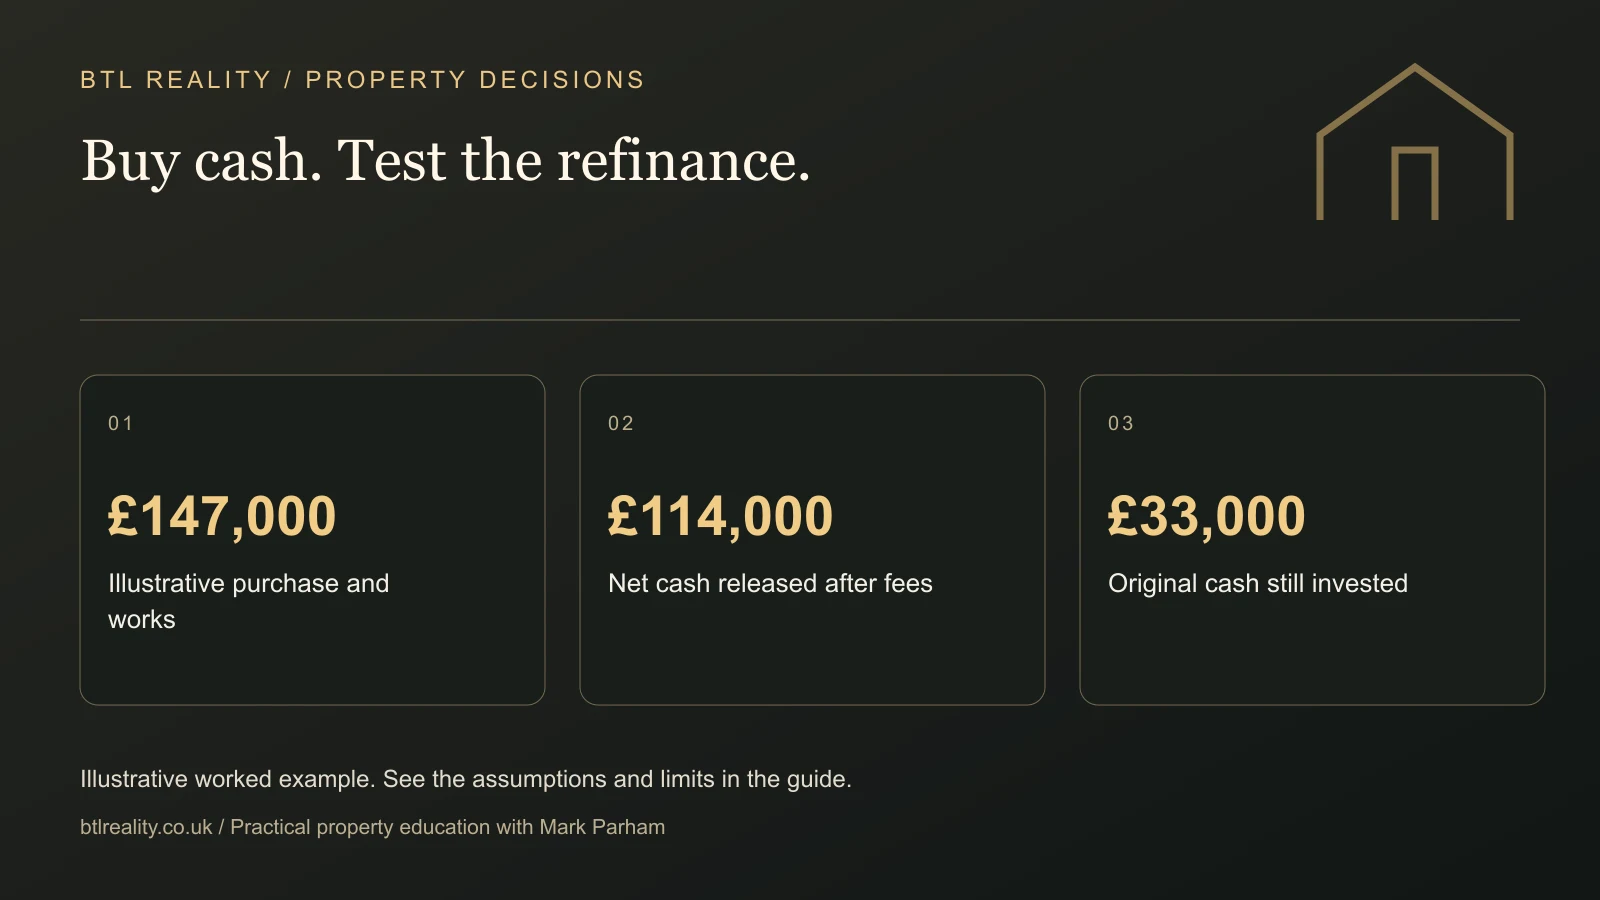
You can potentially buy a property with cash and arrange a mortgage later, but the second transaction is a fresh lending decision. Owning the property outright does not guarantee the lender will accept it, lend the amount you expect or release money on your preferred date.
The strategy can be useful when cash gives you flexibility at purchase. It becomes fragile when the next deposit, renovation bill or household commitment depends on a refinance that has not been approved. The right starting point is to ask whether you can comfortably hold the property if the mortgage takes longer, is smaller or never happens.
Here is how to model that decision, what to ask before buying and why money released from a property is different from profit.
Separate the cash purchase from the later mortgage
At the first stage, you buy with available funds and pay the associated costs. At the second, a lender considers a loan secured on the property. The property's condition, value, rental evidence, ownership history and your circumstances are assessed against the product and policy available at that time.
That means a cash purchase can remove mortgage delays from the initial transaction without removing mortgage risk from the overall strategy. If you bought cash because mainstream lenders would not accept the building, you still need to establish what will make it acceptable later. A new kitchen alone does not resolve every construction, title or tenancy issue.
Tell your broker the full sequence before you exchange or otherwise become bound to buy. Include the source of purchase money, intended work, expected letting date and proposed use of the released funds. An early discussion can identify a problem before your cash is tied up in the asset.
The six-month rule is not a universal promise
Ownership-period requirements differ between lenders and cases. As one current example, The Mortgage Works' general criteria describe six-month ownership requirements, with an additional letting-history condition for some applicants. That does not establish a market-wide right to refinance on day one of month seven.
Ask the broker when your proposed lender measures ownership, whether a letting history is required, and what evidence must be available. Also ask how a recent purchase price and subsequent works will be considered in the valuation. A calendar reminder is useful, but it is not mortgage approval.
Do not confuse a short ownership period with a defective property. They are separate issues. Waiting may address one lender's timing rule; it will not automatically fix an unacceptable lease, missing consent or insufficient rent. Put each condition on its own line so the exit plan is based on evidence rather than the passage of time.
A worked example: £147,000 in, £114,000 released
Suppose the purchase price is £135,000. Assume £12,000 for purchase costs and work, giving £147,000 committed before any additional holding costs or reserve. The buyer expects an accepted refinance value of £155,000 and models a 75% loan-to-value mortgage.
The arithmetic produces a gross loan of £116,250. If £2,250 of refinance costs are paid from those proceeds, the net cash released is £114,000. With no existing mortgage to repay, the simplified calculation leaves £33,000 of the original investment unrecovered: £147,000 minus £114,000.
It does not show a £114,000 profit. The property now carries £116,250 of debt. Its assumed equity is £38,750, based on the £155,000 valuation, while cash left invested reflects your historical expenditure and transaction costs. Equity and unrecovered cash are different measures.
The property refinance calculator helps explore that distinction. Keep your own current borrowing, fees and property figures in the model, and do not treat an estimate as a lending quotation.
What if the valuation is only £140,000?
At the same illustrative 75% loan-to-value, a £140,000 accepted valuation supports £105,000 of borrowing before any further affordability constraint. After the same £2,250 costs, £102,750 is released. The unrecovered amount becomes £44,250, which is £11,250 more than the optimistic example.
If your next purchase depended on receiving £114,000, that difference matters immediately. You may need to reduce the next budget, wait while saving more, or abandon the second deal. It is better to know this before you promise money to another seller or contractor.
A lower valuation is only one possible constraint. The rent may support a smaller loan, the lender may offer a lower maximum loan-to-value, or your application may not meet its requirements. Calculate the potential loan as the amount the lender actually agrees, not simply a percentage multiplied by your preferred property value.
Make the example your own
How much cash stays invested?
Change the accepted valuation and loan-to-value to see how the refinance could differ from the original plan.
Assumes no existing mortgage. A negative unrecovered amount means proceeds exceed the input costs, not guaranteed profit. Fees remain a cost even if proceeds are insufficient. Excludes rent, holding costs, tax and unentered expenses. Rent coverage or other criteria may reduce the loan. Illustrative only. Inputs stay in this page and are not saved or sent.
The no-refinance case belongs in the plan
Ask what happens if no mortgage is completed for twelve months. Can you still meet household commitments, finish essential work and keep an adequate property reserve? Would another project stall because its funding was assumed to come from this property?
A cash-owned rental may produce income without mortgage interest, but it still has maintenance, management, insurance, compliance and vacancy costs. You also have money concentrated in an asset that may take time and expense to sell. Rental receipts do not make all your original cash immediately accessible.
Write down the fallback you would actually accept. Holding a viable rental for longer is different from being forced to sell an unfinished project. If the fallback would put your household or existing portfolio under pressure, the cash purchase may be too large even when the expected refinancing case looks attractive.
Check the income after the refinance
Borrowing changes the monthly result. In the £155,000 valuation example, an interest-only £116,250 loan at an assumed 5% costs about £484 a month. If rent is £1,000 and other operating costs and allowances are £300, the remaining amount is about £216 monthly before tax and exceptional work.
At an assumed 7% rate, interest is about £678 and the same model leaves approximately £22. These are simple illustrations with no capital repayment, not available mortgage offers. They show why a successful cash release can leave a much thinner income stream than the original mortgage-free rental.
Use the mortgage stress calculator before deciding how much debt you want. Borrowing the maximum available may speed the next purchase while reducing resilience in the property that produced the deposit. Judge the two investments together.
Keep a complete record of the money and work
Retain the purchase statement, source-of-funds evidence, invoices, permissions and dated photographs. Ask the broker which records will support the proposed application, and ask the valuer-facing professional what information can properly be supplied about completed improvements.
Do not assume expenditure equals value added. Spending £20,000 proves that £20,000 left your account. It does not prove a buyer or lender will value the property £20,000 higher. Comparable transactions, condition, specification and the local market still matter.
If funds come from a company, gift or borrowing secured elsewhere, disclose the arrangement accurately. A purchase described as cash funded may still leave substantial debt in another part of your finances. Your overall risk assessment must include that debt and its repayment terms.
Compare this with financing the purchase from the outset
A mortgage at purchase may preserve liquidity, while a cash purchase followed by a later loan may involve different fees, timing and execution risks. Compare the complete sequences rather than the initial deposit alone. Include both sets of professional costs where they arise and any finance costs during the holding period.
There may be a genuine reason to choose cash, such as a seller valuing a simpler chain or work that must be completed before a particular mortgage is available. Quantify that benefit. An assumed discount should be supported by evidence, and a fast completion should not mean omitting legal or condition checks.
The buy-to-let deal calculator can establish the acquisition budget. Then build the later refinancing case separately, with conservative and no-refinance alternatives alongside the preferred outcome.
Make the exit plan specific before you buy
A useful exit plan names the lending requirements to satisfy, the documents to obtain, the realistic timetable, the minimum acceptable cash release and the fallback if any of those change. “Refinance later” is a strategy label, not an executable plan.
If you want help turning property goals into a clearer set of numbers and actions, Starter Club is a place to develop that understanding. Use a qualified mortgage adviser for product suitability and eligibility. The aim is to make the cash purchase work on its own merits, with refinancing as a tested possibility rather than an assumed rescue.
If your income comes from assets rather than employment, the guide to buy-to-let mortgages without a salary explains why the property reserve and household reserve should be assessed separately.
Frequently asked questions
How soon can I remortgage a property bought with cash?
Timing depends on the lender, your ownership and letting history, the property's condition and the proposed borrowing. Ask a broker before purchase about the likely route and requirements. Being mortgage-free does not mean every lender will accept an immediate application or lend against your expected value.
Is the six-month mortgage rule universal?
No. Individual lenders apply their own criteria and exceptions. Even where six months is relevant, reaching that point does not guarantee acceptance. Borrower checks, valuation, rental coverage and other conditions still apply. Confirm the exact policy for your proposed transaction rather than treating six months as a legal entitlement.
Can I borrow against the new value after refurbishment?
Potentially, subject to the lender's valuation approach and other criteria. Your renovation spend and target resale figure do not determine the accepted value. Keep evidence of the work and ask how a recent purchase is treated. Model a lower value so the plan can absorb disappointment.
Do I need tenants before refinancing?
Some routes may require evidence of letting, while others assess proposed rental income under their own conditions. The answer depends on the applicant, property and lender. Tell your broker whether the property is occupied, vacant or undergoing work so the route matches the actual position.
What if the refinance valuation is lower than expected?
A lower accepted value may reduce borrowing and leave more cash tied up. Recalculate the loan, fees, monthly finance cost and next project's funding. You may need to retain the property longer or change the next purchase plan. Do not commit the expected proceeds before the refinance completes.
What should I check before committing to a cash purchase?
Check title and condition, the complete purchase budget, reserves, realistic rent and the proposed refinancing criteria. Record the minimum cash release you need and what happens if it is unavailable. Take mortgage questions to a qualified adviser and legal questions to your conveyancer before becoming committed.
Put the next step into practice
Use the free tools to test your numbers, then choose the level of support that fits your next decision.