HMO vs Single Let: Compare the Real Costs and Returns
October 17, 2026
By Mark Parham
BTL Reality · Practical property education
An HMO can generate more rent from one building than a single let, but it can also require more capital, management and compliance work. The useful comparison is cashflow after all costs, measured against the full money and time invested. Gross rent alone cannot tell you which strategy is better.
This guide uses invented examples to expose the differences. It is not a claim about typical UK returns or permission to convert any particular house. Actual demand, finance, licensing and planning need property-specific checks.
What changes when you let by the room?
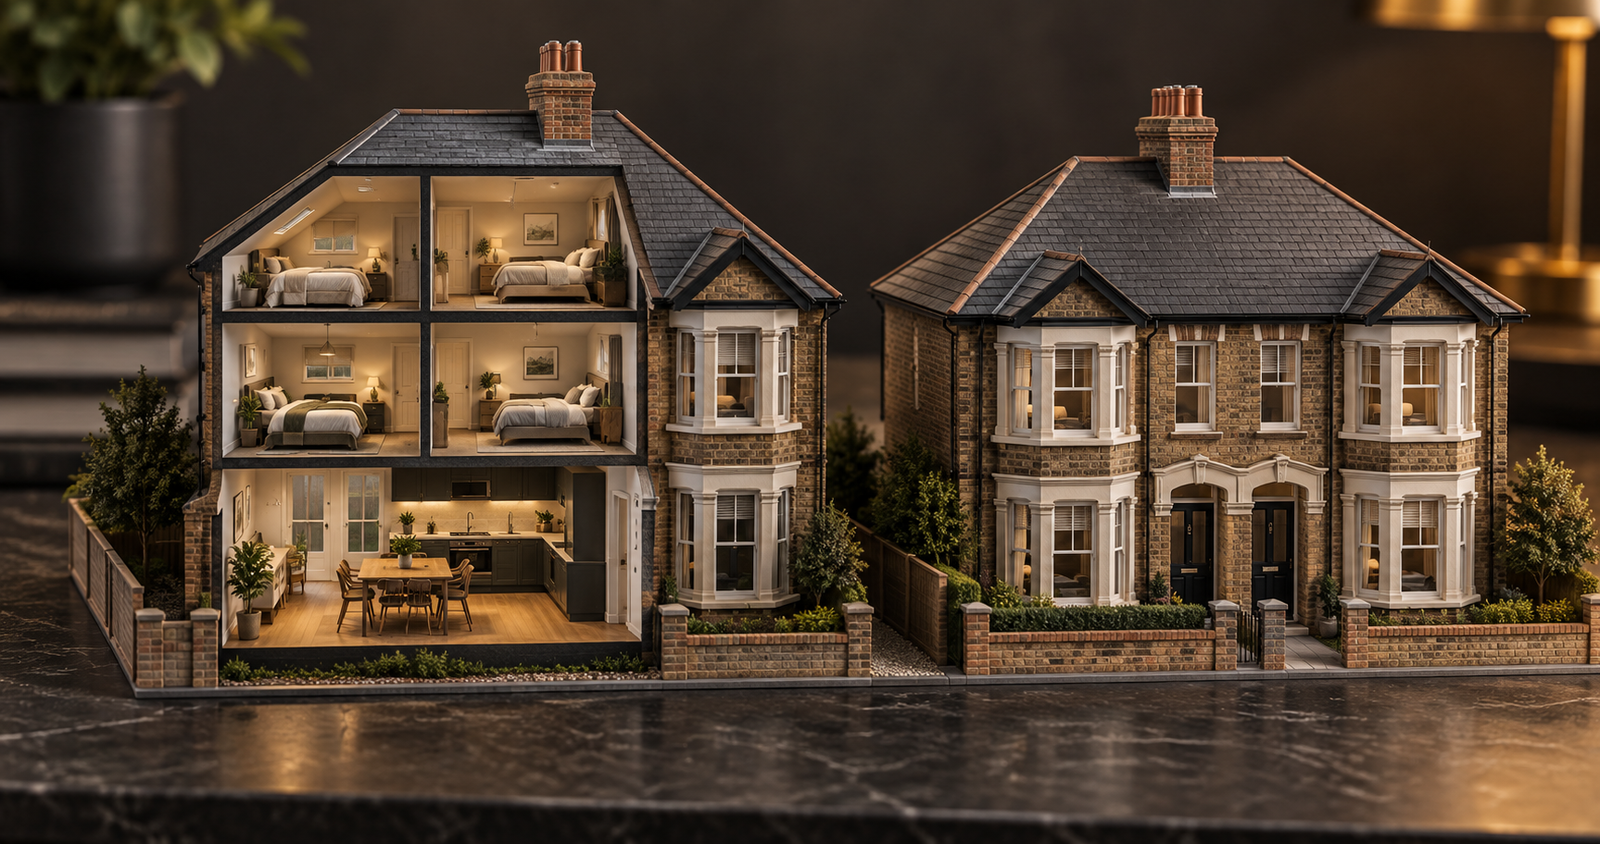
A conventional single let is generally let as one home to a household. An HMO involves occupiers from more than one household sharing facilities, with legal definitions and requirements that vary across the UK. Separate room income can spread the impact of one vacancy, but also creates more moving parts.
Single let
One household and one rent stream can make day-to-day coordination simpler. An empty property can remove all rent, while the mortgage and other owner costs continue. The tenant may pay many household bills, subject to the agreement and circumstances.
HMO
Multiple rent streams can increase gross income. More occupants can mean more turnover, coordination and wear. Landlord-paid bills, furniture, common areas, specialist finance and licensing can absorb a significant part of the extra rent.
Check permission before modelling the upside
In England, mandatory HMO licensing generally covers properties occupied by at least five people forming two or more households and sharing facilities. Smaller HMOs can also need a licence under local schemes. Check the government licence guidance and the relevant council’s requirements for the address.
Licensing and planning are separate checks. For example, Leeds City Council’s planning guidance explains how local Article 4 directions can affect HMO use. Do not assume a licence establishes planning permission, or that a house with five bedrooms can lawfully accommodate five unrelated tenants. Check room standards, fire safety, building regulations, title restrictions, lender consent and insurance too.
TRY THE NUMBERS
How full does an HMO need to be?
Move the sliders to compare the five-room illustration with the single let below. Results are monthly cashflow before tax, not a forecast or a mortgage quote.
The HMO produces £311.48 more a month in this illustration, before tax and initial conversion costs.
Fixed assumptions: £187,500 interest-only debt; HMO rate 6%, management 15% of collected rent including VAT, plus £350 monthly maintenance, insurance, compliance, furniture and licence reserves. The single-let assumptions are itemised below. No capital growth, tax or initial conversion costs included. Figures stay in this page and are not submitted.
JavaScript is needed for the sliders. Default results and the worked example remain readable.
Follow the money through both examples
For comparison, both illustrations use a £250,000 property and £187,500 interest-only debt. This isolates operating differences. It does not assume the same building would be suitable for both uses, or that either mortgage would be available.
| Item | Single let | Five-room HMO |
|---|---|---|
| Rent at full occupancy | £1,400 | £3,000 |
| Occupancy assumption | 95% | 90% |
| Expected rent collected | £1,330 | £2,700 |
| Management, including VAT | £159.60 (12%) | £405 (15%) |
| Bills, council tax, broadband | £0* | £550 |
| Maintenance reserve | £100 | £150 |
| Insurance and compliance | £65 | £100 |
| Furniture and licence reserves | £0* | £100 |
| Mortgage interest | £859.38 (5.5%) | £937.50 (6%) |
| Cashflow after allowances | £146.03 | £457.50 |
*Single-let example assumes an unfurnished property with no local licence fee and bills paid by the occupying household. Vacancy-related bills and council tax would need adding in a real model. HMO furniture reserve is £75 and licence reserve £25 monthly. All figures are assumptions, not market averages. No major works, initial conversion expenditure or tax included.
The occupancy difference can overturn the result
The HMO collects £1,370 more rent than the single let at the default settings, yet the cashflow difference is only about £311 monthly. The rest funds extra operating costs and interest. That may still be worthwhile, but it is a different proposition from comparing £3,000 with £1,400 and stopping there.
Initial conversion costs can change the return again
Monthly cashflow is not return on all the cash invested. An HMO may require layout changes, fire precautions, furniture, professional fees and a longer period before letting. Get written, property-specific advice and quotations before treating the project as viable.
As a simple sensitivity, an extra £40,000 of upfront HMO expenditure against the model’s £311.48 extra monthly cashflow takes roughly 10.7 years to recover through that additional cashflow alone. That ignores tax, finance on the works, later replacements, growth and resale differences. It is not a payback forecast; it shows why the starting capital belongs in the comparison.
Calculate annual cashflow divided by all cash committed, including purchase costs and conversion costs. Then stress the result. Our Buy-to-Let Deal Calculator supports the wider deal assessment, while this article’s tool isolates occupancy and bills.
Choose based on evidence and capability
- Verify tenant demand for the exact rooms or whole property. Enquiries are not the same as signed tenancies at your target rent.
- Confirm lawful use and capacity. Get the relevant professional and council checks before committing to a conversion strategy.
- Price the full operation. Include an agent experienced in that property type, even if you initially plan to manage yourself.
- Stress occupancy, bills and interest together. A model that survives one change can still fail when several occur.
- Compare cash committed and exit options. Consider who would buy the property and whether an alternative use is practical and lawful.
A higher-maintenance investment can be suitable for an investor with the resources and systems to operate it. A simpler single let can be better aligned with someone seeking less involvement. The aim is a return you understand and can support.
Test a bad operating year before a good one
At £600 per room, reducing the HMO model’s average occupancy from 90% to 70% cuts collected rent from £2,700 to £2,100 monthly. Management falls with the rent, but the mortgage and assumed fixed bills do not. The result moves from a £457.50 surplus to a £52.50 shortfall before tax.
Now put occupancy back at 90% and increase the bills slider from £550 to £800. The model’s cashflow falls to £207.50. Combining 70% occupancy with £800 bills creates a £302.50 monthly shortfall. Neither setting predicts what will happen; they show why several moderate pressures can matter together.
Average occupancy also hides timing. Two rooms empty for a long period may feel different from short gaps spread across the year, particularly when major repairs fall due at the same time. Prepare a cash reserve against the sequence of possible payments, not only the annual average.
Do not compare returns using different denominators
A single let might need a deposit, purchase costs and a modest setup budget. An HMO might need those items plus conversion works, furniture, professional input and finance during the project. If you divide both annual cashflow figures by the same deposit, you can flatter the HMO return by ignoring the additional capital.
For illustration, £146.03 monthly cashflow is about £1,752 annually. Against £80,000 total committed cash, that is approximately 2.2% before tax. The HMO’s £457.50 monthly is £5,490 annually. If its full committed cash is £120,000, the corresponding figure is about 4.6%. These invented capital totals illustrate the method, not typical project costs or expected returns.
The HMO still leads in that example, but the percentage is much less dramatic than the gross-rent comparison. You should also consider time to complete, cash tied up during works and the risk of a different eventual sale value.
Match the operating team to the property
An agent who is excellent at family lets may not offer the systems you need for room-by-room management. Ask about tenant demand, turnover, common-area inspections, bill administration and contractor availability for the actual location and property type.
Equally, do not assume a specialist service removes your oversight. Agree the reporting and spending authority, then include its full fee structure in the model. The most attractive strategy on paper can still be the wrong fit if you cannot resource its operation.
Compare the complete investment
Put your own rent evidence, quotes and borrowing assumptions into the deal calculator. Explore Blueprint if you want to develop the wider framework for selecting and assessing property investments.
Is an HMO always more profitable?
No. Higher rent can be outweighed by bills, management, maintenance, finance and the extra cash needed to create or buy it. Compare like-for-like assumptions and run an occupancy stress test.
Does one empty room make an HMO safer?
It can reduce the immediate rent loss compared with a completely empty single let. That advantage has to be weighed against room turnover, fixed bills, operating complexity and the occupancy level needed to cover costs.
Prepared using information checked on 30 September 2026. Check the linked product pages for current availability and terms. This is general property education, not personal financial, mortgage, tax or legal advice. Models and examples are illustrative. Property values and income can fall, and outcomes are not guaranteed.