How Do I Buy a UK Buy-to-Let While Living in Dubai?
October 9, 2026
You can buy a UK buy-to-let while living in Dubai, but organise the finance, legal process, purchase budget and local management before committing to a property. Distance does not remove any of the checks a UK-based investor needs. It makes a clear brief and dependable people more valuable because you cannot easily inspect every problem yourself.
The strongest starting point is not a list of attractive houses. It is a written answer to four questions: what can you fund, what kind of property fits the objective, who will verify it locally, and who will look after it after completion? Once those are settled, a remote purchase becomes a sequence you can manage.
Decide what the property is meant to do
Are you building long-term UK assets, generating income to spend abroad, planning a future return to Britain or diversifying an existing portfolio? Different objectives imply different debt, reserve and location choices. Buying near somewhere familiar can be convenient, but familiarity is not evidence of rental demand or an attractive price.
Write a brief covering total cash available in pounds, purchase range, acceptable works, property type, target tenant demand and minimum cashflow. Include how much time you want to spend overseeing it. A heavy refurbishment may conflict with a busy overseas job even if the spreadsheet shows a higher potential return.
If future personal occupation is a possibility, tell the broker and solicitor. Do not assume an investment mortgage or an existing tenancy can simply be switched to match a later plan without further steps.
Check expat finance before paying reservation fees
Living in the UAE does not mean every UK lender will accept your application, income or property. Criteria can depend on residence, nationality, employment, currency, ownership structure, property type and rental affordability. A broker experienced in overseas applicants can assess the combination rather than just quote a maximum loan-to-value.
For an example of country-specific policy, HSBC's non-UK resident mortgage information includes the UAE among locations from which applications may be considered, subject to its criteria. That is evidence that routes exist, not a universal offer or a recommendation for a particular lender.
Prepare identity and address evidence, earnings or business records, bank statements and the history of the deposit. Ask which documents need certification or translation and how long they remain valid. The lender and solicitor may each need evidence for their own checks.
Build the purchase budget in the currency you will pay
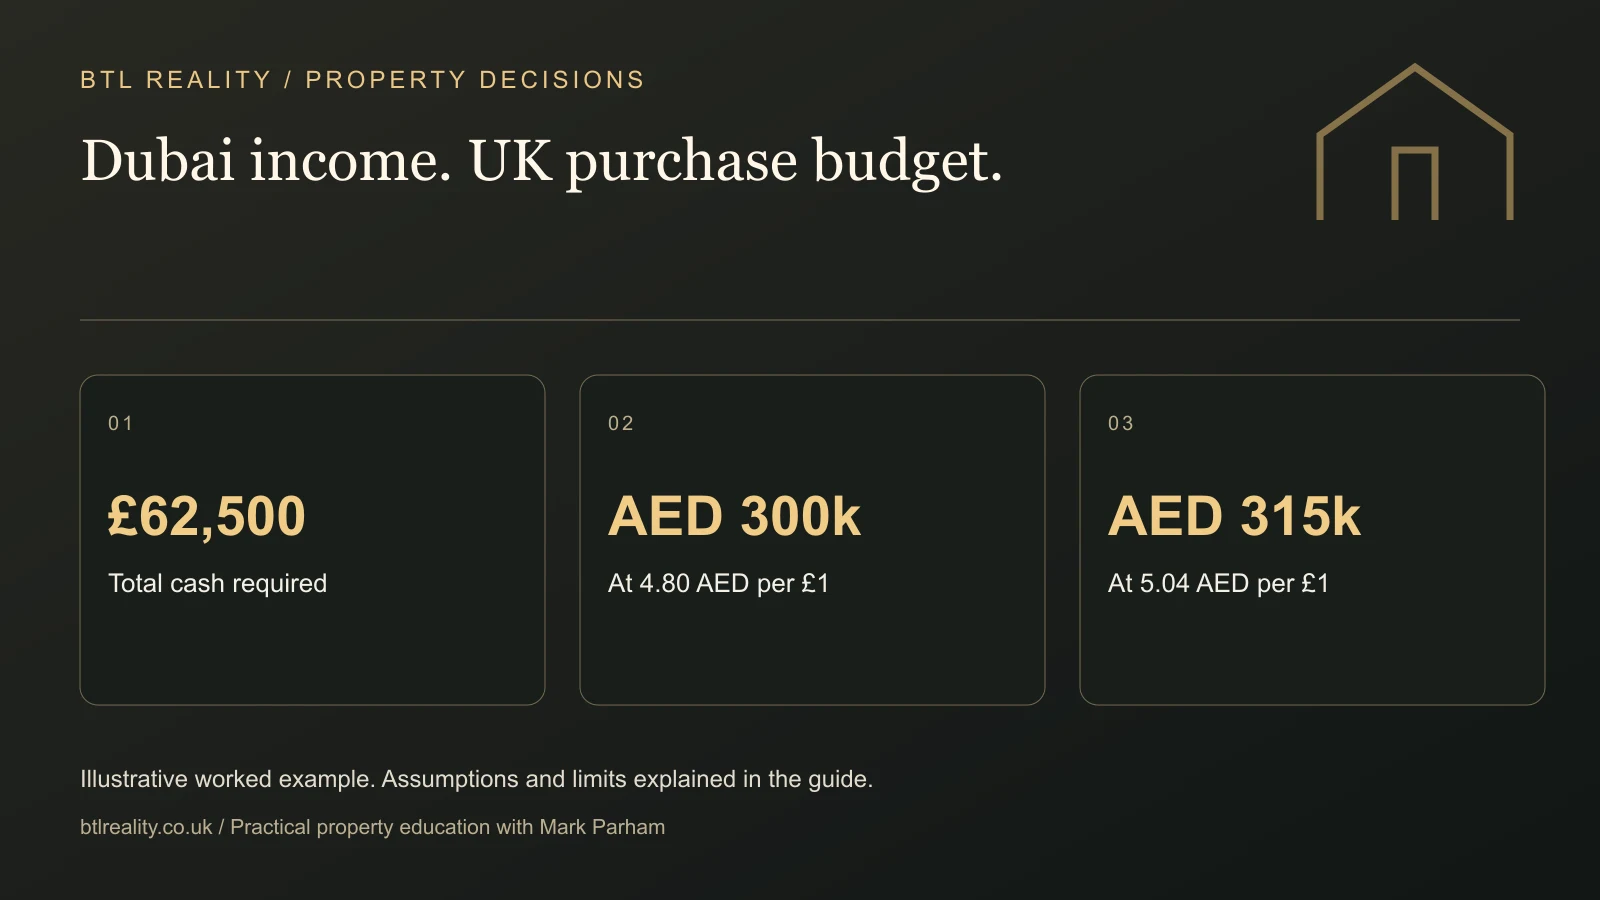
Suppose a property costs £150,000 with an illustrative 75% mortgage. The deposit is £37,500. Add a £12,000 combined purchase-cost allowance, £5,000 works and setup, and £8,000 reserve. Total planned cash is £62,500. The cost allowance is an input to replace with quotations and the correct purchase tax, not a calculation of your liability.
At an illustrative exchange rate of 4.8 AED per pound, £62,500 requires AED 300,000 before transfer costs. At 5.04, it requires AED 315,000. A 5% increase in the sterling cost adds AED 15,000 even though the UK property price has not changed.
Keep funds available for staged payments and completion deadlines. Ask your provider and solicitor about transfer timings, accepted sending accounts and evidence. Do not wait until completion morning to discover a bank limit or a documentation requirement.
Make the example your own
How much AED does your sterling budget need?
The same UK purchase budget can require a different amount of overseas currency.
Illustrative exchange rates, not live quotations. Use an executable provider quote for real transfers. Illustrative only. Inputs stay in this page and are not saved or sent.
Choose the jurisdiction and ownership carefully
England, Wales, Scotland and Northern Ireland have different property and landlord rules, and purchase taxes are not identical. Additional-property and residence-related rules may affect the upfront bill. Have the solicitor calculate the actual liability for your circumstances and transaction before you commit.
Personal ownership and company ownership also have different finance, reporting and withdrawal consequences. A UAE company, a UK property company and a personal purchase are not interchangeable. Get the tax and lending assessments together before choosing a structure, rather than trying to repair an unsuitable choice after exchange.
Use the buy-to-let deal calculator to bring the costs together. Replace example figures with written estimates from the people handling your purchase and leave a visible buffer for uncertain items.
Verify the property through independent evidence
A video viewing is useful, but it does not replace a survey or legal due diligence. Request the full route through the property, communal areas where relevant and the surrounding street. Ask what cannot be seen, including roof condition, damp causes, services and repairs hidden behind fresh decoration.
Check sold comparables rather than relying on the asking price or the seller's valuation. Obtain rental evidence from local agents and understand the tenant profile. If a sourcer presents the deal, establish who produced each assumption and which checks remain your responsibility.
Commission the appropriate survey and legal work for the property. Lease terms, service charges, licensing and existing tenancies can alter the investment substantially. Distance is a reason to document those checks more carefully, not to accept a “fully managed” label as a substitute.
Appoint management before completion
Ask a prospective letting agent how they handle tenant selection, compliance, inspections, arrears, emergencies and repairs. Get their fee schedule including VAT where applicable, renewal or reletting charges, contractor markups and termination terms. Compare service and reporting as well as the headline percentage.
Agree a repair approval limit and a genuine emergency process. A leak cannot wait for you to finish work in Dubai, but routine spending should not be open-ended. Set who can authorise action, who receives updates and which invoices or photographs you expect afterwards.
Make sure insurance reflects the letting arrangement and overseas circumstances. Tell the relevant professionals where you live and how the property will be used. A workable operating setup should not rely on omitting inconvenient details from an application.
Understand the tax and cash reporting
UK property income can remain taxable in the UK while you live abroad. The Non-Resident Landlord Scheme deals with rent collection and withholding arrangements; permission to receive rent gross does not by itself remove tax liability. Read HMRC's overseas-landlord guidance and obtain advice on your own residence and ownership position.
Maintain a UK property ledger showing rent received, agent deductions, repairs, finance, tax provisions and reserves. Money arriving in a bank account is not automatically available for transfer to your lifestyle account. If a company owns the property, the route from company cash to your personal spending needs separate consideration.
Review actual cashflow against the original deal every month initially. If the agent's statement shows less than the forecast, identify whether the difference is timing, a one-off cost or a recurring assumption that needs correcting.
Use help where distance creates a real gap
The point of professional support is to handle tasks you cannot assess or perform reliably yourself. Keep the roles clear: sourcing finds and assesses opportunities against a brief, a broker advises on finance, a solicitor handles legal work, a surveyor assesses condition and an agent manages the tenancy under an agreed service.
BTL Reality Done For You is a property sourcing service built around an agreed brief. It can be a relevant next step when you want help finding a suitable UK investment. Confirm scope and fees before instruction; sourcing does not automatically include every professional service or ongoing property management.
Frequently asked questions
Can a British expat in Dubai get a UK buy-to-let mortgage?
Some lenders consider UK expats living in the UAE, subject to their criteria. Residence alone does not establish eligibility. Income, deposit source, property, rental cover and ownership structure all matter. Ask a broker to assess your circumstances before relying on a advertised loan percentage or committing money to a purchase.
Do I need to fly to the UK to buy an investment property?
Some transactions can be handled remotely, but identity checks, signing requirements and property inspections still need proper arrangements. Confirm the process with your solicitor and lender. An independent local survey and viewing can be valuable even when your own travel is impractical; remote completion does not mean reduced due diligence.
Can I use my UAE salary for a UK mortgage application?
A lender may accept overseas earnings, but currency, employment type, evidence and affordability policies differ. Self-employed or business income can require different documentation from salary. Provide complete records and ask how the lender treats currency movements rather than assuming an AED salary will be assessed exactly like UK employment income.
Is UK rental income tax-free because I live in Dubai?
No. Living in Dubai does not make UK property income automatically free of UK tax. The result depends on the applicable tax rules and your circumstances. Arrange reporting and any Non-Resident Landlord Scheme requirements with an adviser, and keep enough cash for the liability rather than treating gross receipts as spendable profit.
Should I buy near London or in a northern city from overseas?
Choose from evidence of demand, price, costs, financing and the management setup, not a regional label. A northern property can still be poor value, while an apparently lower-yielding location may have other advantages. Compare actual deals against the same written brief and stress-test the rent and operating costs.
Can a sourcing company manage the property after purchase?
Only if that service is explicitly offered and agreed. Sourcing and letting management have different tasks and contracts. Ask who will hold keys, communicate with tenants, arrange repairs and provide statements after completion. Do not infer ongoing management from a promise to help you find or purchase the property.
Put the next step into practice
Use the free tools to test your numbers, then choose the level of support that fits your next decision.