Can I Get a Mortgage on a House That Needs Renovation?
October 7, 2026
You may be able to get a mortgage on a property needing renovation, but the type and severity of the work matter. A tired but lettable house is different from one with no usable facilities, structural concerns or work that prevents occupation. A standard buy-to-let mortgage should not be assumed to fund every refurbishment opportunity.
Before asking whether the finished property will be profitable, establish how you can buy it in its current state. A projected end value is not a solution to a funding gap at completion.
Cosmetic work and fundamental condition are different
A house needing decoration, floor coverings and minor repairs may present a different lending proposition from one requiring structural stabilisation or major services replacement. Photographs do not reliably establish where a property sits on that spectrum.
Ask what works are necessary, which are optional and whether the property is currently suitable for the intended letting. A functioning kitchen or bathroom is relevant, but condition cannot be reduced to a two-item checklist. Safety, construction, defects, access and other issues can matter.
The Mortgage Works' minimum property standards provide one lender's example of the importance of present condition and lettability. Other lenders and specialist products differ. Have the actual property assessed rather than relying on a general description such as “light refurb”.
Give the broker the uncomfortable details early
Send accurate particulars, photographs, the works scope and any available reports. Explain missing facilities, known defects, intended structural alterations, occupancy and your proposed timetable. A broker cannot identify an appropriate route if the facts are filtered to make the property sound easier.
Ask whether standard buy-to-let lending is realistic, whether any retention might apply, and what must be completed before funds are released. Also ask how the completed works will be assessed and whether the proposed tenancy fits the product.
A mortgage agreement in principle concerns a proposed borrower and borrowing position. It does not establish that every property you subsequently choose is acceptable security. Keep that distinction clear when negotiating deadlines.
The cash needed may peak before the work is finished
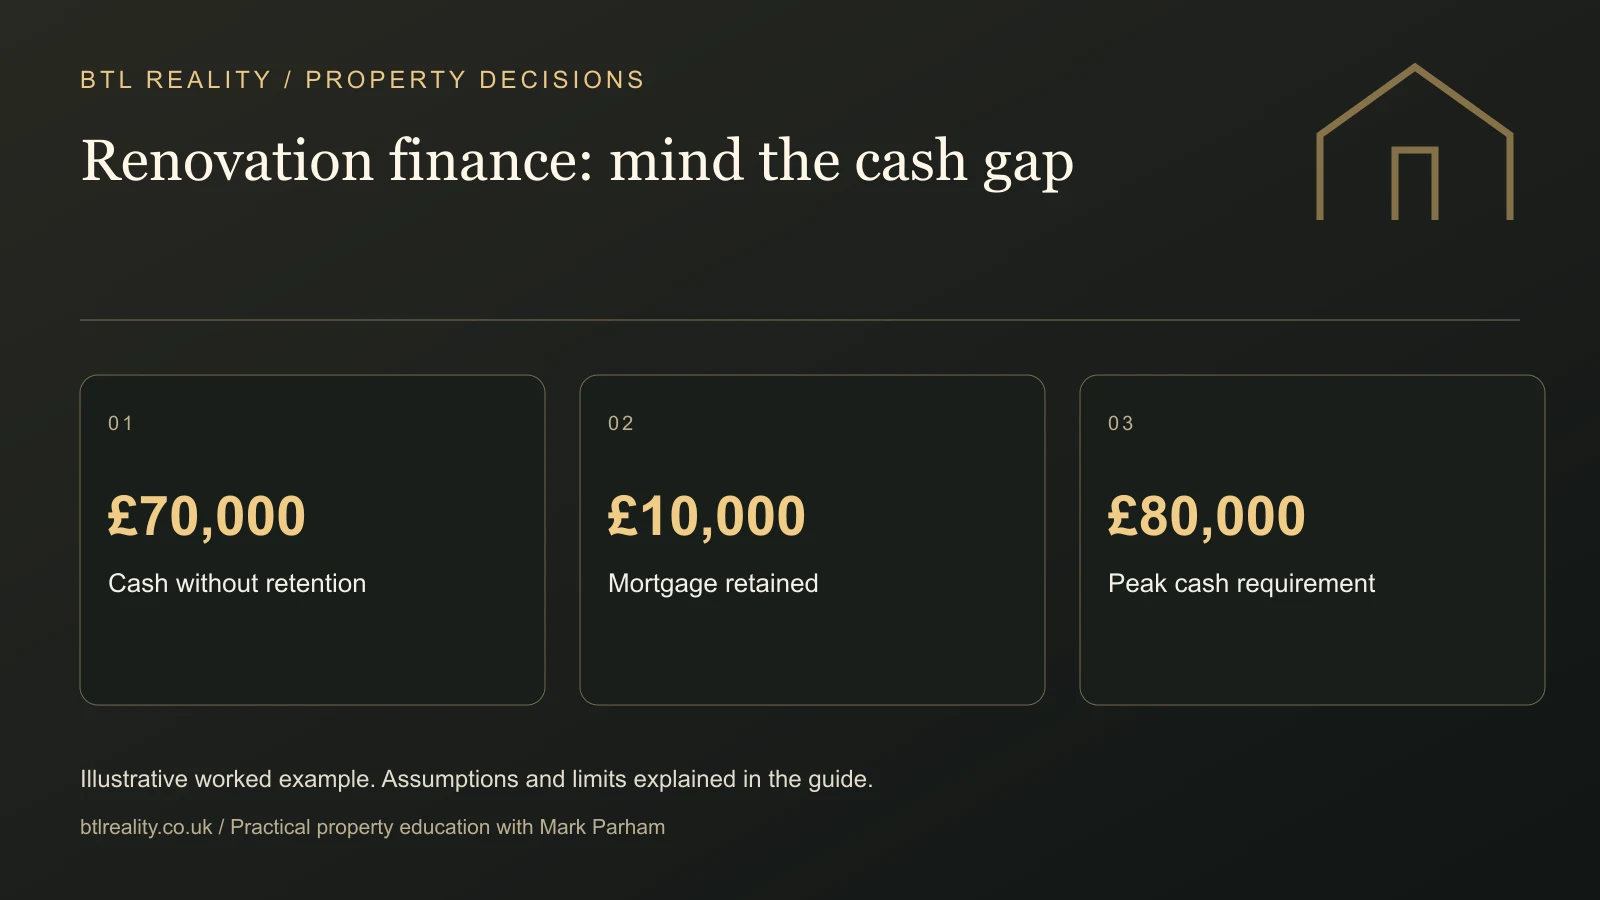
Consider a hypothetical £120,000 purchase with a £25,000 works budget. Assume £8,000 of other purchase and holding costs and a £7,000 reserve. If a lender advances £90,000 at completion, the starting cash allocation is £70,000: £30,000 towards the price plus the other amounts.
Now suppose £10,000 of that loan is retained pending work, leaving £80,000 initially available. You need another £10,000 of temporary cash to complete the same programme. The final approved loan may be unchanged, but the timing creates a larger funding requirement.
This is why a total project profit calculation is not enough. Build a cash timeline showing completion, contractor payments, inspections, retained-funds release and first rent. A project can look profitable overall and still run out of money halfway through.
Make the example your own
What is the peak cash requirement?
A retained mortgage amount can increase temporary cash needs even when it is released later.
Assumes works are funded before the retention is released. Actual completion and drawdown terms govern. Illustrative only. Inputs stay in this page and are not saved or sent.
Specialist finance needs a credible exit
Where standard finance is unavailable, specialist refurbishment or bridging finance may be considered. It is a separate product with its own costs, conditions and risks, not a convenient way to postpone thinking about the long-term mortgage.
Before entering a short-term loan, establish how it will be repaid. If the exit is a buy-to-let remortgage, assess the expected completed condition, rent, value and borrower eligibility. If the exit is a sale, allow for marketing time, transaction costs and a weaker sale price.
The phrase “we will refinance when it is done” is a plan only when the assumptions have been examined. Ask what happens if work takes longer, costs more or fails to produce the anticipated valuation. Retain a fallback that you can actually fund.
Budget the refurbishment as a deliverable scope
Ask contractors to price the same specification so quotations can be compared. Include preparation, access, disposal, making good, certification and any professional costs. Specify who supplies materials and how variations are agreed.
Separate the base budget from contingency rather than spending the contingency on a better finish before work begins. A £25,000 budget with no remaining reserve is different from £25,000 of priced work plus cash for uncertainty.
My property refurbishment mistakes guide explains why a visually impressive result can still disappoint financially. The objective for a rental is a suitable, durable home with justified spending, not the largest possible before-and-after transformation.
Rent starts when the property is ready, not when you buy it
A three-month works programme may need additional time for investigations, permissions, contractor availability, inspections and letting. Even a well-managed project can have a gap between practical completion and rent collection.
During that period, finance, insurance, utilities and other responsibilities may continue. Check the insurance suits the occupancy and works rather than assuming an ordinary occupied-property policy is sufficient. Confirm any requirements with the insurer.
In the buy-to-let deal calculator, include initial void and holding costs consistently. If an allowance already includes an expense, do not add it again under another label. If it excludes something, give it its own line.
An end valuation is not a guaranteed refinance
Suppose you expect the finished property to be worth £170,000. At a hypothetical 75% LTV, that suggests £127,500 of gross borrowing capacity. If the accepted value is £155,000, the same percentage produces £116,250, a difference of £11,250.
The rent assessment may impose another limit. Refinancing costs and the amount owed on short-term finance further reduce usable cash. A forecast that ignores these deductions can turn a modest equity position into an imaginary cash windfall.
Use the property refinance calculator with a lower value and a higher rate as well as the preferred outcome. If the project only survives the highest valuation, revisit the purchase price, funding or scope before committing.
Keep permissions and finance aligned
The lender, insurer and relevant authorities may all have an interest in the work or change of use. A builder saying a conversion is straightforward does not establish that it is permitted or compatible with the mortgage.
Ask the solicitor and relevant professionals what consents, approvals and certificates are needed for this property and location. Planning, building-control and licensing questions are separate, and rules differ across the UK. Avoid carrying an assumption from one area into another.
If the intended strategy changes during the project, reassess the finance and permissions before proceeding. A plan to let a house as one home is not necessarily equivalent to operating an HMO or short-term accommodation.
Buy only when the sequence works
I would want a credible purchase route, sufficient cash for the peak funding requirement, a priced scope and a realistic exit. Each should still make sense under a delay or valuation setback.
If you want structured help understanding how to assess deals and plan the process, explore Blueprint. For the initial numbers, use the free calculators first. The right renovation project is one you can finance and complete properly, not simply one that looks cheap before the work is counted.
Frequently asked questions
Can I get a buy-to-let mortgage on a house with no kitchen?
Do not assume a standard product will accept it. The lender's condition requirements and valuation determine the position, and missing usable facilities can be material. Send the broker accurate information before making a funding commitment. A proposed new kitchen after completion does not establish that the property qualifies for the loan needed to buy it.
Can a mortgage pay for my rental-property refurbishment?
Some products may support specified works, but release amounts and timing vary. Standard purchase borrowing may leave you funding the work separately. Clarify whether money is advanced upfront, retained or released in stages. Your cash plan must cover contractor payments before any later release you are relying on.
What is a mortgage retention on a property needing work?
A retention is an amount the lender withholds subject to its conditions, often connected with required work or evidence. The approved gross loan and cash initially available can therefore differ. Ask exactly what releases the funds, who verifies completion and how you will fund the shortfall in the meantime.
Can I use bridging finance and remortgage after renovation?
That can be a possible structure, subject to suitable products and approval, but the exit needs assessment before the bridge is taken. Test the completed value, rent, fees, timetable and borrower eligibility. A delay or reduced refinance advance may leave a substantial amount to repay from other resources.
Does spending £30,000 renovating add £30,000 to the value?
Not necessarily. Value depends on the local market, starting condition, completed specification and comparable evidence. Some spending simply fixes defects or meets necessary standards. Separate the cost of work from the value assumption and ask whether the rental and resale evidence support the proposed improvement before treating it as created equity.
Should a first-time landlord buy a major refurbishment?
It depends on their capital, experience, professional support and capacity to handle delays and uncertainty. A project with several finance and construction dependencies is different from a ready-to-let purchase. Compare the extra potential return with the additional work, cash exposure and fallback options rather than assuming renovation is required to invest successfully.
Put the next step into practice
Use the free tools to test your numbers, then choose the level of support that fits your next decision.