How Do I Pay Myself From a Property Limited Company?
October 6, 2026
You can take money from a property limited company through different legitimate routes, but rent arriving in the company account is not automatically personal spending money. Salary, dividends, reimbursement of genuine expenses and repayment of money the company owes you each have different rules. The appropriate mix depends on your circumstances and professional advice.
For property planning, the important distinction is between company performance and household income. A portfolio can show a healthy rental surplus while providing less personal spending money than expected once tax, reserves and extraction are considered.
Follow the cash from tenant to household
Start with rent collected, then account for operating bills, finance payments, capital expenditure, tax provisions and the reserve the company needs to retain. This tells you something about cash available inside the business, not necessarily distributable profit.
Accounting profit and cashflow differ. A mortgage capital repayment uses cash but is not the same as mortgage interest. A major improvement may have a different accounting treatment from a repair. Rent due but not received can also create a gap between records and the bank.
Ask your accountant to reconcile those differences before deciding on withdrawals. A useful monthly report should show the bank position, forthcoming obligations, estimated tax and what can properly be paid to you.
A simple cash illustration
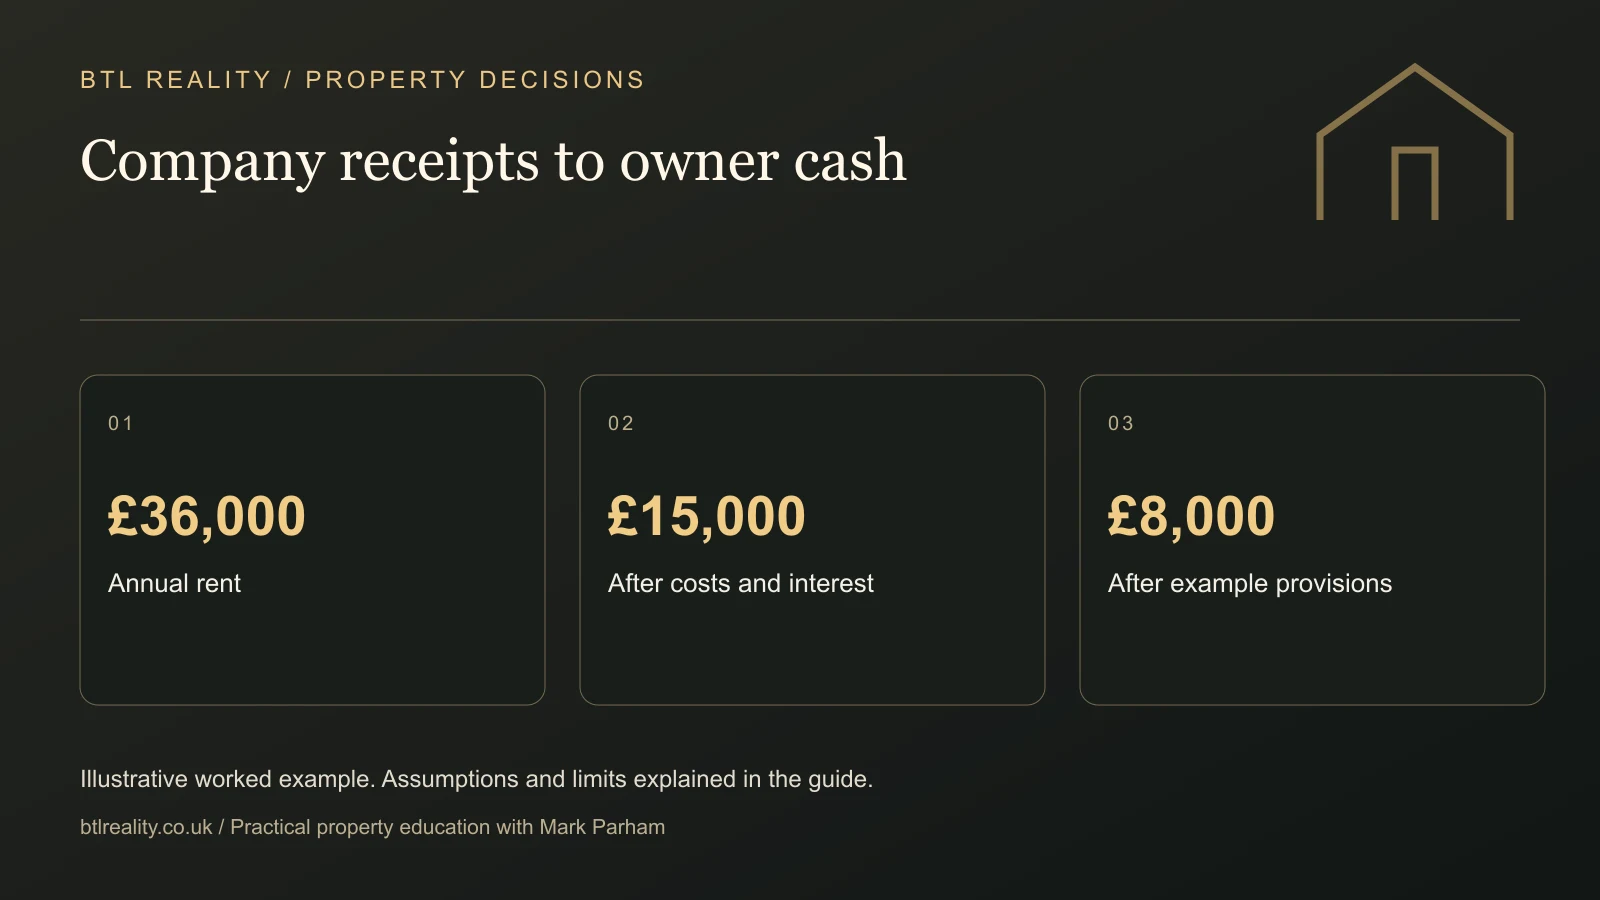
Imagine annual rent collected of £36,000. Assume £9,000 of operating spending and £12,000 of mortgage interest. That leaves £15,000 of cash before tax and other items in this simplified example.
Now ring-fence an illustrative £3,000 tax provision and £4,000 to strengthen the property reserve. The remaining cash is £8,000, approximately £667 per month. The tax provision is an example allowance, not a calculation of the company's liability.
Whether that £8,000 can be paid as a dividend depends on available distributable profits and the required process. If the company owes you money, some cash might instead repay that balance. The same bank balance can therefore support different lawful payments, each requiring correct records.
Make the example your own
Rent to cash: what is actually left?
This is a cash reconciliation, not a dividend or tax calculation.
Available company cash does not establish lawful distributable profits or personal after-tax income. Illustrative only. Inputs stay in this page and are not saved or sent.
Dividends depend on available profits
A dividend is a distribution to shareholders. It is not simply whatever remains in the bank after the mortgage payment. The company needs sufficient available profits and must follow the appropriate approval and documentation process.
GOV.UK's guidance on taking money out of a company explains the basic distinction between salary, dividends and directors' loans. Your accountant should confirm what can be distributed and how the payment affects the recipient's tax position.
Do not declare a dividend just because the property has risen in an online valuation estimate. An unrealised increase in market value does not automatically create cash or freely distributable profits. Keep the investment valuation separate from the accounting assessment.
Repayment of a director's loan is a different movement
If you previously lent money to the company, its records may show an amount owed to you. Repaying that genuine loan balance is conceptually different from paying you a share of rental profit.
For example, you might have introduced £50,000 towards a purchase and properly recorded it as a loan. If the company later repays £5,000, the recorded amount it owes you falls to £45,000. That transaction does not itself mean the rental produced £5,000 of new profit.
Check the balance with the accountant before making a payment. Money introduced as share capital, informal spending and a documented loan may not be interchangeable. Interest paid on a director's loan introduces further rules and should be assessed separately.
Do not confuse a loan repayment with borrowing from the company
The direction of the debt matters. If the company owes you, paying you can reduce that liability. If you withdraw more than is properly due through another route, you may instead owe the company money.
An overdrawn director's loan account can produce additional tax and reporting consequences. It should not become the default way to fund personal bills while waiting for a future dividend or refinance to make the records work.
HMRC's directors' loan guidance sets out the area to discuss with your accountant. The practical safeguard is to classify and authorise a payment before making it, rather than deciding what it was at the end of the year.
Salary is not automatically the best or worst choice
Salary involves employment and payroll considerations. The company and individual may have obligations that differ from those associated with dividends. Other employment income, allowances and the work performed can influence the calculation.
It is common to hear a particular salary-and-dividend combination presented as universally optimal. That ignores changes in rates, personal circumstances, residence, company results and other income. An approach suitable for one owner can be unsuitable for another.
Ask for a current comparison based on your actual position. The objective is lawful, sustainable household income after all relevant costs, not copying a figure from someone else's video or an old tax-year example.
Reimburse genuine business expenses properly
If you personally pay a legitimate company expense, retain the invoice and record why it belongs to the company. Reimbursement should reflect the actual expense and applicable rules, not become a convenient description for personal spending.
Mixed-purpose costs require care. A trip involving both personal time and business activity, or an item used privately as well as commercially, may need a more detailed assessment. Ask before assuming the company can simply pay the whole bill.
Use separate accounts and consistent bookkeeping. Clear records make it easier to understand the portfolio and reduce the risk of counting a personal withdrawal as a property operating cost in your investment analysis.
Refinancing does not make company money personal
Suppose the company refinances a property and receives £30,000 after repaying the old loan and transaction costs. The cash balance rises, but the company also has more mortgage debt. That is not £30,000 of rental profit.
If the company owes you a genuine director's loan, there may be a route to repay some of it, subject to advice and the company's position. If it does not, you cannot assume the entire release can be transferred personally without further consequences.
The property refinance calculator illustrates loan and cash movements. It does not determine the legal or tax route from a company to a shareholder. Keep that additional step in the household-income plan.
Set a withdrawal policy that protects the property
Decide what cash must remain for tax, known repairs, mortgage resets and empty periods before setting a regular personal transfer. A stable monthly amount below the expected surplus can be easier to manage than withdrawing every good month's balance.
Review it when rents, costs or borrowing change. If a large repair uses the reserve, rebuilding that reserve may take priority over increasing withdrawals. The company needs to remain able to meet its obligations even when you are depending on it for income.
The Financial Freedom Calculator helps organise the lifestyle target, but replace simplified tax and cash assumptions with professionally checked figures before relying on a retirement date.
What to ask your accountant
Ask for the current director's loan balance, available distributable profits, forecast tax liabilities, payroll implications and the estimated personal result under suitable withdrawal routes. Explain whether you want occasional capital repayments or a dependable monthly income, because those are different objectives.
For a broader property plan, Private Mentorship can help connect assets, borrowing and lifestyle aims. Tax planning remains with an appropriately qualified adviser. The outcome to pursue is a clear route from rent to usable household money, with the company and its properties properly funded throughout.
Frequently asked questions
Can I transfer rental income from my company to my personal account?
Only through an appropriate, properly recorded route. The transfer may be salary, a dividend, expense reimbursement or a genuine loan repayment, depending on the facts. Decide its treatment before paying it and confirm the company's ability to meet obligations afterwards. Calling a transfer “drawings” does not settle the accounting or tax position.
Can I pay myself dividends every month from a property company?
Frequency is not the main test. The company must have sufficient available profits and follow the required process for each distribution. Ask the accountant how to support and record interim decisions using up-to-date figures. A regular bank transfer cannot become a lawful dividend merely because the company usually receives rent monthly.
Is repayment of my director's loan the same as a dividend?
No. Repaying a genuine amount the company owes you reduces that recorded liability; a dividend distributes profits to shareholders. Confirm the loan balance and documentation with your accountant. Do not reclassify money after the event simply because one description appears more favourable, and keep any interest arrangement separate from repayment of principal.
Can I take a refinance release out of my property company tax-free?
Do not assume that. The mortgage creates company cash and debt, while the route to you depends on the company's records and circumstances. A genuine loan repayment is different from a dividend or borrowing from the company. Have the complete transaction assessed, including future interest and liquidity, before treating the release as personal money.
Should I pay myself salary or dividends from a property company?
There is no universal answer. Other income, available profits, payroll obligations, residence and current tax rules affect the comparison. Ask for a calculation based on your actual position and planned withdrawals. An old online example or another landlord's arrangement is not enough to choose a suitable mix for yourself.
How much cash should I leave inside the property company?
Allocate money to forecast tax, operating bills, likely repairs, vacancy exposure and finance changes before setting personal withdrawals. The amount depends on the properties and other support available. Keep company reserves separate from household reserves, review them after major spending and avoid counting one pot as protection for several simultaneous commitments.
Put the next step into practice
Use the free tools to test your numbers, then choose the level of support that fits your next decision.