Can I Live Off Remortgaging Rental Properties?
October 5, 2026
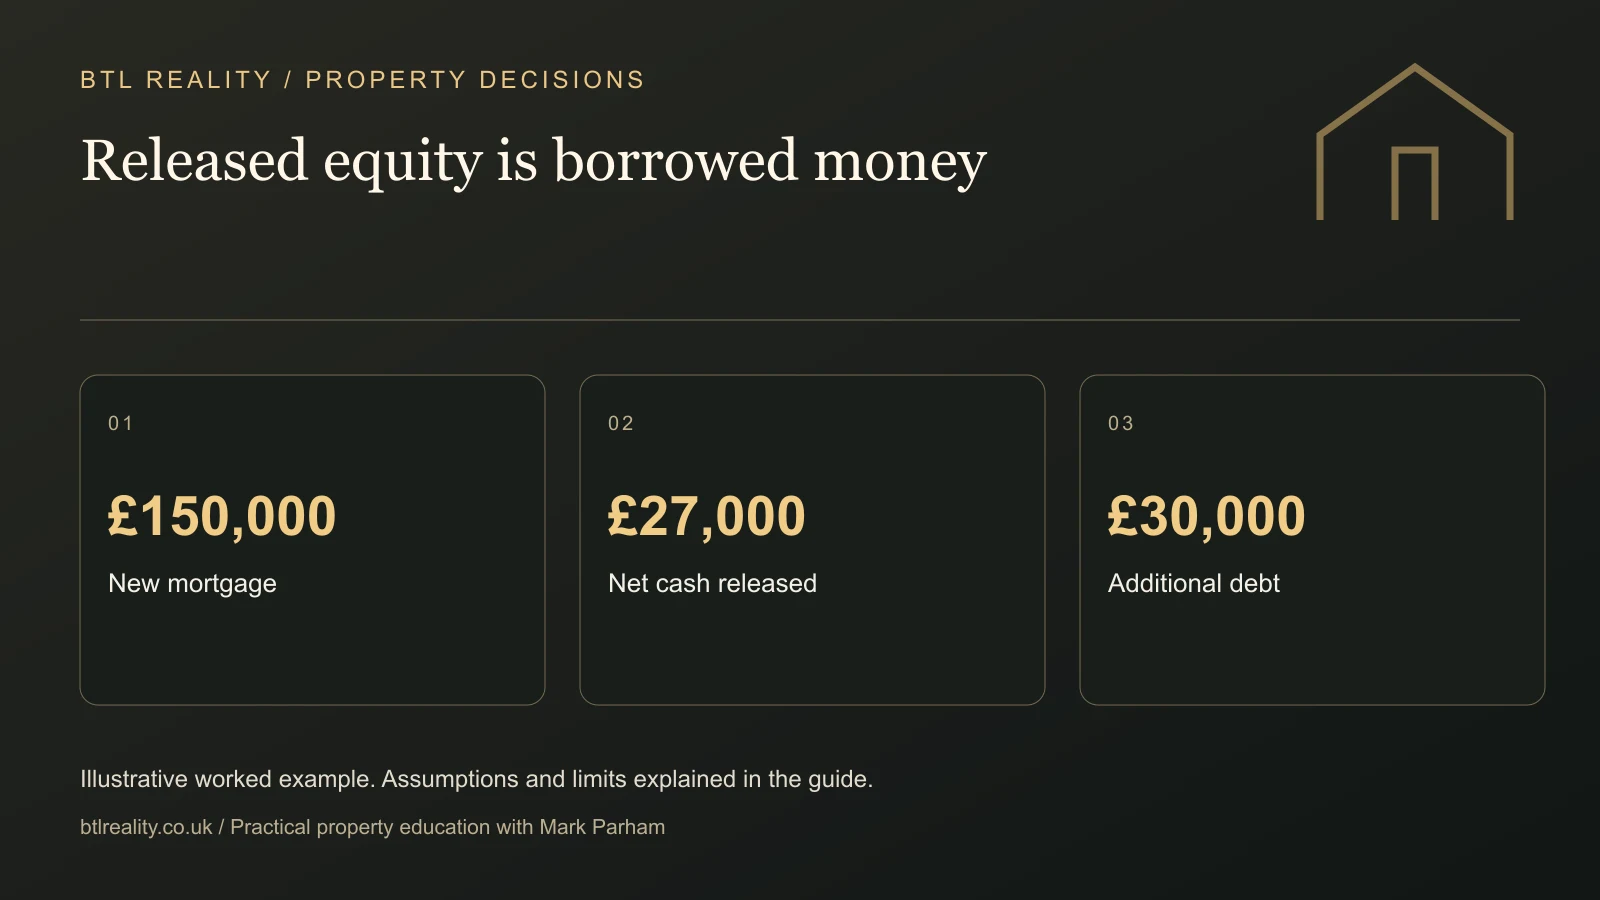
You may be able to use money released by remortgaging rental property for living costs, but it is borrowing, not rental income. Whether a lender permits the purpose and approves the loan depends on the application. A lifestyle funded partly by repeated refinancing carries different risks from one covered by net rent alone.
The idea is attractive: values rise, you release some equity and keep the properties. The difficult part is ensuring the cash lasts between transactions while the larger debt remains affordable. A model should show that whole process, not simply draw a rising property-value line.
Where the money actually comes from
When you refinance, a new loan normally repays the old secured balance and associated costs. Only the remaining amount becomes available cash. You have exchanged some equity for a larger liability.
Suppose a property is valued at £200,000 and the existing mortgage is £120,000. A hypothetical 75% refinance would create a £150,000 loan. After repaying £120,000 and allowing £3,000 of refinancing costs, the usable release is £27,000.
The property has not generated £27,000 of operating profit. You owe £30,000 more than before, and the cash released is smaller because of the costs. That distinction should remain visible on every forecast and report.
What does the larger loan do to the rent?
At an illustrative 5% interest rate, £120,000 of interest-only debt costs £6,000 a year. £150,000 costs £7,500. The additional annual interest is £1,500, or £125 a month, assuming the rate itself does not change.
If the property previously produced £500 a month after operating costs and mortgage interest, it now produces £375 before tax under those unchanged assumptions. A different refinance rate could improve or worsen the result further.
This is the common modelling mistake: taking cash out but leaving the original mortgage cost in the forecast. The release then appears to fund lifestyle without reducing future rental cashflow. In reality, both sides must change together.
Make the example your own
How much lifestyle runway does a release buy?
Model a property refinance separately from rent. The new debt still needs servicing and eventual repayment.
Runway excludes any extra interest after refinancing. Subtract that from rent and increase the gap before using this for planning. Illustrative only. Inputs stay in this page and are not saved or sent.
How long might the release fund the gap?
Suppose your household needs £2,500 a month and dependable net income after the refinance is £1,500. The shortfall is £1,000 a month. A £27,000 release would cover 27 months of that fixed gap, before any additional reserve allocation or unexpected expense.
If you ring-fence £7,000 for property and household contingencies, £20,000 remains for spending, covering 20 months. That is a cash runway, not permanent financial freedom. To continue the same spending, something must change before the money runs out.
Possible changes include higher net rental income, lower spending, other income, a property sale or another approved refinance. Each should be shown explicitly rather than hidden behind a generic “capital growth” assumption.
A two-year refinance interval is not a promise
You can model an intention to review refinancing every two years. That does not mean the property will support a worthwhile release every two years. Value, debt, rent, lender criteria, fees and any early repayment charges all affect the result.
At the next review, assume the property is still worth £200,000 and the mortgage is already £150,000. At 75% LTV there is no additional borrowing capacity before fees. The passage of two years has not created cash by itself.
If the value rises to £220,000, 75% is £165,000. Against £150,000 existing debt and £3,000 costs, the release is £12,000. A model with a £15,000 minimum useful release would correctly decline that transaction. Increasing the value assumption merely to force a release would hide the weakness.
Future lending is a separate dependency
The lender must accept the property, borrower, rental position and purpose of borrowing at the time. Retirement, residency changes, portfolio size and the intended term can all make the future application different from the original purchase.
The Mortgage Works' general criteria illustrate how lenders set conditions for capital raising and remortgaging. One lender considering a category of borrowing does not establish that your future application will pass or that the use of funds will be accepted.
Discuss the purpose with a qualified mortgage adviser. Do not present living-cost borrowing as money for a different purpose. If the plan depends on continued lending, that dependency belongs prominently in the decision, not in the small print.
Compare rent-only funding with rent plus borrowing
Under a rent-only lifestyle, the recurring spending target must be covered by the net rental money available for that purpose. Refinancing may still form part of an investment strategy, but it is not used to disguise a household income shortfall.
Under a rent-plus-capital approach, periodic cash releases or investment withdrawals can fund part of the spending. That may bring a modelled start date forward, but the plan needs enough liquidity, realistic lending assumptions and a workable response if releases stop.
Our Financial Freedom Calculator separates these choices. Compare the start date alongside property value, debt, equity, spending and the longer-term funding check. The earliest date is not automatically the strongest plan.
Avoid counting the same money twice
Suppose you release £27,000 and use £20,000 for living costs. You do not still have £27,000 available for the next purchase. The remaining £7,000 may already be allocated to reserves.
Similarly, if the model uses rental profit to fund household spending, that profit cannot simultaneously be reinvested in another deposit. Once you start enjoying the money, the growth path changes. A useful forecast compares the spending path with continued accumulation rather than pretending they are identical.
In my discussion of refinancing to build a property portfolio, the focus is deploying capital towards investment. Spending released capital on lifestyle is a different use, and it deserves a separate assessment.
Tax and ownership still need checking
Borrowed money is not the same as rental profit, but that does not make every aspect of the arrangement tax-neutral. The purpose of borrowing, ownership structure and how money reaches you can affect the treatment of costs and withdrawals.
If the property belongs to a company, a refinance paid into the company account does not automatically become personal spending money. If you own the property personally, the treatment of borrowing costs still requires care. Ask an accountant to review the actual proposal rather than applying a blanket rule about refinancing being “tax-free income”.
Keep tax and legal advice separate from the educational model. The calculator can explain cash movements but cannot determine all consequences of a particular transaction.
The stress tests that matter most
Run a period of no capital growth, a higher mortgage rate, a lower refinance valuation and a larger repair bill. Then test a scenario in which no further equity can be released. Record the first month the spending account needs support and what you would do before that point.
Also plan the eventual repayment of interest-only debt. Repeatedly extending a mortgage is not a guaranteed exit strategy. Selling, reducing debt or using other assets may form part of the answer, with costs and tax included.
Use the property refinance calculator for each proposed transaction and the freedom calculator for the wider lifestyle. For support examining a more complex portfolio, read the Private Mentorship scope and application criteria. A good plan should make the borrowing visible, not make it disappear behind an attractive retirement date.
Frequently asked questions
Is money released by remortgaging a rental property income?
It is loan proceeds, not rental operating income. The release increases available cash while normally increasing debt or changing its terms. Tax consequences and interest treatment still need professional assessment. A lifestyle model should show the release separately from rent and deduct the resulting finance costs from future cashflow.
Can I remortgage every two years to pay living costs?
You can plan to review the position at that interval, but cannot guarantee a worthwhile or approved release. Future values, rent, criteria, fees and loan terms matter. If the property value does not rise enough, there may be no usable cash after costs even though two years have passed.
What happens if house prices stop rising while I live off equity?
Further releases may shrink or stop, depending on the debt and lending position. Existing cash can then be depleted by any gap between spending and recurring income. Test how long the reserve lasts and identify realistic responses in advance. Continuing the same lifestyle cannot simply be assumed when its funding source disappears.
Is 75% LTV better than 55% for financial freedom?
Higher borrowing may release more capital but usually increases interest exposure and leaves less equity protection. Lower borrowing can support stronger rental cashflow but ties up more capital. Compare the date, income, debt and resilience together. The higher-LTV route should not be labelled better solely because an optimistic model reaches a target sooner.
Can I spend a refinance release and keep growing the portfolio?
Potentially, but only the money remaining after spending, costs and reserves can be reinvested. Future growth also depends on rents, values and finance. A model must allocate each pound once. Compare the spending path against continued reinvestment to see the trade-off instead of assuming identical portfolio growth under both choices.
Does refinancing avoid the need to sell property in retirement?
It may postpone a sale in some circumstances, but it does not remove the need for a debt repayment and exit plan. Interest-only mortgages eventually reach maturity, and further borrowing may be unavailable. Review potential sales, debt reduction and other funding sources with their costs, rather than relying on indefinite mortgage renewals.
Put the next step into practice
Use the free tools to test your numbers, then choose the level of support that fits your next decision.