Can I Use a Gifted Deposit for a Buy-to-Let?
October 5, 2026
A gifted deposit can be accepted for a buy-to-let mortgage, but the lender must accept the donor, the source of the money and the terms of the gift. Do not assume a family member offering to help means the finance is sorted. The solicitor and lender still need the transaction explained properly.
The practical aim is to turn a generous offer into a purchase you can afford to own. That means looking beyond the deposit itself: costs, reserves, who legally owns the property and whether anyone expects their money back.
Establish whether it is a gift or a loan
A genuine gift and a family loan are different arrangements. If your parents expect repayment from the next refinance, that expectation needs to be disclosed. Calling the money a gift on a form while privately promising repayment does not solve the finance problem.
Similarly, someone contributing money in return for an ownership share is not simply giving a deposit. Their interest may affect the mortgage application, legal ownership and tax position. Tell the broker and solicitor the real arrangement before choosing a product.
The conversation can feel awkward within a family, but it is easier before money moves. Write down whether repayment is expected, whether the donor wants security or an interest in the property, and whether the buyer can make decisions without consulting them.
Each lender defines acceptable help differently
As one current example, Accord's buy-to-let deposit criteria permit certain family cash gifts and distinguish these from sources it does not accept. That is evidence that gifted deposits can work, not a promise that every proposed donor or purchase will qualify.
A gift from a parent, a friend, a company or a person overseas may receive different treatment. The mortgage product, borrower, ownership structure and deposit percentage can matter too. Criteria can change between planning the purchase and submitting the application.
Ask a broker to check the proposed gift before paying a reservation or sourcing fee. Give them the amount, donor relationship, country where the funds are held and whether the money is already available. An answer based on those details is much more useful than a generic “gifted deposits are fine”.
Work out the full cash requirement
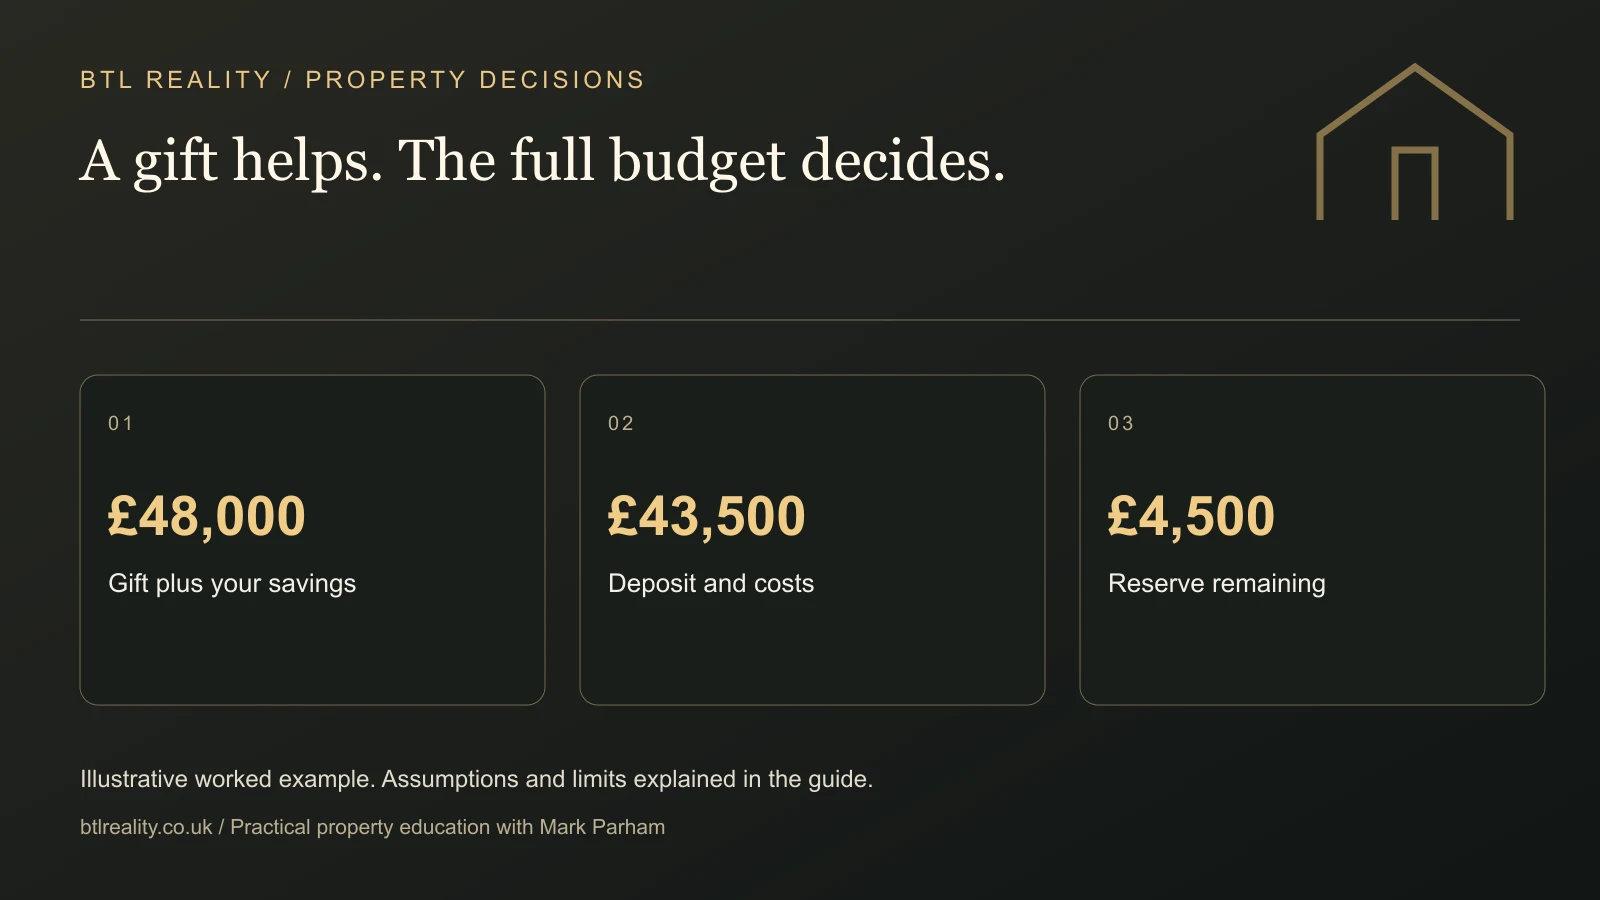
Imagine a £140,000 buy-to-let with an illustrative 75% mortgage. The purchase-price contribution is £35,000. A relative offers £30,000 and you have £18,000 of your own money, giving £48,000 in total.
On the deposit alone, you appear to have £13,000 left. Now allow an illustrative £8,500 for purchase costs and initial work. That leaves £4,500 for your property reserve and any household money you need to protect. The gift has helped substantially, but it has not removed the need to budget.
If your target property reserve is £7,000, you are £2,500 short of the intended allocation. You might save longer, change the purchase budget or reassess costs using firm quotations. Quietly deleting the reserve line makes the spreadsheet balance without improving your position.
Use our buy-to-let deal calculator to list the deposit, fees, work and cash retained. Calculate purchase taxes for your actual circumstances using the stamp duty calculator, then confirm the treatment with your solicitor.
Make the example your own
Does the gift cover the whole purchase?
Include fees and a reserve before deciding whether the funding is sufficient.
Illustrative only. Inputs stay in this page and are not saved or sent.
Prepare the evidence before the deadline
The lender and solicitor will specify the documents they need. Common areas of enquiry include the donor's identity, relationship to you, where the funds came from, the account trail and written confirmation of the arrangement. Follow their actual requests rather than using a random online letter as definitive.
Money accumulated from salary has a different history from money recently received through a business sale or another property sale. Keep the supporting records accessible. Moving funds between several accounts without a clear explanation can make the trail harder to follow.
Do not redact relevant transactions or describe borrowed money as savings to simplify the paperwork. If something looks complicated, explain it early. A professional can tell you which evidence is necessary and how to provide it securely.
An overseas gift needs extra planning
A donor living abroad may be able to help, but you need to check lender acceptance, identification requirements, currency conversion and transfer timing. The relevant professionals may need more time to verify documents or explain unfamiliar records.
Budget the amount that reaches the required account after exchange costs and fees. A promise to send a foreign-currency amount is not the same as a guaranteed sterling sum. Leave time for the transfer to clear and for the receiving institution to complete its checks.
Keep any tax questions separate from mortgage eligibility. A lender accepting a gift does not establish that it has no tax consequences for anyone involved. Cross-border circumstances can introduce obligations in more than one country, so the donor may need advice as well as the buyer.
Discuss the family risks openly
Property can fall in value, repairs can arrive early and a refinance may not happen when expected. If the gift is essential retirement money for the donor, those risks deserve a more careful conversation than “the rent will cover everything”.
Even a legally unconditional gift can create emotional expectations. The donor may assume they can stay at the property, approve tenants or insist on a sale. Those assumptions could clash with the mortgage, tenancy or your investment plan.
Ask the solicitor how the intended arrangement should be documented and whether the donor should receive independent advice. The goal is clarity for everyone, rather than a document that disguises a more complicated understanding.
Do not promise to repay the gift through refinancing
If repayment is part of the agreement, describe it honestly as such. If repayment is merely something you would like to do voluntarily in future, do not build the donor's finances around it happening.
A refinance depends on valuation, rent, affordability, lender policy and costs at the time. Borrowing more also changes the property's interest bill. Our property refinance calculator can illustrate the mechanics, but it cannot create a mortgage offer.
I would want the purchase to stand on its own rental and cash position first. A family contribution should improve resilience, not become the reason to take on a project that only works if the best possible refinance result arrives immediately.
Questions to take to your broker and solicitor
- Does the lender accept this donor, relationship and source of funds for this specific application?
- What written confirmation and identification will each professional require?
- Can the donor retain any interest, repayment right or security, and what would that change?
- When must the funds be available, and in which account?
- Have all costs and a retained reserve been included alongside the deposit?
- Are there tax or cross-border issues the donor and recipient should review separately?
Keep answers and documents together. If the donor's circumstances, purchase price or ownership plan changes, tell the professionals rather than assuming the original assessment still applies.
Make the help count
A gifted deposit can bring a first investment closer. The best use of that opportunity is a well-understood purchase with realistic borrowing, adequate cash and clear family expectations.
Start with the free calculators and the guide to how much money you need to start property investing. If you want support building a practical plan around your starting position, explore Starter Club. The education can help you organise the decision; mortgage, legal and tax questions still belong with the relevant professionals.
Frequently asked questions
Can my parents gift the whole buy-to-let deposit?
Some lending routes may accept a qualifying family gift covering the required deposit, but approval depends on the lender's policy and the whole application. Confirm the proposed amount and donor relationship with the broker. You still need to account for purchase costs, reserves and any conditions relating to your own contribution.
Can a friend gift me a buy-to-let deposit?
Do not assume a friend is treated like an accepted family donor. Lender definitions vary and some exclude non-family gifts. Explain the relationship, source and terms before choosing a product. If repayment or ownership rights are expected, disclose them rather than presenting the arrangement as an unconditional gift.
What should a gifted deposit letter say?
Use the lender's and solicitor's requirements. They may need the amount, parties, relationship and confirmation of the actual gift terms, alongside identity and source evidence. A letter cannot make a repayable loan into a gift. Ask the professionals to confirm the format instead of copying a template that may omit material details.
Can gifted deposit money come from overseas?
It may be possible, subject to lender acceptance and the required checks. Allow time for identity verification, source-of-funds evidence, translation where required and currency transfers. Confirm the sterling amount available after fees. The donor and recipient may also need advice about tax or reporting obligations in the countries involved.
Can I repay a gifted deposit after remortgaging?
If repayment was agreed from the start, tell the lender and solicitor because the arrangement may be a loan rather than a gift. A later voluntary payment is a separate matter to discuss appropriately. In either case, do not promise a refinance outcome before the future valuation, borrowing and costs are known.
Does a gifted deposit remove the need for savings?
No. Even where the deposit is fully provided, you need a complete plan for costs, vacancies, repairs and household resilience. Borrowing the maximum and using every available pound at completion can leave you exposed. The helpful question is whether the entire ownership budget works, not simply whether the deposit box is ticked.
Put the next step into practice
Use the free tools to test your numbers, then choose the level of support that fits your next decision.