Buy-to-Let: Limited Company or Personal Name? My Approach
September 4, 2026
If I were starting my property portfolio again, earning a decent income and planning to build a sizeable business with mortgages, I would use a limited company. But that isn’t the same as saying every landlord should do it. The right structure depends on what you’re building and when you want to spend the money yourself.
I own more than £3.5 million of property across personal ownership and limited companies, so I’ve lived with both sides. The difference becomes particularly noticeable when you compare the tax treatment of mortgage interest. A company can leave you with more money to reinvest, but there’s a catch: money in the company belongs to the company.
This article follows my video published on 4 September 2026. The tax example uses the 2026/27 position and deliberately rounded figures. I’m explaining how I think about the decision, rather than giving you a structure to copy without an accountant checking your circumstances.
You can also watch my limited company versus personal name video on YouTube.
The mortgage interest difference
Let’s start with the reason this question matters so much to investors using debt. For an individual who owns residential rental property, mortgage interest generally isn’t deducted in the normal way when calculating taxable rental profit. Instead, there’s a basic-rate finance-cost tax reduction, subject to limits.
That can create a surprisingly large gap between the cash your property produces and the profit figure used in your tax calculation. If you’re already a higher-rate taxpayer, you can end up paying tax on an amount substantially greater than the cash left after the mortgage interest has gone out.
A company normally calculates its taxable profit after deducting allowable mortgage interest. That doesn’t automatically make it the winner, because corporation tax, borrowing costs, administration and extracting the money all need considering. But it changes the starting point significantly.
This is why comparing the headline personal tax rate with the corporation tax rate isn’t enough. I want to see how much actual cash remains, where that cash sits and what I’m allowed to do with it next.
My £150,000 buy-to-let example
In the video, I used a property costing £150,000 with a 75% mortgage. That means borrowing £112,500 and putting in a £37,500 deposit, before purchase costs. At an illustrative interest rate of 5.5%, the annual interest is £6,187.50, which I rounded to £6,200 to keep the explanation manageable.
Assume rent of £1,100 a month, or £13,200 a year, and another £2,000 for management, insurance, maintenance and the other running costs. Using the rounded interest figure, the property produces £5,000 of annual cash profit before tax.
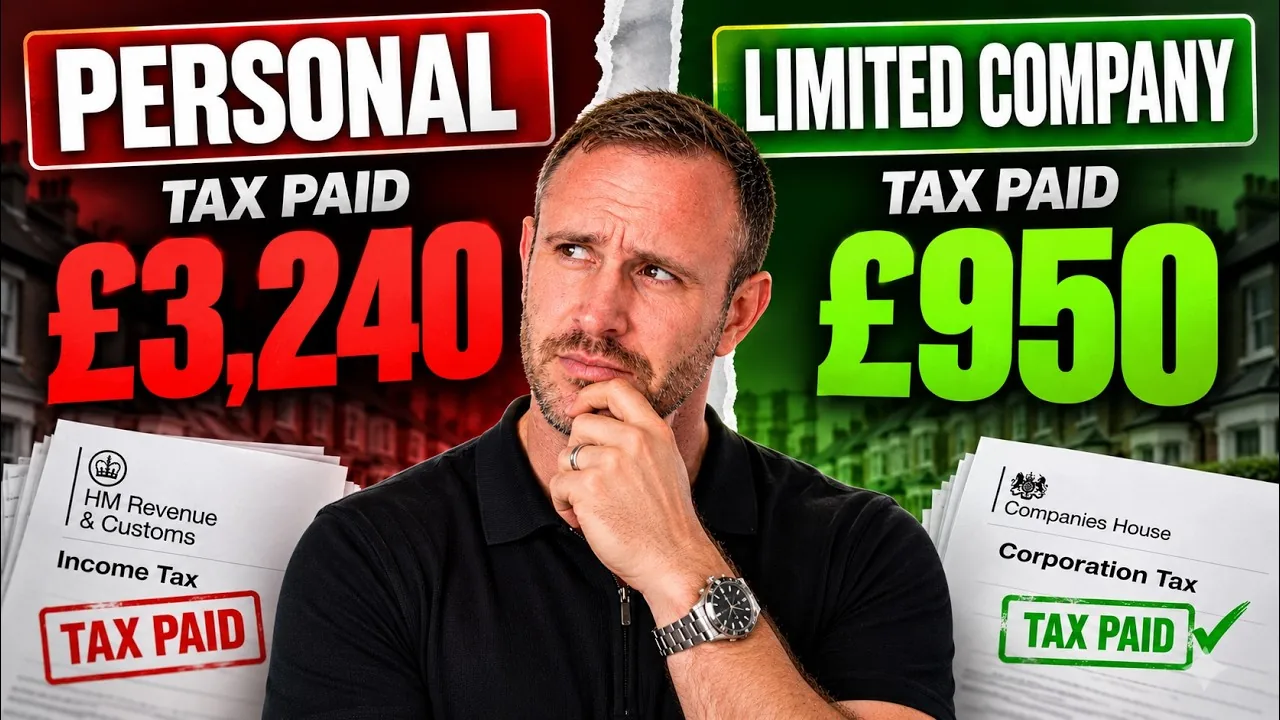
For a personal owner already paying 40% tax on all this additional income, the taxable rental profit before finance-cost relief is £11,200. Tax at 40% comes to £4,480. The illustrative 20% reduction on £6,200 of finance costs is £1,240, leaving £3,240 to pay.
That takes the £5,000 cash profit down to £1,760 after personal tax. These are rounded teaching figures, and the result assumes the tax reduction is available in full. Your other income, allowances and the relief limits can change the calculation.
Now put the same rental activity inside a company. If it qualifies for the 19% small-profits corporation tax rate, tax on the £5,000 profit is £950. That leaves £4,050 inside the company. In the video I described that as about £4,000, compared with £1,760 personally.
The qualification matters. Corporation tax isn’t always 19%: the main rate is 25%, with marginal relief potentially applying between the relevant thresholds. Associated companies and other conditions can affect those thresholds. I wouldn’t build a portfolio forecast on the assumption that every pound of future profit will stay in the smallest tax band.
Why retaining profits helps me grow
The advantage becomes more interesting when you think beyond one property. If I don’t need the rental income to fund my lifestyle, money retained inside the company can help pay for the next deposit, refurbishment or purchase costs.
Across several properties, retaining more cash may bring the next purchase forward. Then that property can contribute rent as well. That is the appeal for me: I want the portfolio to help finance its own growth over time.
It still needs to be real surplus. Money earmarked for tax, repairs or an upcoming mortgage payment isn’t spare capital just because it’s sitting in the bank. I would separate those commitments before deciding what is available to invest again.
I’ve explained the wider approach in my three-step property investment plan. The structure needs to support that plan. It doesn’t replace finding good properties, borrowing sensibly or keeping enough cash to deal with a difficult year.
The money in the company isn’t automatically yours
Suppose the company has £50,000 in its bank account. You cannot simply treat that as £50,000 of personal spending money. There needs to be a legitimate way of taking it out, properly recorded and taxed where required.
That might involve salary, dividends or repayment of money you previously lent the company through a director’s loan account. Repaying genuine loan principal is different from paying a dividend, but you need the underlying records and an actual amount owed to you. It isn’t a label you can attach to any withdrawal you fancy.
There may be another tax charge when company profits become personal income. That is why the £4,050 company balance in my example isn’t directly equivalent to £4,050 in your own pocket. Compare the full journey, including extraction, before deciding the company has saved you a particular amount.
At 43, I still want spare capital going into the next property. At 55 or 60, I might want something different. The structure that helps me expand needs an exit and income plan as well.
Refinancing creates the same distinction
Imagine the £150,000 property eventually becomes worth £250,000. With the original interest-only balance of £112,500 still outstanding, a new 75% mortgage would be £187,500. The difference is £75,000 before refinancing costs, assuming the lender accepts the valuation and borrowing.
If the property is personally owned, the released funds come to you. If the company owns it, the funds go into the company. Buying another property within that company may fit the plan perfectly. Spending the money personally brings you back to the extraction question.
Either way, the £75,000 is additional borrowing. It isn’t rent, sale profit or money created without a corresponding liability. The new interest bill has to fit the rental income, and the lender may restrict the amount even if the headline loan-to-value calculation looks fine.
That distinction becomes especially important when planning retirement. My property retirement plan starts with the income I want available personally, because owning assets and having spendable income are different things.
When personal ownership can make sense
If I wanted just one or two rentals, used little borrowing and wanted the income personally, I would be quite comfortable considering ownership in my own name. The company advantage may be smaller once you account for the extra costs and administration.
Company mortgages can have different rates, fees and lender requirements. You also have company accounts, filings and accountancy costs. I would ask a broker to compare actual offers for both structures instead of assuming that the borrowing will cost exactly the same.
Personal ownership can also be more straightforward to understand and manage. That simplicity has value. A small tax advantage on paper isn’t particularly exciting if extra costs absorb it or the structure makes getting your money out unnecessarily awkward.
Conversely, someone with a substantial income, significant mortgages and plans for five, ten or twenty properties may find a company much more attractive. The question I would ask is what you’re trying to build over the next twenty years, and when you expect to use the income.
Moving existing properties is a separate decision
Buying your next property through a company is very different from transferring properties you already own. A transfer can bring capital gains tax, property transaction taxes, refinancing charges and legal fees into play. Reliefs may exist in particular circumstances, but they need specialist assessment.
I’ve personally looked at moving some of my own properties into my company. The numbers didn’t justify it. That is why I still hold property in both structures rather than forcing everything into one neat arrangement.
I wouldn’t let a general argument in favour of companies persuade me to create a large immediate bill without a proper comparison of the long-term benefit. The existing loans, purchase history and individual properties matter as much as the headline tax rules.
My three-part approach to the decision
First, decide the scale and purpose of the portfolio. In the video I mentioned £1 million of assets as a rough point where the conversation can start looking more like building a property business. That is my rule of thumb, not a tax threshold or a requirement for using a company.
Second, if a company suits the plan, retain as much capital as reasonably possible while building. Buy well, improve where appropriate, keep the rental surplus and refinance carefully. Leave enough flexibility to handle the years that don’t follow the spreadsheet.
Third, plan extraction long before you need it. Your other income, future employment and residence can all affect that plan. Overseas residence can change the treatment of dividends, but it doesn’t make tax disappear automatically. Genuine residence, local rules, treaties and temporary non-residence provisions need specialist advice.
The rules are also changing. HMRC sets out separate property-income rates of 22%, 42% and 47% from April 2027 for England, Wales and Northern Ireland, with devolved arrangements requiring attention. You can read the official explanation of the property-income tax changes. That is another reason to have the whole plan checked rather than relying on today’s simplified example.
If you’d like to talk through what you’re trying to build, book a free property strategy call. You can also explore Starter Club or Done For You and a 20-minute suitability call. My aim is to connect the ownership decision to your actual goals, so that the property business you build can eventually pay for the life you want.